Call CA Tally HelpDesk
+91 9205471661,
7428779101
Introduction: Why Understanding Partners' Accounts Matters in 2026
Every successful partnership begins with trust, shared responsibilities and a common vision. However, as businesses grow, managing partners' financial contributions, withdrawals, remuneration and profit shares becomes increasingly complicated.
In 2026, Indian partnership firms face growing expectations for accurate financial records, transparent profit distribution and dependable accounting practices. Whether operating a wholesale business, manufacturing unit, professional consultancy or family enterprise, partners need to understand exactly how much money they have invested and how much they are entitled to receive.
Two important accounting records help maintain this clarity: the Partner's Capital Account and the Partner's Current Account.
Although both relate to a partner's financial interest in the firm, they serve different purposes.
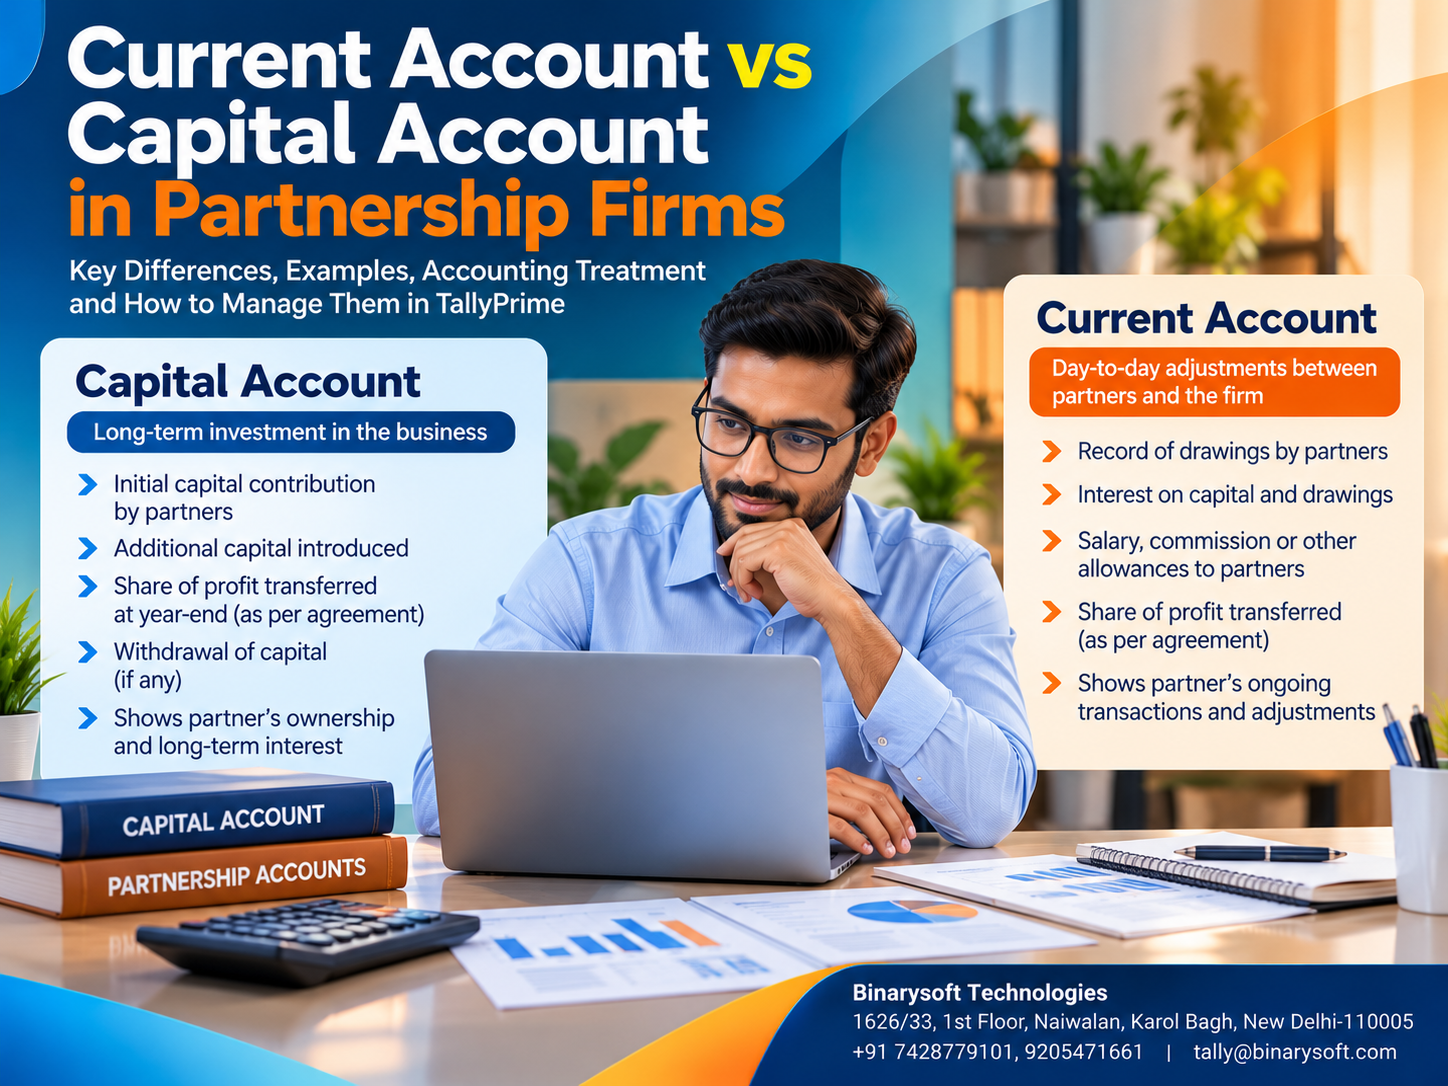
The capital account generally records long-term capital invested in the partnership. The current account records periodic adjustments such as drawings, interest on capital, remuneration and profit or loss allocations under the fixed capital method.
Confusing these accounts can lead to incorrect financial statements, misunderstandings between partners and complications during retirement or restructuring.
TallyPrime helps partnership firms maintain separate ledgers, record financial transactions and generate reports for monitoring partner balances.
This guide explains the differences between current and capital accounts, their accounting treatment, practical examples and how businesses can manage them efficiently.
1. What Is a Capital Account in Partnership Accounting?
A capital account records the amount of money or assets contributed by a partner as investment in a partnership firm.
It represents the partner's capital interest in the business and helps establish the financial contribution made toward business operations.
For example, suppose two partners establish a wholesale trading company.
Rahul contributes ₹10,00,000, while Amit contributes ₹8,00,000.
Their initial capital accounts will reflect these contributions separately.
Main Features of a Capital Account
A capital account records the initial investment introduced by a partner.
It may also record additional permanent capital contributions or permanent reductions in capital.
Under the fixed capital method, routine adjustments such as drawings and profit shares are maintained separately.
The account therefore provides a relatively stable record of the partner's long-term investment.
Example
Rahul introduces ₹10,00,000 into the partnership through the bank.
The accounting entry is:
|
Particulars
|
Debit
|
Credit
|
|---|
|
Bank Account
|
₹10,00,000
|
|
|
Rahul's Capital Account
|
|
₹10,00,000
|
This transaction increases the firm's bank balance and records Rahul's capital contribution.
2. What Is a Current Account in Partnership Accounting?
A partner's current account records periodic financial adjustments between the partner and the partnership firm.
It is generally maintained when the firm follows the fixed capital method.
Instead of changing the original capital contribution for every transaction, the firm records routine adjustments in a separate current account.
Transactions Recorded in a Current Account
Common transactions include:
-
Partner's share of profit or loss.
-
Interest on capital.
-
Interest on drawings.
-
Partner remuneration or commission.
-
Personal withdrawals.
-
Other agreed partner-related adjustments.
For example, Rahul may have invested ₹10,00,000 as fixed capital but withdrawn ₹50,000 for personal use during the year.
Under the fixed capital method, this withdrawal is debited to Rahul's current account rather than permanently reducing his capital account.
This separation makes it easier to distinguish invested capital from routine financial movements.
3. Current Account vs Capital Account: Key Differences
|
Basis
|
Capital Account
|
Current Account
|
|---|
|
Purpose
|
Records long-term capital
|
Records periodic adjustments
|
|
Nature
|
Partner's investment
|
Partner's running balance
|
|
Balance
|
Generally fixed under fixed method
|
Changes with transactions
|
|
Initial investment
|
Recorded here
|
Not normally recorded
|
|
Additional permanent capital
|
Recorded here
|
Not normally recorded
|
|
Drawings
|
Usually excluded under fixed method
|
Debited
|
|
Interest on capital
|
Usually excluded under fixed method
|
Credited
|
|
Partner remuneration
|
Usually excluded under fixed method
|
Credited
|
|
Profit or loss share
|
Usually excluded under fixed method
|
Credited or debited
|
|
Account requirement
|
Maintained for each partner
|
Used under fixed capital method
|
Both accounts contribute to understanding a partner's overall financial position in the firm.
4. Understanding the Fixed Capital Method
Under the fixed capital method, each partner generally maintains two separate accounts.
The capital account records long-term investment, while the current account records regular adjustments.
Example of Fixed Capital
Consider a partnership with two partners:
Rahul's capital: ₹10,00,000
Amit's capital: ₹8,00,000
During the financial year, Rahul receives ₹1,50,000 as his share of profit and withdraws ₹60,000.
His fixed capital remains ₹10,00,000.
His current account reflects the profit credit and drawings debit.
Assuming no other adjustments, Rahul's current account has a closing credit balance of ₹90,000.
Advantages
The fixed capital method provides clearer separation between long-term investment and periodic adjustments.
It supports transparency in profit distribution and simplifies reviewing partner-related transactions.
This approach is particularly useful when multiple partners have different capital contributions and withdrawal patterns.
5. Understanding the Fluctuating Capital Method
Under the fluctuating capital method, a separate current account is not normally maintained.
Instead, capital contributions, drawings, interest, remuneration and profit allocations are recorded in the partner's capital account.
Consequently, the capital balance changes throughout the accounting period.
Example
Rahul begins the year with capital of ₹10,00,000.
He receives a profit share of ₹1,50,000 and withdraws ₹60,000.
His closing capital becomes:
₹10,00,000 + ₹1,50,000 − ₹60,000 = ₹10,90,000
Advantages
The fluctuating capital method requires fewer ledgers and may be convenient for smaller partnerships.
However, it combines long-term investment and routine adjustments, making it less convenient when partners want to distinguish the two.
6. An Emotional Story: Two Brothers, One Business and a Financial Misunderstanding
For nearly twenty years, brothers Rajesh and Suresh operated a family-owned hardware distribution business in Delhi.
Their father had established the business in a small rented shop, hoping that his sons would eventually expand it together.
Rajesh managed purchases and supplier relationships, while Suresh handled customers and daily operations.
As the company grew, both brothers contributed additional funds whenever the business required working capital.
They also withdrew money for family expenses.
Unfortunately, their accountant recorded several capital contributions, withdrawals and profit adjustments without clearly separating the transactions.
One year, the brothers disagreed about how much each had invested.
Rajesh believed he had contributed more capital, while Suresh felt that his additional responsibilities had not been properly recognized.
The disagreement became personal.
Family dinners grew uncomfortable, and their father worried that the business he had built would divide his sons.
Eventually, the brothers decided to review their partnership accounts with professional assistance.
They examined their partnership deed, bank transactions, capital contributions and previous financial statements.
The accountant recommended maintaining separate capital and current accounts under an agreed fixed capital method.
Using TallyPrime, the firm reorganized its partner ledgers and recorded the relevant adjustments.
The brothers could now distinguish permanent investments from personal withdrawals and profit allocations.
The process did not eliminate every disagreement, but it gave them a common set of financial records.
One evening, their father visited the shop and saw both sons discussing expansion plans again.
For him, that moment mattered more than the year's profit.
The family had rediscovered the importance of transparency.
This fictional story illustrates how organized partnership accounting can help reduce financial misunderstandings and protect business relationships.
7. How to Calculate a Partner's Current Account Balance
A partner's current account balance is determined by combining credits and debits recorded during the accounting period.
Credits may include opening credit balances, profit shares, interest on capital and remuneration.
Debits may include drawings, interest on drawings and loss allocations.
Practical Example
Suppose Rahul's current account contains the following transactions:
|
Particulars
|
Amount
|
|---|
|
Opening credit balance
|
₹40,000
|
|
Share of profit
|
₹1,20,000
|
|
Interest on capital
|
₹60,000
|
|
Partner remuneration
|
₹90,000
|
|
Drawings
|
₹75,000
|
|
Interest on drawings
|
₹5,000
|
Total credits: ₹3,10,000
Total debits: ₹80,000
Closing current account balance: ₹2,30,000 credit
This balance represents the net amount standing to Rahul's credit in his current account.
His fixed capital remains separately recorded.
8. Journal Entries for Capital and Current Accounts
Correct journal entries are essential for maintaining accurate partnership records.
Initial Capital Contribution
Bank A/c Dr. ₹5,00,000
To Partner's Capital A/c ₹5,00,000
Interest on Capital
Profit & Loss Appropriation A/c Dr. ₹30,000
To Partner's Current A/c ₹30,000
Partner's Share of Profit
Profit & Loss Appropriation A/c Dr. ₹1,00,000
To Partner's Current A/c ₹1,00,000
Drawings
Partner's Current A/c Dr. ₹20,000
To Bank A/c ₹20,000
Interest on Drawings
Partner's Current A/c Dr. ₹2,000
To Profit & Loss Appropriation A/c ₹2,000
These entries illustrate the fixed capital method. Actual accounting treatment should follow the partnership deed and applicable accounting requirements.
9. How TallyPrime Helps Manage Partners' Capital and Current Accounts
TallyPrime provides ledger management, voucher recording and financial reporting capabilities that help partnership firms maintain partner-related accounts.
Separate Partner Ledgers
Businesses can create separate capital and current ledgers for each partner.
This helps distinguish capital contributions from periodic adjustments.
Journal Voucher Management
Journal vouchers can be used to record profit allocations, interest adjustments and other partner-related entries.
Drawings Tracking
Personal withdrawals can be recorded against the appropriate partner ledger.
Financial Reporting
TallyPrime provides ledger statements, Trial Balances and Balance Sheets for reviewing partner balances.
Transaction Verification
Accounting teams can examine voucher details and supporting records to investigate discrepancies.
Multi-User Operations
Suitable licensing and access permissions can support accounting work performed by multiple authorized employees.
TallyPrime does not automatically determine partnership deed provisions or legally appropriate profit-sharing arrangements. These must be configured and recorded correctly.
10. Step-by-Step Guide to Managing Partner Accounts in TallyPrime
Businesses can organize partnership accounting by following a structured ledger setup.
Step 1: Create separate partner ledgers. Open TallyPrime and select the relevant company. Navigate to ledger creation through the accounting masters menu or Create option.
Step 2: Create capital accounts. Create separate ledgers such as Rahul Capital Account and Amit Capital Account under the Capital Account group.
Step 3: Create current accounts. Under the fixed capital method, create separate Rahul Current Account and Amit Current Account ledgers. Use an appropriate grouping structure consistent with the firm's financial reporting requirements.
Step 4: Record capital contributions. Use receipt or journal vouchers, as appropriate, to record cash, bank or other capital contributions.
Step 5: Record periodic adjustments. Enter drawings, interest on capital, remuneration and profit allocations through suitable vouchers.
Step 6: Review financial reports. Examine individual ledger statements, the Trial Balance and Balance Sheet to verify balances.
Step 7: Reconcile annually. Confirm that the closing balances agree with the partnership deed, profit appropriation records and supporting documents.
The exact menu options may differ depending on the TallyPrime release.
11. Case Study One: A Wholesale Partnership Improves Financial Transparency
Illustrative case study based on common partnership accounting challenges.
Business Background
A wholesale electrical goods business in Sadar Bazar, Delhi, operated with three partners.
Each partner had invested a different amount, while drawings and profit distributions varied throughout the year.
Challenges
The business maintained a single running capital account for each partner.
Although the records contained transaction details, the partners found it difficult to distinguish original capital contributions from routine adjustments.
This created confusion during annual profit distribution.
Solution
After reviewing the partnership deed, the firm adopted the fixed capital method.
Separate capital and current ledgers were configured in TallyPrime.
Permanent contributions remained in capital accounts, while drawings, interest and profit shares were recorded in current accounts.
Business Outcome
The partners gained clearer visibility into their investments and running balances.
Annual profit allocation became easier to verify, and financial discussions were supported by organized accounting records.
The company also established a more consistent year-end reconciliation process.
Key lesson: Separating fixed capital from periodic adjustments can improve transparency and reduce partnership accounting disputes.
12. Case Study Two: A Manufacturing Partnership Simplifies Year-End Accounting
Illustrative case study demonstrating structured partner ledger management.
Business Background
A manufacturing partnership in Faridabad produced industrial components for customers across North India.
The firm had four partners with different capital contributions and management responsibilities.
Challenges
The accounting team struggled to prepare accurate partner-wise statements because remuneration, drawings and interest adjustments were maintained in separate spreadsheets.
Year-end reconciliation required considerable manual effort.
Solution
The company introduced a structured TallyPrime ledger system.
Each partner received separate capital and current accounts.
The accountant recorded adjustments using journal vouchers and reviewed balances through ledger statements.
Business Outcome
The company reduced its dependence on disconnected spreadsheets.
Partner-related transactions became easier to trace, and management gained clearer financial information.
Annual accounting reviews became more organized.
Key lesson: Consistent ledger structures and regular reconciliation can improve partnership financial management.
13. Common Mistakes in Capital and Current Account Management
Partnership firms should avoid mixing permanent capital contributions with routine drawings without understanding the chosen accounting method.
Another common mistake is allocating profits without following the partnership deed.
Businesses may also overlook interest adjustments or record personal expenses as operating expenses.
Incorrect ledger grouping can create misleading financial statements.
To reduce these risks, firms should maintain clear documentation, review partner transactions regularly and reconcile balances at year-end.
14. Importance of Capital and Current Accounts for Financial Planning
Accurate partner accounts help businesses understand the financial interests of individual partners.
They can also support discussions about additional investment, profit retention and business expansion.
When admitting a new partner or arranging a partner's retirement, organized records help establish the amounts standing to each partner's credit or debit.
However, account balances alone do not determine ownership percentages or settlement entitlements. These depend on the partnership deed and applicable agreements.
TallyPrime provides financial reports that can support such reviews.
15. How TallyPrime on Cloud Supports Partnership Accounting
Partnership businesses operating from multiple locations may require shared access to financial records.
With suitable cloud hosting and licensing, authorized partners and accounting employees can access their TallyPrime environment remotely.
For example, one partner may review financial reports while another manages business operations from a different city.
Cloud hosting can support collaboration, centralized accounting and backup planning.
Businesses should verify user permissions, security arrangements and data recovery procedures before adopting a hosting service.
Conclusion
Understanding the difference between a capital account and a current account is essential for accurate partnership accounting.
The capital account records long-term investment, while the current account records routine partner-related adjustments under the fixed capital method.
The fluctuating capital method combines these transactions into a single capital account.
Both approaches can be appropriate depending on the partnership agreement and business requirements.
TallyPrime helps firms maintain separate ledgers, record journal entries and review financial reports.
With consistent accounting practices, partnership businesses can improve transparency, reduce misunderstandings and make better financial decisions.
Powered by Binarysoft Technologies
Authorized Tally Partner
Location: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact Us: +91 7428779101, 9205471661
Email: tally@binarysoft.com
Business Hours: 10:00 AM – 6:00 PM, Monday to Friday
Frequently Asked Questions
How can Binarysoft Technologies help partnership businesses?
Binarysoft Technologies can assist with TallyPrime implementation, partner ledger configuration, accounting setup, financial reporting, employee training and suitable cloud-hosting requirements.
How are partners' profits recorded in TallyPrime?
Profit allocations can be recorded through suitable journal vouchers after determining the appropriate amounts according to the partnership deed.
Can TallyPrime maintain separate partner accounts?
Yes. TallyPrime allows businesses to create separate capital and current ledgers and record relevant accounting transactions.
Does interest on capital affect the current account?
Under the fixed capital method, interest on capital is normally credited to the partner's current account according to the partnership agreement.
CA. Aaryan Kanodia focuses on GST reporting, bookkeeping systems, and financial process improvement. He works with businesses to simplify routine accounting activities and maintain records suitable for compliance and internal review.