Call CA Tally HelpDesk
+91 9205471661,
7428779101
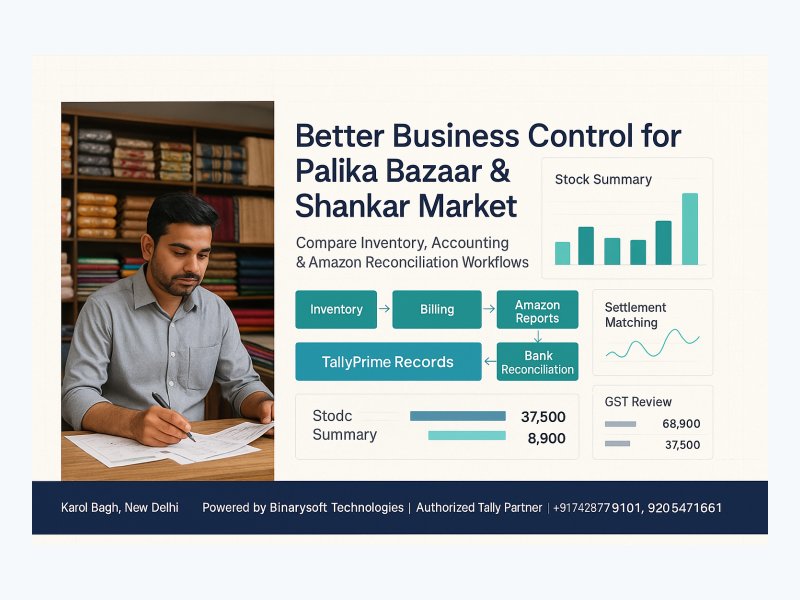
In 2026, the biggest change for many Palika Bazaar and Shankar Market sellers is not a single new rule; it is the speed and visibility of every transaction. UPI, card payments, Amazon orders, courier returns, marketplace fees and supplier credits now meet inside the same business day. Buyers compare prices on their phones, suppliers expect quicker payment, and accountants ask for cleaner monthly data. When records are late, a shop can look profitable while cash is actually blocked in returns, excess stock or unpaid marketplace deductions. No seller needs more confusion at closing time. The practical win is simple: organize inventory, sales, returns, settlements, fees, TCS, TDS and GST data so the owner can see what sold, what came back, what is owed and what must be discussed with the accountant before filing or purchase decisions.
Suggested URL slug: better-business-control-palika-bazaar-shankar-market-inventory-accounting-software
Why business control matters for Palika Bazaar and Shankar Market sellers
Palika Bazaar and Shankar Market are not ordinary retail locations. A seller may handle walk-in bargaining, repeat wholesale buyers, tourist purchases, online enquiries, repairs, exchanges, seasonal stock, cash collections, UPI receipts, card settlements and marketplace sales in the same week. In such an environment, business control does not mean making the shop complicated. It means knowing the basics before they become expensive problems.
A shopkeeper needs to know how much stock is available, what price was paid, which items are moving, which items are lying dead, which supplier payments are due, which customer balances are pending, how much cash is in hand, how much is expected from marketplaces, and what deductions have been made before money reaches the bank. If these answers are scattered across notebooks, WhatsApp messages, marketplace dashboards and bank statements, the business becomes dependent on memory.
Memory works when the shop is small, the owner is always present, and the number of products is limited. It starts failing when one person handles procurement, another person manages the counter, a family member checks online orders, and the accountant receives incomplete records after the month ends. That is where a structured inventory and accounting system becomes useful.
For sellers in Palika Bazaar and Shankar Market, the right software should not only print bills. It should help connect sales, stock, purchase cost, marketplace deductions, tax records and bank receipts. It should also support a workflow that staff can actually follow during busy market hours. A system that looks impressive but is not used daily will not improve control.
The local reality: high footfall, price pressure and mixed sales channels
Local market sellers operate under constant commercial pressure. A customer may ask for the same product at three shops within ten minutes. A supplier may change prices without much notice. Fast-moving stock may run out before the weekend. Slow-moving stock may silently occupy valuable space. A return may come back without the original bill. An online order may be delivered after the shop has already sold the same item over the counter.
These pressures create three common business risks. The first is stock confusion. The owner believes there are ten pieces available, but two are damaged, three are booked for online dispatch, and one has already been exchanged. The second is margin confusion. The bank received money, but the actual margin is lower after discount, commission, delivery charge, packaging, return loss and marketplace fee. The third is compliance confusion. Sales, returns, GST data, TCS, TDS and purchase records do not match easily because entries are not organized at the source.
Good software cannot remove market competition. It cannot guarantee profit. It cannot replace business judgement. But it can make the business visible. When records are clean, the owner can negotiate better with suppliers, identify slow stock earlier, prepare clearer data for the accountant and reduce the time wasted in month-end searching.
An illustrative story from Gaffar Market: how small gaps become heavy
Consider an illustrative story of Ramesh, a fictional mobile accessories seller in Gaffar Market near Karol Bagh. His shop is not large, but it is always busy. He sells chargers, covers, earbuds, cables and small gadgets. His father started the business with handwritten registers. Ramesh added UPI payments, card swipes and Amazon orders. His younger cousin helps with packing online orders in the afternoon.
For a long time, Ramesh believed he was in control because sales were strong. The shop looked active. The bank account showed regular credits. Suppliers still gave him material on short credit. But pressure built slowly. A few fast-moving products were repeatedly out of stock. Some expensive covers were purchased in bulk and did not move. Amazon settlements came after deductions that nobody fully checked. Returned items were kept in a side carton and were not entered back properly. The accountant asked for monthly summaries, but Ramesh sent screenshots, bank statements and a few handwritten notes.
One evening, after a difficult discussion with a supplier, Ramesh sat in the shop after closing. The shutter was half down, the market noise was fading, and he realized he did not know his true position. He had stock, but not the right stock. He had sales, but not clear margins. He had bank receipts, but did not know which orders they belonged to. The emotional burden was not only financial. It was the stress of running a business that looked successful from outside but felt uncertain from inside.
This story is not presented as a real customer case. It is a realistic illustration of what many growing sellers experience. The solution was not to buy the most expensive software or to hire a large team. The solution was to design a simple daily discipline: product masters, purchase entries, counter billing, marketplace settlement tracking, returns recording, fee ledgers, bank reconciliation and monthly review with the accountant. Once the records became clearer, decisions became less emotional. Ramesh could see what to reorder, what to stop buying, what to discount, what to repair, and what to ask his accountant before filing.
Inventory software versus accounting software: what is the difference?
Many sellers use the words inventory software and accounting software as if they mean the same thing. They are related, but they solve different problems. Inventory software focuses on stock: item names, quantities, batches, serial numbers, godowns, reorder levels, purchases, sales, transfers and closing stock. Accounting software focuses on money: sales ledgers, purchase ledgers, bank, cash, expenses, duties and taxes, receivables, payables, profit and loss, balance sheet and reports for the accountant.
A pure inventory app may help the counter team know whether an item is available. But if it does not connect properly with accounting, the owner may still struggle to know supplier balances, taxes, marketplace deductions and bank reconciliation. A pure accounting setup may produce financial reports, but if stock items are not maintained well, the owner may not know product-level movement and closing stock accuracy.
The best choice for many market sellers is an integrated approach. That may be a business accounting system with inventory features, a retail point-of-sale system connected to accounting, or TallyPrime configured with inventory masters, accounting ledgers and a disciplined voucher workflow. The exact setup depends on shop size, number of items, billing speed, staff skill and online sales volume.
Software options commonly considered by market sellers
Billing-only applications
Billing apps are attractive because they are quick to start and easy for counter staff. They may generate invoices, manage basic customer details and show simple reports. For a small shop with limited products, this can be useful. The limitation appears when the owner needs deeper accounting, GST reports, supplier reconciliation, marketplace fee accounting and closing stock valuation. If data has to be re-entered into another accounting system, errors increase.
Spreadsheets and manual registers
Spreadsheets are flexible and familiar. Many sellers use Excel or Google Sheets to track orders, purchases and payments. The advantage is low cost and quick customization. The disadvantage is weak control. Formulas can be changed accidentally, duplicate entries are common, and it is difficult to maintain a reliable audit trail. Spreadsheets are useful for analysis and working papers, but they should not become the only accounting backbone for a growing business.
Standalone inventory systems
Standalone inventory tools are strong when the business has many SKUs, barcode needs, multiple counters or warehouse movement. They may be useful for shops with high item variety. The concern is integration. If sales, purchases and stock do not flow cleanly into accounting, the owner may get two versions of the truth: stock in one system and money in another.
Full accounting and inventory platforms
Accounting systems with inventory capability help connect stock movement with financial entries. TallyPrime is widely used by Indian businesses for accounting and inventory workflows. Before finalizing any setup, sellers should verify current TallyPrime features, licensing, GST-related options, import methods, multi-user access and cloud or remote access arrangements from current product documentation and their authorized partner.
Cloud-hosted accounting access
Some sellers want TallyPrime access from the shop, home, warehouse or accountant office. A cloud-hosted environment can help authorized users work on the same business data with better accessibility. However, the seller should verify data security practices, backup policy, user permissions, licensing terms, support responsibility and internet dependency before adopting any cloud arrangement.
E-commerce connectors and data import tools
Marketplace sellers often use connector tools or import templates to bring Amazon and other platform data into accounting. These tools can save time, but they require careful mapping. Sales, returns, shipping fees, commission, tax collected at source, tax deducted at source, reimbursements and bank settlements must go to the correct ledgers. The seller should not assume that every connector is correct by default. The first few months should be reviewed with the accountant.
How to compare inventory and accounting software for Palika Bazaar and Shankar Market
A practical comparison should begin with the seller’s actual workflow, not with a feature list. The owner should write down how goods enter the shop, how they are priced, how they are sold, how returns happen, how staff records payments, how online orders are packed, how supplier credits are managed and how the accountant receives data.
Once the workflow is visible, software can be compared on practical criteria. The right question is not only whether the software has a feature. The right question is whether the shop can use that feature correctly every day.
- Billing speed: Can staff create invoices quickly during peak hours without selecting wrong items?
- Stock accuracy: Does the software support item-wise stock tracking, units, godowns and adjustment entries suitable for the shop?
- Accounting depth: Can it handle purchases, sales, expenses, receivables, payables, bank, cash and taxes in a structured manner?
- Marketplace handling: Can Amazon sales, returns, fees, TCS, TDS and settlements be imported or summarized without confusion?
- GST readiness: Does the workflow help prepare data for GST discussion and filing, subject to current law and accountant review?
- Reconciliation: Can bank receipts be matched with settlement reports rather than treated as direct sales?
- User control: Can the owner restrict who can create, alter or delete entries?
- Reporting: Are reports understandable enough for purchase decisions, ageing review and stock planning?
- Support: Is there a local partner who understands both Tally and the practical pressure of Delhi market businesses?
- Scalability: Can the system support growth to multiple users, additional sales channels or a separate warehouse?
Why TallyPrime remains relevant for local sellers
TallyPrime is familiar to many Indian accountants and business owners. For a seller in Palika Bazaar or Shankar Market, this familiarity matters. A system is useful only when the owner, accountant and support partner can understand the same data. TallyPrime can be configured around ledgers, stock items, groups, vouchers, cost centres, godowns and reports. The exact capabilities and available features should be checked with current TallyPrime documentation and an authorized Tally partner before implementation.
For many sellers, the real benefit is structure. Purchases are not only written in a register; they are entered against suppliers and stock items. Sales are not only counted from the cash drawer; they are recorded with proper ledgers. Expenses are not hidden inside reduced bank credits; they are posted separately. Marketplace settlements are not treated as sales; they are reconciled against sales, returns and deductions. This structure gives the owner better control.
TallyPrime can also support a disciplined accountant-owner relationship. Instead of giving the accountant incomplete data after two months, the seller can maintain records regularly and review exceptions. This does not remove the need for professional advice. It makes professional advice more useful because the accountant sees cleaner data.
Designing a chart of accounts for market sellers
A clean chart of accounts is the foundation of useful accounting. If all marketplace deductions are posted to one vague expense ledger, the owner cannot see what is happening. If online sales and counter sales are mixed without any classification, channel-wise margin becomes unclear. If supplier advances and purchase returns are not tracked properly, payables become unreliable.
The chart of accounts should be designed with the accountant. It should reflect tax requirements, reporting needs and daily usability. The following categories are commonly useful, but every business should confirm the exact setup with its accountant.
- Sales ledgers: Counter sales, Amazon sales, wholesale sales and other channels can be separated if reporting is needed.
- Purchase ledgers: Local purchases, interstate purchases and import-related purchases may need separate treatment depending on the business.
- Tax ledgers: Output GST and input GST ledgers should be set up according to current GST requirements and accountant guidance.
- Marketplace receivable: A separate Amazon receivable ledger helps distinguish platform dues from bank money.
- Marketplace fee ledgers: Commission, closing fee, shipping fee, technology fee, storage fee, advertising fee and other deductions may be tracked separately if material.
- TCS and TDS receivable ledgers: Amounts collected or deducted by the marketplace, where applicable, should be tracked so they are not lost as expenses.
- Returns and claims: Sales returns, damaged returns, reimbursements and claims should be visible.
- Payment ledgers: Bank accounts, cash, UPI clearing and card settlement ledgers may be maintained depending on collection channels.
The aim is not to create hundreds of ledgers that staff cannot use. The aim is to create enough detail for decisions and compliance review. Too little detail hides problems. Too much detail creates posting errors. A balanced structure is best.
Building item masters that staff can actually use
Inventory control begins with item naming. In markets where products look similar, poor naming creates daily confusion. For example, a phone cover may differ by model, color, finish and quality grade. A cable may differ by connector type, length, brand and warranty. A fabric item may differ by material, width, color and design. If the item master says only cover or cable, stock reports are not useful.
A good item naming system should be clear, consistent and short enough for billing speed. The seller can decide a structure such as category, model, variant and color. For example, a mobile accessories seller may use names like Cable Type C 1m Black Standard or Cover iPhone 15 Clear Soft. A fabric seller may use Cotton Print 44in Blue Floral. The structure should match how staff searches for items.
Stock groups and categories can help organize reporting. Fast-moving and slow-moving groups can be reviewed. High-value items may need serial-wise or batch-wise tracking if appropriate and supported by the current software setup. Godowns or locations can be useful when stock is split between shop, basement, warehouse, display counter and online packing area.
The owner should avoid creating duplicate item names for the same product. Duplicate masters are a silent cause of stock mismatch. One staff member may sell from one item name while purchase is entered under another. At month-end, the report shows negative stock in one item and excess stock in another. A periodic master cleanup prevents this.
Stock control examples for Palika Bazaar and Shankar Market
Consider a Palika Bazaar seller dealing in fashion accessories. The shop has fast-moving belts, wallets, bags and sunglasses. Some items are seasonal, some are impulse purchases, and some are ordered in bulk because the supplier offers a discount. Without item-wise stock reports, the owner may keep buying the same designs because they look attractive, not because they sell.
With organized inventory, the seller can review movement by item group. If a specific wallet design sold well during the last month and only a few pieces remain, it can be reordered. If a bag design has not moved for several weeks, the owner can decide whether to discount it, bundle it or stop reordering. This is business control in practical form.
Now consider a Shankar Market fabric or garment-related seller. The business may deal with shades, lengths, rolls or pieces. Staff may cut material, reserve stock for regular buyers, and adjust returns. The inventory method must match the business reality. The unit of measurement, wastage handling and return process should be discussed before software configuration. Otherwise, the system may look correct but fail during daily use.
For electronics, accessories or gadgets, the seller may need warranty tracking, serial numbers or at least purchase batch records. Not every item needs deep tracking. A low-value common cable may be managed by quantity. A higher-value device may need stricter control. The decision should be based on risk, value and staff capacity.
Amazon sales in TallyPrime: the most important principle
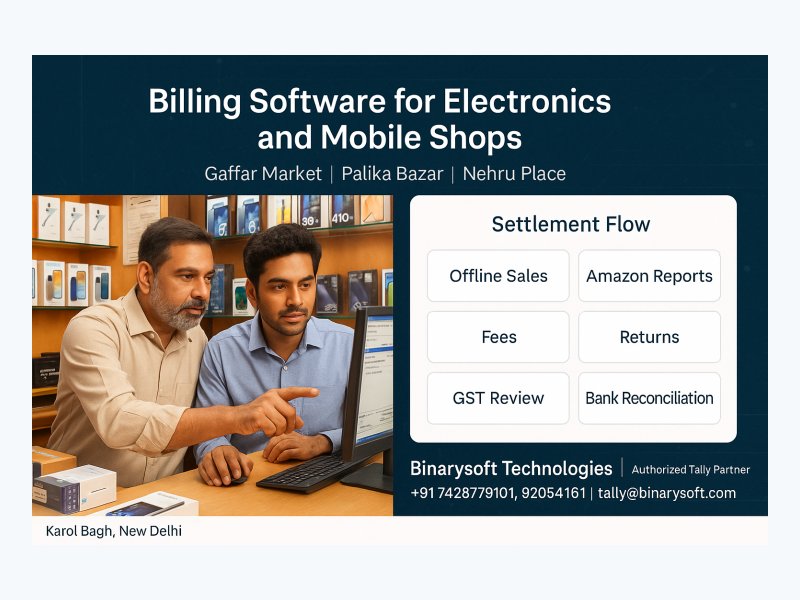
The most important principle for Amazon accounting is this: marketplace reports are not the same as bank receipts. Amazon may collect money from customers, deduct fees, adjust returns, apply TCS or TDS where applicable, and then transfer the net settlement to the seller’s bank account. If the seller records only the bank receipt as sales, the accounts will be incomplete.
The bank receipt is only the net amount received. It does not show the full customer invoice value, marketplace fee, tax components, return deductions, claim adjustments or amounts collected or deducted on behalf of tax authorities. The marketplace settlement report explains why the bank received that amount. The order report explains what was sold. The return report explains what came back. The fee report explains deductions. The tax reports help the accountant review GST, TCS and TDS treatment.
For a seller using TallyPrime, the workflow should separate gross sales, returns, fees, tax ledgers, marketplace receivable and bank receipts. The exact voucher structure, ledger names and import method should be confirmed with the accountant and current TallyPrime documentation. The principle remains constant: do not let net bank credit replace proper sales accounting.
How to organize Amazon data before entering it in TallyPrime
Amazon provides different reports for different purposes. The names, formats and available columns may change, so sellers should check the current seller portal and consult their accountant. Instead of downloading reports randomly, create a monthly folder structure. Each month should contain order reports, settlement reports, return reports, fee reports, tax reports, reimbursement reports and bank statements.
A simple folder naming method can save hours later. For example, create a folder for each financial year, then each month, then separate subfolders for marketplace reports and bank statements. Keep original downloaded files unchanged. If a working spreadsheet is prepared, save it separately so the original report remains available for verification.
Before entering or importing data into TallyPrime, summarize it carefully. The summary should show total sales, sales returns, commission and fees, taxes on fees if applicable, TCS, TDS, reimbursements, claims, net settlement and bank receipt. The accountant should review the mapping. Once the mapping is approved, the same structure can be followed every month.
Suggested Amazon accounting flow
- Step 1: Download order, settlement, return, fee and tax-related reports for the period.
- Step 2: Match settlement period with bank credit dates. Remember that order date, shipment date and settlement date may differ.
- Step 3: Post gross sales to the relevant sales ledger and tax ledgers as advised by the accountant.
- Step 4: Post sales returns separately instead of reducing sales informally.
- Step 5: Post marketplace commission, shipping fees, closing fees, advertising fees or other deductions to suitable expense ledgers.
- Step 6: Track TCS and TDS amounts in separate receivable ledgers where applicable and as shown in marketplace reports.
- Step 7: Transfer the net settlement from Amazon receivable to bank when the bank credit is received.
- Step 8: Reconcile pending balances in Amazon receivable with unsettled orders, returns, claims or timing differences.
Illustrative Amazon settlement example
Assume an illustrative settlement period for an online seller. The marketplace report shows customer order value of 120000 for several orders. During the same period, returns of 15000 are adjusted. Marketplace fees and related charges total 9000 before any tax treatment that the accountant must verify. TCS and TDS entries appear in the report where applicable. A reimbursement of 1000 is also shown for a claim. The bank receives a net amount that is lower than the customer order value.
If the seller records only the net bank receipt as sales, sales will be understated, expenses will be hidden, tax-related receivables may be missed, and returns will not be visible. The owner may think the marketplace is less profitable than it is, or more profitable than it is, depending on what was ignored. The accountant may also struggle to match GST, TCS, TDS and settlement data.
A better approach is to record the gross sale, record returns, record fees, record TCS and TDS receivables where applicable, record reimbursements, and then match the final bank receipt. This shows the full picture. The owner can then ask useful questions: Which products are returned frequently? Are marketplace fees too high for low-margin items? Are reimbursements being tracked? Are TCS and TDS amounts being claimed or adjusted properly as advised by the accountant?
Common reconciliation mistakes with Amazon and other marketplaces
Marketplace reconciliation errors are common because the bank statement looks simple while the settlement report is detailed. Sellers should train themselves and their staff to avoid the following mistakes.
- Mistake 1: Treating bank receipt as sales. The bank receives net settlement after deductions. Sales should be based on transaction data, not only the bank credit.
- Mistake 2: Ignoring returns. Returned items affect sales, stock, GST review, customer claims and product profitability.
- Mistake 3: Posting all deductions to one expense ledger. Commission, shipping, advertising, storage, penalties and other charges may need separate review if material.
- Mistake 4: Missing TCS and TDS amounts. These amounts may be available for adjustment or claim subject to current law and accountant review. They should not be lost inside expenses.
- Mistake 5: Matching by bank date only. Order date, invoice date, shipment date, return date and settlement date can be different.
- Mistake 6: Duplicating sales entries. If invoices are entered manually and then imported again, sales may be overstated.
- Mistake 7: Not checking pending marketplace receivable. A balance may be genuine due to unsettled orders, but it may also indicate missing returns or wrong posting.
- Mistake 8: Ignoring damaged or unsellable returns. If a returned product cannot be resold, stock quantity and stock value need careful treatment.
- Mistake 9: Not preserving reports. If reports are downloaded late or mixed across periods, reconciliation becomes harder.
GST, TCS and TDS: what sellers should verify
Tax treatment must be handled carefully. GST rates, input credit eligibility, return filing requirements, e-invoicing applicability, e-way bill rules, TCS treatment, TDS treatment and thresholds can change or depend on the nature and size of the business. This article does not provide tax advice and does not assume any current rate or threshold. Sellers should confirm all tax positions with their accountant and current official guidance.
From a record-keeping perspective, the seller should ensure that the accounting system captures the data needed for review. For GST, this may include taxable value, tax amount, place of supply, customer type, purchase input tax details and returns. For marketplace TCS and TDS, this may include amounts shown in platform reports, certificates or statements available through the relevant portals, and reconciliation with books.
The accountant can file correctly only when the underlying data is organized. If marketplace sales are entered as one monthly bank receipt, the accountant may not have enough detail. If returns are recorded in a separate notebook but not in books, reports will not match. If purchase invoices are missing, input tax review becomes difficult. Clean accounting does not guarantee a specific tax outcome, but it gives the accountant a reliable base.
Daily, weekly and monthly workflow for better control
The best software setup fails if there is no routine. Market sellers should create a rhythm that fits daily pressure. The routine should be simple enough to continue during festival season, weekends and staff absence.
Daily routine
- Enter or sync all counter sales before closing or by the next morning.
- Record purchases and goods received as soon as material enters the shop or warehouse.
- Separate cash, UPI, card and online payments clearly.
- Record sales returns and exchanges with reason, condition and stock impact.
- Check negative stock items and correct wrong item selection quickly.
- Keep purchase invoices, courier slips and marketplace dispatch records in one place.
Weekly routine
- Review fast-moving and slow-moving items.
- Check pending supplier payments and customer balances.
- Download marketplace reports for recent settlements.
- Match bank credits with UPI, card and marketplace receipts.
- Review damaged, returned or unsellable stock.
- Discuss unusual deductions or missing settlements with the responsible person.
Monthly routine
- Close purchase and sales entries for the month.
- Reconcile bank accounts, cash, UPI clearing and card settlements.
- Reconcile Amazon receivable and other marketplace balances.
- Share organized reports with the accountant for GST, TCS, TDS and financial review.
- Review stock valuation and slow stock before making new purchases.
- Back up data and confirm that important reports are stored safely.
Checklist before choosing software
Before buying or changing software, owners should ask practical questions. The answers will prevent wrong selection and reduce implementation delays.
- How many SKUs do we sell actively?
- Do we need barcode billing or is item search enough?
- Do we sell through Amazon, other marketplaces, WhatsApp, counter and wholesale channels?
- How many users need access?
- Who will enter purchases and who will verify them?
- Do we need godown-wise stock for shop, storage and online packing area?
- Do we handle serial numbers, batches, warranty or expiry?
- How often do returns happen and how are they approved?
- Do we need separate profitability reports for counter and marketplace sales?
- Can the accountant work with the software data directly?
- How will GST, TCS and TDS data be reviewed?
- What is the backup plan if the internet fails or the main user is absent?
- Who will train staff and clean old data?
- What reports will the owner review every week?
Comparison by business type
Small counter-only seller
A small seller with limited SKUs and mostly counter sales may need simple billing, purchase entry, cash and bank accounting, basic stock and GST-ready records as applicable. The priority is ease of use. Overcomplicated setup may reduce discipline. TallyPrime with carefully created item masters and ledgers may be enough if staff can follow the process.
Retail plus wholesale seller
A seller who handles both walk-in customers and wholesale buyers needs better receivable control. Customer ledgers, credit limits, payment follow-up and bill-wise outstanding reports become important. Stock must also distinguish between retail units and bulk quantities if both are used. Software should help the owner see which buyers pay on time and which buyers block cash.
Marketplace-focused seller
A seller with significant Amazon sales needs strong settlement reconciliation. The key is not only order import. The key is correct accounting for returns, fees, TCS, TDS, reimbursements and bank receipts. This seller should invest time in ledger mapping and monthly review. A connector or import workflow may be useful, but it must be tested.
Multi-location seller
A seller with shop, warehouse and home-office operations needs location-wise stock and controlled access. Godown-wise inventory, user permissions, backups and cloud access become important. The owner should decide who can create masters, who can enter sales, who can alter past entries and who can view financial reports.
High-value product seller
For electronics, gadgets, branded accessories or other high-value items, stock loss and warranty claims can be expensive. Serial tracking, purchase reference, supplier warranty terms and return condition should be considered. The exact software feature should be verified before implementation.
Why bank reconciliation is not optional
Many owners check the bank account daily but do not reconcile it. Checking means seeing whether money has arrived. Reconciliation means matching the money to the right transaction. The difference is important. A bank credit may be from Amazon settlement, card settlement, UPI batch, customer transfer, supplier refund or owner capital. A bank debit may be supplier payment, fee, EMI, tax payment, rent, salary or bank charge.
Without reconciliation, the owner may believe that all expected money has arrived when some amount is still pending. Or the owner may chase a customer even though payment came under a different reference. Marketplace settlements make this more complex because one bank credit can represent hundreds of orders and deductions.
In TallyPrime or any accounting system, bank reconciliation should be done regularly. The bank date, voucher date, reference number and narration should be meaningful. If staff enters vague narrations like payment received or Amazon, the accountant must spend extra time later. Better narration saves time and reduces mistakes.
Cash, UPI and card collections: keeping channels separate
Delhi market sellers often receive money through multiple channels in the same hour. Cash goes into the drawer. UPI may go to the owner’s current account, a QR-linked account or sometimes a staff-managed device. Card payments may settle after deduction or delay. If these channels are not separated in books, daily collection reports become unreliable.
A simple approach is to maintain separate ledgers or clearing accounts for major payment modes, as advised by the accountant. Daily counter sales can be recorded with payment mode. UPI collections can be matched with bank credits. Card settlements can be matched with the card provider statement. Cash can be physically counted and compared with cash book balance.
This discipline helps detect errors early. If UPI sales are recorded but bank credits do not match, the issue can be checked quickly. If card settlements are lower due to charges, those charges can be posted properly. If cash is short, the owner can investigate before the trail goes cold.
Purchase control: the hidden source of profit improvement
Many shop owners focus on sales but lose money in purchases. Buying too much, buying the wrong variants, missing supplier schemes, not recording purchase returns, and failing to claim damaged goods can reduce profit. Inventory software helps only when purchases are entered correctly.
Every purchase should capture supplier name, invoice number, date, item, quantity, rate, tax details where applicable and payment terms. If goods are received before the invoice, the business should have a method for goods receipt and later invoice matching. If the supplier gives credit notes, those should be recorded. If stock is returned to the supplier, the accounting and inventory effect should both be clear.
For Palika Bazaar sellers dealing in seasonal products, purchase control is critical. A design that sells during one season may not move later. For Shankar Market sellers, variations in fabric, shade, size or quality may affect reorder decisions. Purchase reports should help the owner see not only total buying but item-wise buying quality.
Returns and exchanges: record them before they distort profit
Returns are part of modern retail. Customers expect replacement, exchange or refund. Marketplaces also generate returns based on customer behaviour, delivery issues or product mismatch. If returns are not recorded correctly, sales and stock reports become misleading.
A return should answer four questions. What was returned? Why was it returned? Is it sellable? What financial adjustment is required? A sellable return can go back into stock after inspection. A damaged return may need a separate damaged stock location or write-off process. A customer exchange should not be handled casually because it affects both sales and stock.
For Amazon returns, the seller should compare return reports with physical stock received. Sometimes the marketplace report may show a return, but the item condition or timing needs review. Reimbursements, claims and deductions should be tracked separately. This is where accounting and stock teams must communicate.
Reports owners should review every week
Software becomes valuable when the owner reads the right reports. Too many reports create fatigue. Too few reports hide problems. A weekly review can be completed in a short time if reports are well configured.
- Stock summary: Shows available quantity and value by item group.
- Fast-moving items: Helps decide reorder priorities.
- Slow-moving items: Helps plan discounting, bundling or stopping future purchases.
- Negative stock report: Indicates wrong entry, missing purchase or incorrect item selection.
- Supplier outstanding: Helps plan cash and avoid strained relationships.
- Customer outstanding: Helps follow up credit sales.
- Bank reconciliation report: Shows unmatched receipts and payments.
- Marketplace receivable: Shows whether Amazon or other platform balances are pending or mismatched.
- Expense summary: Helps detect rising fees, rent, salaries, courier charges or advertising costs.
Data migration: moving from registers or old software
Moving to a better system does not mean dumping all old data into the new software. Migration should be planned. The owner should decide a cut-off date, verify opening balances, clean item masters, confirm supplier and customer balances, and count stock physically. Opening stock should be realistic, not guessed.
Old data may contain duplicate customers, inactive suppliers, wrong item names and outdated rates. Importing everything without cleaning creates future confusion. It is often better to migrate essential masters and verified opening balances, while keeping old records available for reference.
Physical stock verification is especially important. If the system starts with wrong quantity, staff will lose trust quickly. The first month after migration should be treated as a stabilization period. Negative stock, wrong item selection, duplicate entries and missing purchases should be corrected regularly.
Training staff for daily discipline
Software success depends on people. A shop may buy the right system but fail because staff are not trained. Training should be role-based. Counter staff need to know billing, item search, payment mode and return entry. Purchase staff need to know goods receipt, supplier invoice and stock verification. The owner needs reports and approval controls. The accountant needs ledger mapping and period-end review.
Training should include practical examples from the shop’s own products. Staff learn better when they see familiar items. The owner should also create simple rules. For example, no item should be sold under miscellaneous if the item exists. No purchase should be entered without supplier invoice details. No return should be accepted into saleable stock without inspection. No marketplace settlement should be posted directly as sales without report review.
Discipline should be firm but realistic. During peak hours, staff may make mistakes. The system should include daily correction time. A ten-minute closing review can prevent a long month-end problem.
Cloud access and Tally@Cloud considerations
Cloud access can be useful for sellers who want to work beyond one desktop. The owner may want to view reports from home. The accountant may need access without visiting the shop. A second location may need to enter data. Tally@Cloud can support this style of working when implemented properly, subject to licensing, infrastructure and security considerations.
Before moving to cloud access, sellers should ask practical questions. Who will have user access? How are passwords managed? Is there a backup policy? What happens if internet connectivity fails? How is data protected? Who provides support? How are software updates handled? Are Tally licensing and user access terms correctly followed? These questions should be answered before the system goes live.
The purpose of cloud access is not to make the business fashionable. The purpose is to make data available to authorized people at the right time. If the owner, staff and accountant can work from the same updated books, decisions become faster and records become cleaner.
How better records improve supplier negotiation
Suppliers respond better when the buyer knows the numbers. If the owner can show purchase volume, return frequency, damaged goods, payment history and fast-moving variants, negotiation becomes more factual. Instead of saying the rate is high, the seller can say which item gives weak margin after marketplace fee and return loss. Instead of buying a mixed lot blindly, the seller can choose variants that actually move.
Good records also protect relationships. When supplier balances are clear, payment disputes reduce. If a supplier credit note is pending, it can be followed up with evidence. If a purchase return was sent, it can be matched with the supplier account. This creates confidence on both sides.
How better records improve pricing decisions
Pricing in markets like Palika Bazaar and Shankar Market is often flexible. Customers bargain, competitors adjust rates and online prices influence expectations. But pricing should still be informed by cost. If the seller does not know purchase cost, marketplace fee, packaging cost, return risk and tax impact, discounting can destroy margin.
Software reports help identify minimum viable price. For counter sales, the owner can consider purchase cost, expected discount and overhead. For Amazon sales, the owner must also consider commission, fulfillment or shipping charges, advertising, returns, TCS, TDS and settlement timing where applicable. The same product may need different pricing by channel.
This does not mean software will set the perfect price. It means the owner can price with awareness. A strategic discount on slow stock may be useful. An accidental discount on already low-margin online items can be harmful. Clean records reveal the difference.
Warning signs that your current system is failing
A seller does not need to wait for a major problem before improving software. There are early warning signs. If any of these are common, the business should review its accounting and inventory setup.
- The owner cannot tell the value of closing stock with confidence.
- Marketplace bank receipts are posted as sales without settlement reconciliation.
- Returns are kept physically but not entered into the system.
- Supplier balances often differ from supplier statements.
- The accountant repeatedly asks for missing purchase invoices or sales summaries.
- Stock reports show negative quantities.
- Staff create duplicate item names because they cannot find existing items.
- Fast-moving items go out of stock while slow items keep increasing.
- TCS or TDS amounts from marketplace reports are not tracked separately.
- Bank reconciliation is delayed for several months.
- The owner depends on screenshots instead of reports.
A practical implementation plan
Implementation should be done in phases. Trying to fix everything in one week can overwhelm staff. A realistic plan improves adoption.
Phase 1: Business mapping
Document sales channels, product categories, payment methods, purchase process, returns process, marketplace reports and accountant requirements. This phase prevents wrong configuration.
Phase 2: Master design
Create item groups, stock items, units, supplier ledgers, customer ledgers, tax ledgers, payment ledgers and marketplace ledgers. Remove duplicates and use naming rules.
Phase 3: Opening balances
Verify opening stock, cash, bank, supplier balances, customer balances and marketplace receivables. Take accountant approval before finalizing.
Phase 4: Daily transaction training
Train staff on billing, purchases, payment modes, returns and corrections. Use real shop examples.
Phase 5: Marketplace reconciliation
Download reports, map ledgers, post sample settlements and reconcile with bank. Review with accountant before repeating monthly.
Phase 6: Monthly review
Check GST-related reports, TCS, TDS, bank reconciliation, stock summary, supplier outstanding and marketplace receivable. Improve the process based on errors found.
Useful checklist for Amazon data in TallyPrime
- Keep marketplace reports separate from bank statements.
- Do not record net bank receipt as total sales.
- Create or confirm ledgers for Amazon receivable, sales, returns, fees, TCS, TDS, reimbursements and bank.
- Verify current GST, TCS and TDS treatment with the accountant.
- Match settlement period, bank date and report totals.
- Post returns separately and update stock condition.
- Track reimbursements and claims instead of ignoring small amounts.
- Review pending marketplace receivable every month.
- Preserve original reports for audit and future checking.
- Test any import or connector mapping before using it at scale.
Conclusion
Better business control for Palika Bazaar and Shankar Market sellers does not come from software alone. It comes from software plus discipline. The owner needs clear item masters, timely purchase entries, proper billing, return control, bank reconciliation, marketplace settlement mapping and regular accountant review. When Amazon sales, returns, fees, TCS, TDS and GST data are organized correctly, the business becomes easier to understand. Decisions about purchasing, pricing, discounting, supplier payment and tax discussion become more practical.
The right inventory and accounting software should match the seller’s real workflow. A billing-only tool may suit a very small shop. A full accounting and inventory setup may be better for sellers with stock complexity, credit sales and marketplace orders. TallyPrime, configured carefully and supported properly, can be a strong option for many Indian market businesses. Sellers should verify current features, tax treatment and licensing details before implementation.
For local guidance, setup, migration, TallyPrime support and Tally@Cloud access, contact Binarysoft Technologies. Powered by Binarysoft Technologies, Authorized Tally Partner, 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi - 110005, INDIA. Call +91 7428779101, 9205471661 or email tally@binarysoft.com. Contact hours: 10:00 AM - 6:00 PM, Mon-Fri.
FAQ
Which is better for a Palika Bazaar seller: inventory software or accounting software?
The best choice is usually an integrated setup that handles both stock and accounts. Inventory software helps track quantities, locations and product movement. Accounting software helps manage sales, purchases, payments, taxes, receivables and payables. A seller with only a few items may start simple, but a growing shop should connect inventory with accounting so the owner can see both stock and money accurately.
Can TallyPrime be used for Amazon sales accounting?
Yes, TallyPrime can be configured to record Amazon sales, returns, fees, marketplace receivables, TCS, TDS and bank settlements, subject to correct ledger mapping and current product capabilities. Sellers should verify the exact import method, feature availability and GST treatment with current TallyPrime documentation, an authorized partner and their accountant.
Why should Amazon bank receipts not be treated as sales?
Amazon bank receipts are usually net settlements after deductions, returns and adjustments. The actual customer sales value, fees, TCS, TDS, refunds and reimbursements may be visible only in marketplace reports. If a seller records only the bank receipt as sales, revenue, expenses, tax-related receivables and returns may be misstated.
How often should marketplace reconciliation be done?
Marketplace reconciliation should ideally be reviewed at least monthly, and more often if online order volume is high. Regular reconciliation helps identify missing settlements, high returns, incorrect fee posting, pending reimbursements and unmatched bank receipts before they become difficult to trace.
What should sellers confirm with their accountant before setting up ledgers?
Sellers should confirm GST treatment, applicable tax ledgers, TCS and TDS handling, sales return treatment, input tax review, filing requirements and any threshold or compliance rule relevant to their business. Tax rates and rules should be verified from current official guidance and professional advice rather than assumed.
Is Tally@Cloud useful for market sellers?
Tally@Cloud can be useful when owners, staff and accountants need authorized access from different locations. It may help with timely data entry and review. Before adoption, sellers should verify licensing, user permissions, backup policy, data security, support responsibility and internet dependency.
What is the biggest mistake in inventory management for local market shops?
The biggest mistake is often poor item master discipline. Duplicate item names, vague product descriptions and missing purchase entries lead to wrong stock reports. Once staff stop trusting stock reports, the software loses value. Clear naming, regular entry and periodic stock checking are essential.
How can a seller start improving records without disrupting daily sales?
Start in phases. Clean item masters, enter current purchases and sales properly, separate payment modes, record returns daily, and reconcile bank and marketplace receipts weekly or monthly. Do not try to perfect everything on day one. A practical routine followed consistently is better than a complex system that staff avoid.
Frequently Asked Questions
Which is better for a Palika Bazaar seller: inventory software or accounting software?
The best choice is usually an integrated setup that handles both stock and accounts. Inventory software helps track quantities, locations and product movement. Accounting software helps manage sales, purchases, payments, taxes, receivables and payables. A seller with only a few items may start simple, but a growing shop should connect inventory with accounting so the owner can see both stock and money accurately.
Can TallyPrime be used for Amazon sales accounting?
Yes, TallyPrime can be configured to record Amazon sales, returns, fees, marketplace receivables, TCS, TDS and bank settlements, subject to correct ledger mapping and current product capabilities. Sellers should verify the exact import method, feature availability and GST treatment with current TallyPrime documentation, an authorized partner and their accountant.
Why should Amazon bank receipts not be treated as sales?
Amazon bank receipts are usually net settlements after deductions, returns and adjustments. The actual customer sales value, fees, TCS, TDS, refunds and reimbursements may be visible only in marketplace reports. If a seller records only the bank receipt as sales, revenue, expenses, tax-related receivables and returns may be misstated.
How often should marketplace reconciliation be done?
Marketplace reconciliation should ideally be reviewed at least monthly, and more often if online order volume is high. Regular reconciliation helps identify missing settlements, high returns, incorrect fee posting, pending reimbursements and unmatched bank receipts before they become difficult to trace.
What should sellers confirm with their accountant before setting up ledgers?
Sellers should confirm GST treatment, applicable tax ledgers, TCS and TDS handling, sales return treatment, input tax review, filing requirements and any threshold or compliance rule relevant to their business. Tax rates and rules should be verified from current official guidance and professional advice rather than assumed.
Is Tally@Cloud useful for market sellers?
Tally@Cloud can be useful when owners, staff and accountants need authorized access from different locations. It may help with timely data entry and review. Before adoption, sellers should verify licensing, user permissions, backup policy, data security, support responsibility and internet dependency.
What is the biggest mistake in inventory management for local market shops?
The biggest mistake is often poor item master discipline. Duplicate item names, vague product descriptions and missing purchase entries lead to wrong stock reports. Once staff stop trusting stock reports, the software loses value. Clear naming, regular entry and periodic stock checking are essential.
How can a seller start improving records without disrupting daily sales?
Start in phases. Clean item masters, enter current purchases and sales properly, separate payment modes, record returns daily, and reconcile bank and marketplace receipts weekly or monthly. Do not try to perfect everything on day one. A practical routine followed consistently is better than a complex system that staff avoid.
CA. Priya Tanvi specializes in accounting compliance, GST advisory, and business reporting for small and growing enterprises. She works with business owners to improve record-keeping and financial clarity. Her articles focus on practical compliance solutions and operational discipline.