Call CA Tally HelpDesk
+91 9205471661,
7428779101
Introduction: Why Credit and Cash Flow Management Matter More Than Ever
A business can generate impressive sales and still struggle to pay its bills. This is one of the most challenging financial realities faced by small businesses, wholesalers, retailers, manufacturers and distributors across India.
In 2026, businesses are dealing with rising operational expenses, delayed customer payments, changing purchasing patterns and increasing pressure to maintain sufficient working capital. While generating revenue remains important, maintaining control over when money enters and leaves the business has become equally essential.
Poor credit management can create a dangerous cycle. Customers delay payments, suppliers demand settlements, inventory purchases become difficult, and business owners begin relying on expensive short-term borrowing.
This is where Tally Prime credit and cash flow management features become valuable.
By combining customer credit monitoring, outstanding receivables, payment tracking, bank reconciliation and financial reporting, Tally Prime helps businesses understand their financial position and make informed decisions.
A Business Owner's Story: When Growing Sales Created a Financial Crisis
Rajesh operated a wholesale electrical goods business in Delhi. Over several years, he built strong relationships with retailers and contractors by offering competitive prices and flexible credit facilities.
His monthly sales were growing steadily, and he believed his business was becoming financially stronger.
However, one morning, a major supplier called requesting immediate payment for an overdue invoice.
Rajesh checked his bank balance and discovered that he did not have enough funds to settle the amount.
He was confused. His business had generated substantial sales during the previous month. Where had the money gone?
After reviewing his records, he discovered that several customers had exceeded their agreed payment periods. Some invoices were overdue by more than 60 days, while others had remained unpaid for nearly three months.
The problem was not insufficient sales. It was insufficient cash collection.
The situation became emotionally difficult when Rajesh considered delaying employee salaries to manage supplier payments.
He decided to reorganize his accounting process using Tally Prime.
He began maintaining bill-wise customer balances, reviewing overdue receivables, setting customer credit limits and monitoring daily cash and bank balances.
Within the following months, his business developed a more disciplined collection process.
Although the transition required effort, Rajesh finally understood an important lesson:
Sales generate revenue, but timely collections keep a business running.
This is an illustrative business story created to explain common cash flow challenges.
1. Understanding Credit Management in Business
Credit management refers to the process of controlling the amount of money customers can owe a business and ensuring that outstanding payments are collected within agreed timelines.
Many businesses offer credit facilities to maintain customer relationships and increase sales.
For example, a distributor may allow retailers to purchase products with a 30-day payment period.
However, without proper monitoring, customers may continue purchasing products even when earlier invoices remain unpaid.
Effective credit management involves evaluating customer payment behavior, defining credit limits, monitoring outstanding invoices and following up on overdue payments.
How Tally Prime Helps
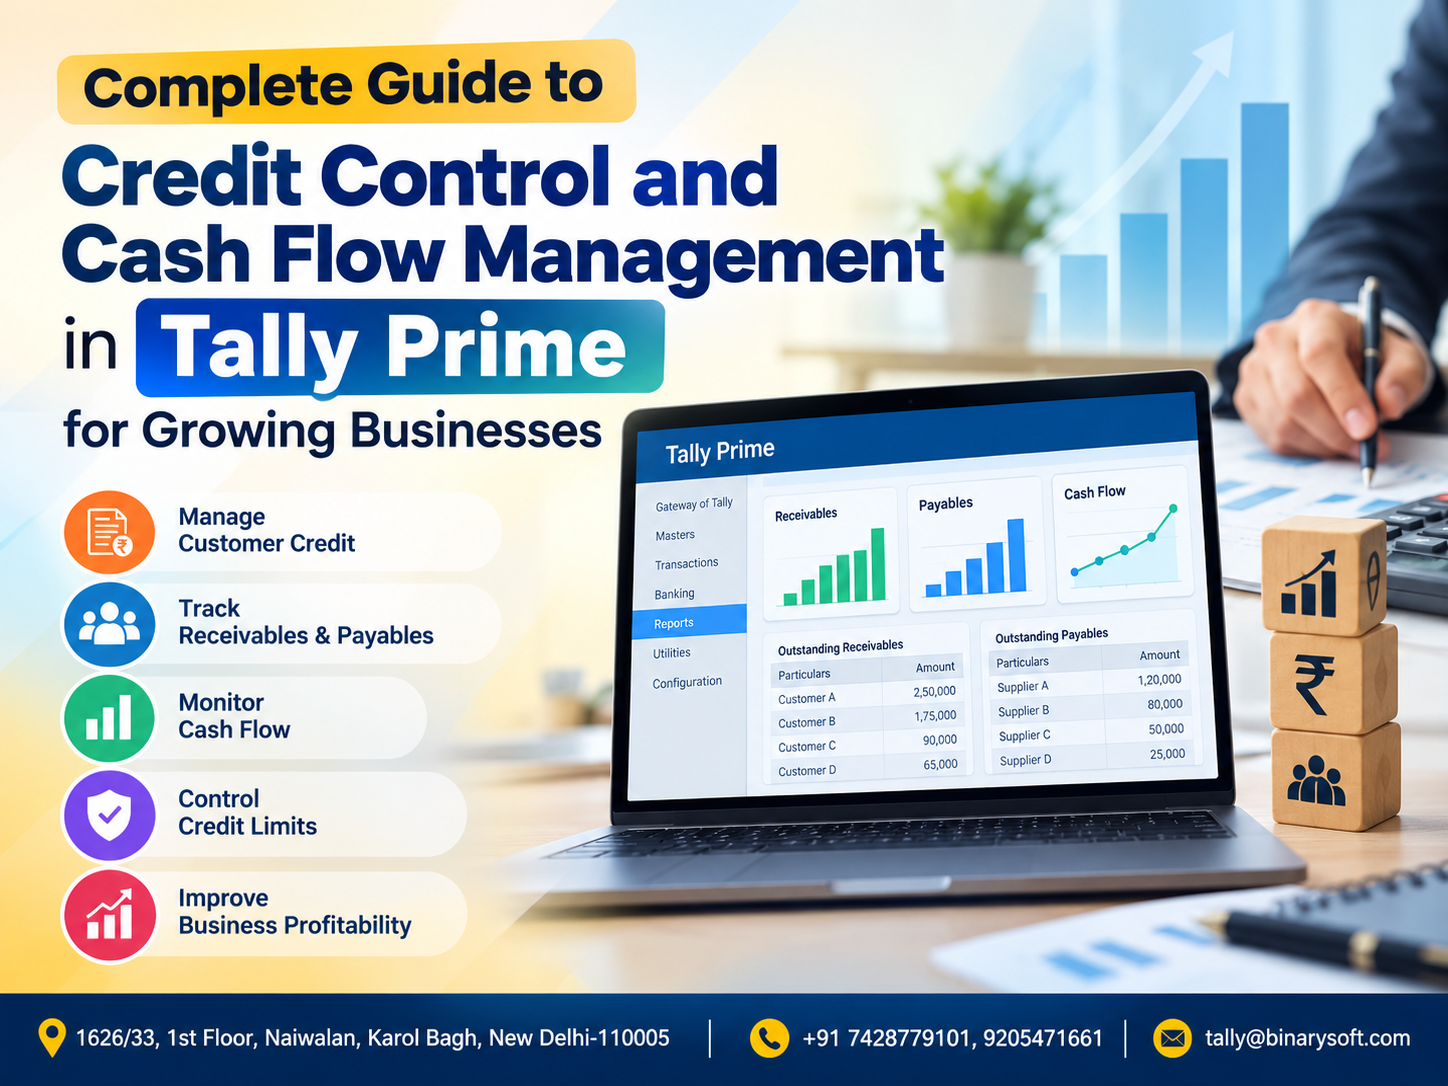
Tally Prime enables businesses to maintain customer ledgers, record credit transactions, track bill-wise receivables and review customer outstanding balances.
Businesses can also configure credit limits and credit periods for customer ledgers, helping users identify transactions that exceed agreed terms.
These controls support more disciplined sales decisions and reduce unnecessary credit exposure.
2. Customer Credit Limits for Better Financial Protection
A credit limit defines the maximum outstanding amount a business is willing to allow a customer.
For example, a wholesale supplier may assign a customer a credit limit of ₹2,00,000.
If the customer's outstanding balance reaches this amount, additional credit sales should be reviewed before approval.
Without credit limits, businesses may unknowingly extend excessive credit to customers who already have significant unpaid balances.
Managing Credit Limits in Tally Prime
Businesses can configure credit-related information in customer ledger records, including credit limits and credit periods.
During applicable sales transactions, Tally Prime can provide warnings or checks when configured limits are exceeded.
The business should establish an internal approval policy for exceptions, because software warnings alone do not replace credit authorization.
A practical credit policy should consider customer purchasing history, payment discipline, business relationship, financial capacity and current outstanding balances.
Regularly reviewing these factors helps prevent excessive receivables and improves financial stability.
3. Outstanding Receivables Management
Outstanding receivables represent amounts customers owe for goods or services already supplied.
A business may report high sales revenue but experience financial difficulties when customers delay payments.
Consider a company with monthly credit sales of ₹15,00,000.
If customers pay only ₹9,00,000 during the period, the remaining ₹6,00,000 increases outstanding receivables, assuming no other adjustments.
That amount represents money the business has earned through sales but has not yet collected.
Outstanding Reports in Tally Prime
Tally Prime provides receivables reports that help businesses review unpaid customer balances.
Users can analyze outstanding invoices, customer-wise balances, overdue amounts and pending collections.
Bill-wise tracking allows payments to be allocated against specific invoices, improving accuracy when customers make partial payments.
For example, if a customer owes ₹80,000 against two invoices and pays ₹30,000, the payment can be adjusted against the relevant bill.
This helps the accounting team identify exactly which invoices remain unpaid.
4. Receivables Ageing Analysis
Receivables ageing helps businesses understand how long customer payments have remained outstanding.
An ageing report categorizes receivables into time periods, allowing managers to identify customers requiring immediate attention.
A typical ageing structure may look like this:
The finance team can prioritize these balances for collection, while considering agreed payment terms and any disputed invoices.
Benefits of Ageing Reports
Ageing analysis helps businesses recognize slow-paying customers, reduce collection delays, identify potential bad debts and plan future cash inflows.
Tally Prime supports receivables ageing analysis, helping managers evaluate outstanding balances by relevant periods.
Regular ageing reviews can improve the efficiency of credit collection activities.
5. Cash Flow Management and Monitoring
Cash flow management involves tracking the movement of money into and out of a business.
Cash inflows may include customer payments, cash sales, interest receipts and financing proceeds.
Cash outflows may include supplier payments, salaries, rent, electricity expenses, loan repayments and taxes.
A profitable business can experience cash shortages when its payments become due before customers settle their invoices.
Cash Flow Statement in Tally Prime
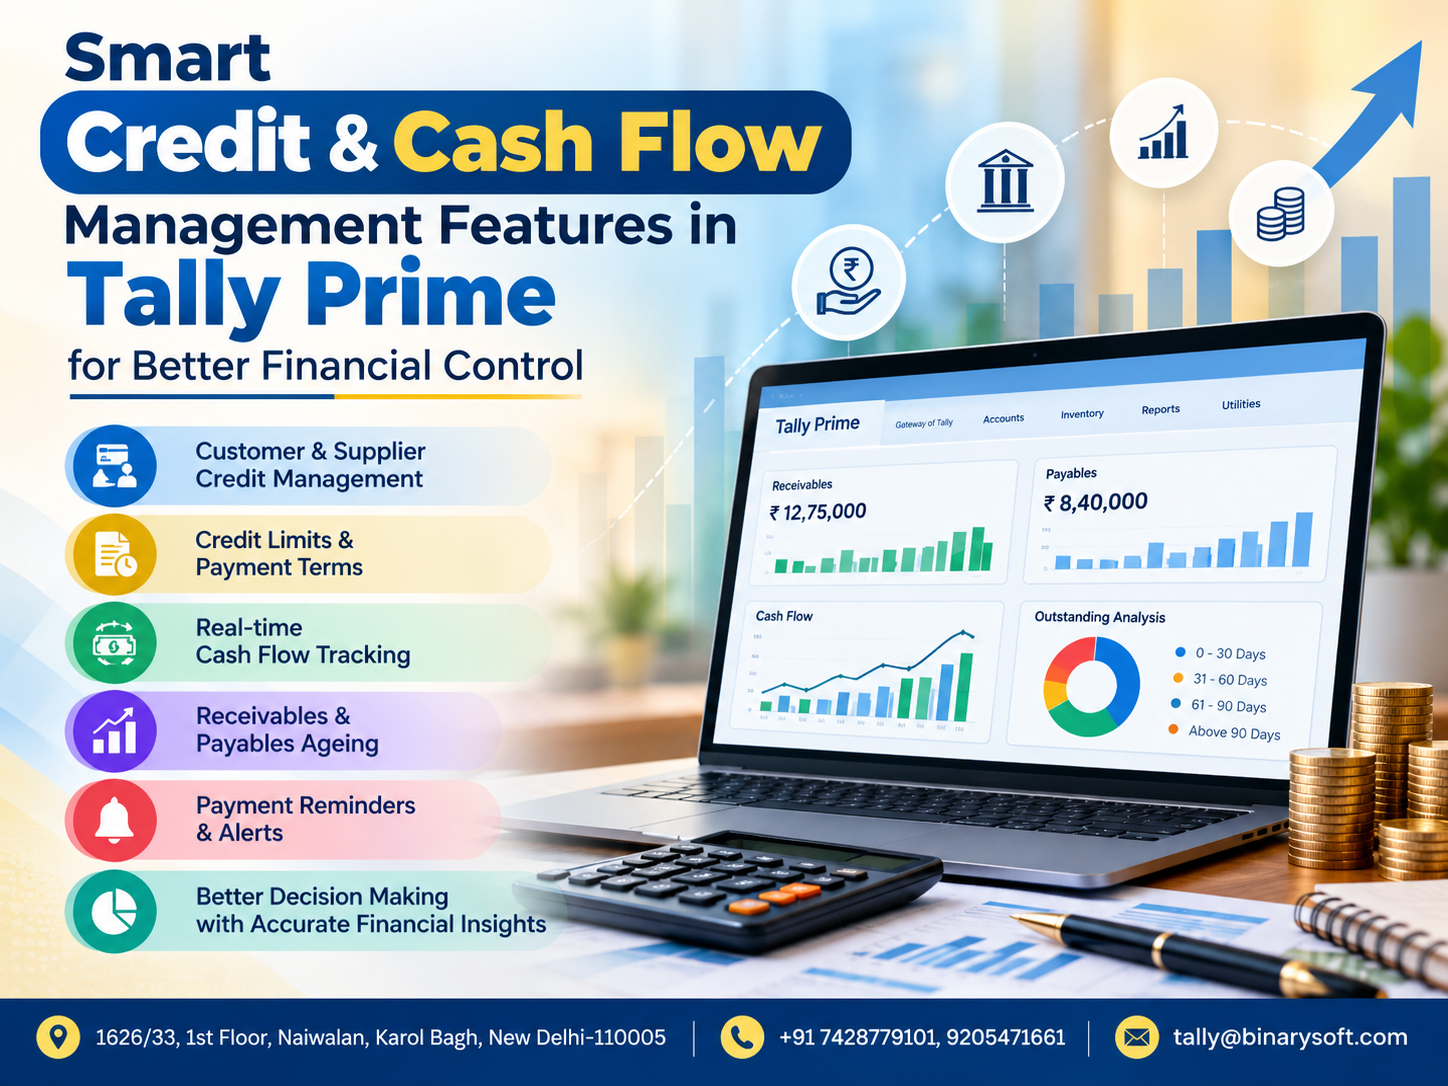
Tally Prime provides cash flow reporting that helps businesses analyze cash movement across selected periods.
Managers can review changes in available funds and understand how recorded transactions affect liquidity.
Cash flow reporting becomes more useful when combined with customer outstanding reports, supplier payables and expected payment schedules.
However, a historical cash flow statement is different from a forward-looking cash flow forecast. Future cash requirements should be estimated separately using expected receipts, payments and other obligations.
6. Managing Supplier Payments and Outstanding Payables
Credit management is not limited to collecting money from customers.
Businesses must also manage payments owed to suppliers.
Poor payable management can damage supplier relationships, interrupt product deliveries and create unnecessary financial pressure.
For example, a manufacturing company may need to settle raw material invoices before receiving its next shipment.
If customer collections are delayed, supplier payments may become difficult.
Payables Management in Tally Prime
Tally Prime helps businesses maintain supplier ledgers, track purchase invoices, record payments and review outstanding payable balances.
Bill-wise accounting makes it easier to identify pending supplier invoices and their due dates.
Businesses can use these reports to prioritize essential payments and avoid overlooking financial commitments.
Effective payable management should balance timely supplier settlements with maintaining sufficient operating cash.
7. Cash Flow Projection for Future Financial Planning
Knowing the current bank balance is important, but understanding future cash requirements is even more valuable.
Cash flow projection helps businesses estimate the amount of money likely to become available during upcoming weeks or months.
For example, a company may expect customer collections of ₹8,00,000 during the next 30 days.
Using Tally Prime for Cash Flow Projection
Tally Prime includes cash flow projection reporting to help businesses estimate future receipts, payments and expected balances using available accounting information.
Business owners can use these projections to evaluate purchasing decisions, plan investments, manage supplier commitments and identify potential cash shortages.
Projections should be reviewed against actual payment behavior because an invoice becoming due does not guarantee that the customer will pay on time.
8. Payment Reminders and Collection Follow-Ups
Delayed payments often occur because businesses lack a structured collection process.
Some customers genuinely forget payment deadlines, while others require repeated follow-ups.
A professional reminder system can improve collection efficiency without damaging customer relationships.
Tally Prime supports outstanding statements and reminder communications that help businesses follow up on pending payments.
Depending on the configured communication services, statements can be shared through supported digital channels.
Businesses should establish a consistent reminder schedule.
For example, an accounts team might send a friendly reminder three days before the due date, follow up on the due date and escalate overdue balances according to company policy.
Maintaining professional communication encourages timely settlements and improves financial discipline.
Tally Prime supports interest calculations based on configured terms, including applicable simple or compound interest methods.
This can help businesses monitor financing costs associated with delayed collections.
However, interest should only be charged when supported by customer agreements and applicable legal requirements.
10. Bank Reconciliation for Accurate Cash Balances
Cash flow decisions depend on reliable accounting records.
A difference between bank statements and accounting records can create confusion about available funds.
For example, a business may record a supplier payment that has not yet cleared the bank.
Similarly, a customer may transfer money that has not yet been recorded in the accounting system.
Bank reconciliation helps identify these differences.
Benefits of Bank Reconciliation in Tally Prime
Tally Prime provides banking and reconciliation features that help businesses compare recorded transactions with bank information.
Depending on the supported bank, software release and configuration, businesses may use statement imports and available connected banking capabilities.
Regular reconciliation helps identify missing entries, duplicate transactions, uncleared payments and recording errors.
Accurate bank balances improve the reliability of cash flow decisions.
11. Financial Reports for Better Decision-Making
Effective financial control requires more than monitoring daily collections.
Business owners need a broader understanding of profitability, liabilities, assets and working capital.
Tally Prime provides several financial reports that support these decisions.
The Balance Sheet helps assess assets, liabilities and the overall financial position.
The Profit and Loss Account helps evaluate business income, expenses and profitability.
Cash Flow reports show the movement of cash and bank funds.
Outstanding Receivables and Payables reports identify money to be collected and payments to be made.
By reviewing these reports together, management can make more informed decisions about credit policies, purchasing, expenses and financing.
12. Step-by-Step Credit Management Setup in Tally Prime
Businesses can establish a structured credit management process through the following steps.
Step 1: Enable bill-wise accounting
Open Gateway of Tally, select F11 Features and enable bill-wise entries under the applicable accounting settings.
Step 2: Configure customer ledgers
Create or alter customer ledgers under Sundry Debtors. Enable bill-wise balance tracking and define the appropriate credit period.
Step 3: Set credit limits
Use the relevant ledger configuration options to enable and specify customer credit limits.
Step 4: Record credit sales
Create sales invoices and maintain appropriate bill references and due dates.
Step 5: Record customer receipts
When customers make payments, use Receipt vouchers and allocate the amounts against the appropriate outstanding invoices.
Step 6: Review outstanding receivables
Navigate to Display More Reports, Statements of Accounts, Outstandings and Receivables, or use the Go To search facility.
Step 7: Analyze overdue payments
Use ageing analysis to identify overdue invoices and prioritize collections.
Step 8: Monitor cash flow
Open the Cash Flow report to examine receipts, payments and cash movement.
Step 9: Review financial performance
Compare cash flow information with the Balance Sheet, Profit and Loss Account and outstanding reports.
The exact screen labels and available options may vary according to the Tally Prime release and enabled features.
13. Case Study One: Wholesale Distributor Improves Payment Collections
Illustrative case study based on common wholesale business challenges.
Business Background
A wholesale electrical distributor in Karol Bagh supplied products to retailers across Delhi NCR.
The company generated approximately ₹25 lakh in monthly sales, with a significant proportion sold on credit.
However, its accounting team struggled to track outstanding invoices.
Customer balances were maintained in spreadsheets, and payment follow-ups were inconsistent.
Business Challenges
The company faced overdue receivables, unclear customer credit exposure and frequent supplier payment pressure.
Management also lacked a reliable view of which customers were consistently delaying settlements.
Solution Using Tally Prime
The company introduced bill-wise accounting, configured customer credit limits and started reviewing receivables ageing reports every week.
Customer receipts were allocated against individual invoices.
The accounts team also created a structured payment reminder process and reviewed cash flow information before major purchases.
14. Case Study Two: Manufacturing Company Reduces Cash Flow Pressure
Illustrative case study showing a practical manufacturing scenario.
Business Background
A small manufacturing company in Bawana, Delhi, produced packaging materials for wholesalers and industrial customers.
Although customer orders were increasing, the business frequently experienced shortages of working capital.
Raw materials had to be purchased before finished products could be delivered and customer payments collected.
Financial Challenges
The company faced inconsistent customer payment cycles, unpredictable raw material expenses and difficulty coordinating supplier payments.
Management had limited visibility into future cash requirements.
Solution Using Tally Prime
The company organized supplier and customer ledgers, introduced invoice-wise tracking and began monitoring expected cash inflows and outflows.
Cash flow projections helped management identify periods when major payments might exceed expected collections.
The company also reviewed outstanding receivables before approving additional credit sales.
Illustrative Results
Within four months, the example business reduced its average customer collection period from 55 days to 42 days.
The 13-day improvement reduced the amount of capital tied up in receivables.
Supplier payment planning also became more predictable, helping management schedule inventory purchases more carefully.
This case illustrates how financial visibility can support business stability without requiring higher sales volumes.
15. Best Practices for Maintaining Healthy Cash Flow
Businesses should treat cash flow management as a regular operational responsibility rather than an occasional accounting exercise.
Reviewing customer receivables every week helps identify delayed payments before they become serious problems.
Credit limits should be evaluated periodically, particularly when customers increase purchasing volumes or develop inconsistent payment behavior.
Businesses should also avoid purchasing excessive inventory simply because sales are growing.
Inventory that remains unsold ties up working capital and can increase storage costs.
Supplier payment schedules should be coordinated with realistic customer collection expectations.
Maintaining an appropriate cash reserve can help businesses manage unexpected expenses and temporary collection delays.
Finally, management should review financial reports regularly rather than waiting until the end of the financial year.
A combination of accurate accounting records, consistent collections and careful financial planning creates stronger long-term control.
16. Why Tally Prime Is Useful for Growing Indian Businesses
Tally Prime brings accounting, invoicing, inventory management, outstanding tracking and financial reporting into a connected business environment.
For retailers, it helps maintain customer balances and monitor daily transactions.
For wholesalers and distributors, it supports credit limit management, invoice-wise receivables and supplier payment planning.
For manufacturers, it helps connect accounting information with purchasing, inventory and financial reporting.
For service businesses, it provides visibility into unpaid invoices, customer balances and operating expenses.
Its reporting capabilities help management identify financial problems earlier and take corrective action.
Businesses using a properly configured cloud-hosted environment may also benefit from authorized remote access to their accounting system, subject to the hosting setup, permissions and security controls.
The greatest advantage comes from combining software capabilities with disciplined accounting practices and regular management reviews.
Conclusion
Smart credit and cash flow management is essential for maintaining financial stability in a competitive business environment.
Increasing sales alone cannot guarantee business success when customer payments remain delayed and supplier obligations continue to grow.
Businesses must understand how much money customers owe, when payments are expected, which suppliers need to be paid and whether sufficient funds will be available for future operations.
Tally Prime provides practical tools for customer credit monitoring, bill-wise accounting, outstanding receivables, payable management, ageing analysis, interest calculation and cash flow reporting.
These features help business owners move beyond reactive financial management toward more informed decision-making.
By implementing clear credit policies, monitoring collections, reviewing financial reports and planning future cash requirements, businesses can strengthen working capital management and reduce avoidable financial pressure.
Better financial control begins with accurate information, timely collections and disciplined cash flow planning.
Powered by Binarysoft Technologies
Authorized Tally Partner
Location: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact Us: +91 7428779101, 9205471661
Email: tally@binarysoft.com
Business Hours: 10:00 AM – 6:00 PM, Monday to Friday
Binarysoft Technologies helps businesses implement and use Tally Prime for accounting, inventory management, financial reporting, credit monitoring and business operations.
Frequently Asked Questions
What is credit management in Tally Prime?
Credit management in Tally Prime involves tracking customer outstanding balances, defining credit limits, maintaining credit periods and monitoring overdue invoices. These features help businesses control customer credit exposure and improve payment collections.
How can Tally Prime help improve cash flow?
Tally Prime provides cash flow reports, cash flow projections, receivables tracking, payables management and financial statements. These tools help businesses monitor funds and plan financial commitments more effectively.
Can I set customer credit limits in Tally Prime?
Yes. Businesses can configure credit limits for customer ledgers and use applicable checks or alerts to monitor transactions that exceed defined limits.
How do I check outstanding customer payments?
Open the Receivables report under Statements of Accounts and Outstandings. You can review pending invoices, customer balances, due dates and overdue amounts.
CA. Devansh Rathi works closely with wholesalers, distributors, and growing enterprises on taxation, reconciliations, and financial controls. His approach emphasizes accurate records, timely compliance, and efficient accounting systems.