Call CA Tally HelpDesk
+91 9205471661,
7428779101
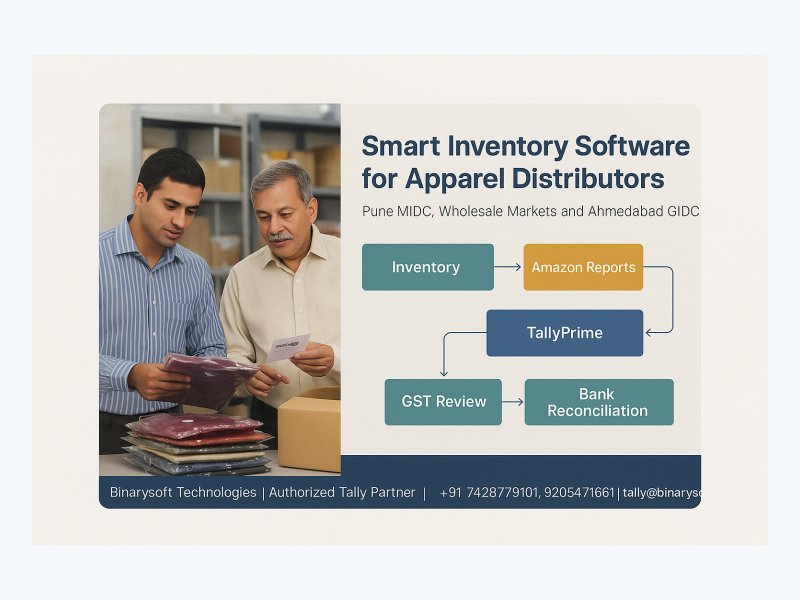
In 2026, apparel distributors are not struggling because of one single new rule; they are struggling because business has become faster than their back-office records. A seller supplying Pune MIDC units, Ahmedabad GIDC buyers, local wholesale markets and Amazon customers may dispatch hundreds of size, colour and style combinations in a single week. Payments arrive later in settlements, returns come back in mixed condition, marketplace fees reduce receipts, and GST records must still tell a clean story. When inventory records are weak, profit becomes guesswork and the accountant spends month-end repairing data instead of reviewing it. Smart inventory software, used correctly with TallyPrime and a disciplined reporting process, helps distributors see what sold, what came back, what is still sellable, what is blocked, and what actually reached the bank.
Suggested URL slug: smart-inventory-software-apparel-distributors-pune-midc-ahmedabad-gidc
Why Apparel Distribution Needs Smarter Inventory Control Now
Apparel distribution is different from many other trading businesses. A distributor does not merely handle one item called a shirt or one item called a kurti. The actual stock is split across style, size, colour, fabric, brand, season, batch, supplier, price band and sales channel. A single design may have six sizes, eight colours and two fabric variations. If the same product is sold through a Pune MIDC buyer, a Delhi wholesaler, an Ahmedabad GIDC customer and an Amazon listing, one wrong stock entry can create a chain of errors across dispatch, billing, cash flow and tax records.
For distributors working around Pune MIDC industrial areas, local wholesale markets and Ahmedabad GIDC industrial hubs, speed is a daily requirement. Buyers often expect quick availability confirmations. Factory-linked customers want dispatch planning. Retailers ask for replacement sizes. E-commerce customers return items without caring how complicated the accounting becomes. The business owner must answer simple questions: what is available, where is it available, how much margin is left after fees, what is pending from Amazon, what is pending from wholesale buyers, and whether the GST data is ready for review.
This is where smart inventory software becomes more than a stock register. It becomes the discipline that connects purchase, manufacturing inward, godown movement, dispatch, sales invoices, return vouchers, marketplace reports, settlement receipts, GST ledgers and accountant review. TallyPrime is widely used by Indian businesses for accounting and inventory, but the result depends on configuration, data discipline and reconciliation habits. Sellers should always verify current product capabilities from official TallyPrime documentation and confirm tax treatment with their accountant, because features, filing requirements, tax rates and marketplace report formats can change.
The Apparel Distribution Problem Across Pune MIDC, Wholesale Markets and Ahmedabad GIDC
An apparel distributor operating across these regions usually faces a mixed sales model. Pune MIDC customers may include manufacturers, institutional buyers, factory staff uniform buyers, local wholesalers, packaging-linked units and retail aggregators. Ahmedabad GIDC buyers may include garment processors, exporters, industrial uniform suppliers, textile traders and distribution partners. Wholesale markets add another layer: fast-moving buyers, credit sales, rate negotiations, partial dispatches, returns, replacements and transport-based deliveries.
On top of this, many distributors now sell on Amazon or other online marketplaces. Marketplace sales are attractive because they can open demand beyond one city. However, they also create accounting pressure. The sales may be visible in the Amazon order report, but the money received in the bank is not equal to gross sales. The settlement usually includes deductions, returns, commission, shipping-related charges, promotional charges, tax-related entries, TCS, TDS or other adjustments depending on the marketplace report and current rules. The seller must not treat the bank receipt as the full sales value without checking the report behind it.
In apparel, returns are not a side issue; they are part of the operating model. A returned item may be sellable, damaged, size exchanged, colour mismatched, courier-damaged, customer-used, missing tag, or returned after the settlement cycle. Each situation can affect inventory, accounting and margin differently. If all returns are entered as one monthly adjustment, the business loses control over real stock and profit.
Common symptoms of weak inventory records
- Stock shown in TallyPrime does not match physical stock at the warehouse.
- Amazon available quantity differs from internal stock records.
- Returns are received physically but not recorded in inventory on time.
- Bank receipts from marketplaces are entered as direct sales without settlement breakup.
- Fees, TCS, TDS and other deductions are posted to one miscellaneous ledger without review.
- GST reports need heavy manual correction before filing.
- Wholesale credit balances do not match buyer confirmations.
- Fast-moving sizes go out of stock while slow-moving colours occupy warehouse space.
- Purchase planning is based on memory, not SKU movement.
- Branch or godown transfers are recorded late, causing double-selling or stock shortages.
These problems are not solved by buying software alone. They are solved by designing the right inventory structure, using TallyPrime consistently, separating sales channels, reading marketplace reports correctly and reconciling bank receipts with settlement reports. Smart inventory software is effective when it supports a practical business workflow.
A Realistic Story From Karol Bagh: The Month-End That Changed Everything
The following story is illustrative and not a real customer case. It is written to show the kind of situation many apparel sellers can recognize.
Rohit ran a family apparel distribution business near Karol Bagh. His father had built the trade with personal relationships, handwritten notes and a sharp memory for customers. Rohit expanded the same business into online sales, small wholesale supply to Pune buyers, and periodic bulk orders to Ahmedabad-linked traders. The business looked successful from the outside. Cartons moved every day. The phones kept ringing. Amazon orders came in even during lunch. Transporters knew the shop address without asking.
But Rohit dreaded the last week of every month. His accountant would call and ask for Amazon settlement details, return records, GST breakup, credit notes and purchase bills. The warehouse team would say that the stock was available, but the Amazon listing showed out of stock. A wholesale buyer would claim that two cartons were short. A returned kurti lot would sit near the back wall because nobody knew whether it was sellable. Rohit often stayed late after the shutters were down, opening Excel files, WhatsApp images and marketplace reports on three screens.
The emotional weight was not only about money. Rohit felt he was letting down the business his father had built. His father would ask a simple question: how can sales be increasing but cash be tight? Rohit had no simple answer. The bank showed receipts from Amazon, but those receipts were not the same as sales. Fees had been deducted. Some orders were returned. Some TCS or TDS-related entries required proper accounting review. Some wholesale invoices were unpaid. Some stock was blocked in sizes that did not move. The family could see activity, but not clarity.
The turning point came after a buyer asked for a repeat order of a fast-moving black shirt in medium and large sizes. Rohit promised dispatch by evening because Tally showed enough pieces. When the warehouse checked, the medium size had already been picked for online orders and two cartons were actually returned stock awaiting quality check. The buyer cancelled the order. That evening, Rohit realized the problem was not effort. His team was working hard. The problem was that sales, inventory, returns, settlements and bank receipts were not connected in a reliable process.
Rohit did not need magic. He needed a disciplined setup. He needed item names that showed style, colour and size. He needed godowns for ready stock, returned stock and damaged stock. He needed Amazon sales separated from wholesale sales. He needed settlement reports posted correctly instead of treating bank credits as total income. He needed a checklist his staff could follow before month-end. Most importantly, he needed everyone to stop saying, we will adjust later. In apparel distribution, later usually means confusion, lost margin and avoidable stress.
What Smart Inventory Software Should Mean for Apparel Distributors
The phrase smart inventory software is sometimes used loosely. For an apparel distributor, it should not mean a dashboard that looks modern but fails during reconciliation. It should mean a system that helps the business capture the right details at the right time and convert them into usable accounting, inventory and tax data.
In practical terms, smart inventory software for apparel distributors should help you answer these questions without panic:
- Which style, colour and size combinations are available right now?
- Which items are in Pune, Ahmedabad, Delhi, a warehouse, a branch, a transporter hold area or return inspection?
- Which items are sold but not yet dispatched?
- Which Amazon orders are settled, returned, disputed or pending settlement?
- Which marketplace deductions are fees and which are tax-related entries requiring accountant review?
- Which wholesale customers are overdue?
- Which SKUs are profitable after marketplace charges and returns?
- Which stock should be replenished before the next sales cycle?
- Which slow-moving items should be discounted or bundled?
- Which reports should be shared with the accountant before GST review?
TallyPrime can be used as a strong foundation for accounting and inventory when configured carefully. Businesses should confirm the exact features available in their current TallyPrime version and edition, and should verify whether additional integrations, import utilities or custom workflows are required for marketplace data. The smartest setup is usually not the most complex setup. It is the one that the team can use every day without bypassing it.
Designing a Clean SKU Structure for Apparel
Inventory accuracy starts with item naming. Apparel sellers often create item names casually in the beginning and then suffer later. For example, if one staff member creates Black Shirt M, another creates Shirt Black Medium, and a third creates BLK Shirt Med, reports will not show the true movement of that product. The same item becomes three items. Purchase planning fails. Sales analysis fails. Stock transfer becomes confusing.
A clean SKU structure should be simple, readable and consistent. It should contain the information needed by sales, warehouse and accounting teams. A distributor may create an internal SKU format that includes brand or category, style code, colour and size. The exact format depends on the business, but consistency is non-negotiable.
Example SKU naming approach
- Category: SHIRT, TSHIRT, KURTI, TROUSER, UNIFORM, SAREE, LEGGING.
- Style code: supplier style number or internal design code.
- Colour: standard short code such as BLK, WHT, NVY, RED, GRN.
- Size: XS, S, M, L, XL, XXL or numeric size.
- Optional batch or season: SS26, FW26, FESTIVE, SCHOOL, CORPORATE.
An example could be SHIRT-ST145-BLK-M or KURTI-KR220-MRN-L. The goal is not to make names fashionable; the goal is to make them searchable, sortable and auditable. If the team can identify the product from the SKU and the reports can group it properly, the naming system is doing its job.
In TallyPrime, businesses can use stock groups, stock categories, units, godowns and item masters according to their requirements. The exact configuration should be verified with current TallyPrime documentation or an authorized partner, because available options and recommended workflows may depend on version, licensing and business needs. The principle remains the same: define your item structure before data becomes messy.
Stock Groups, Categories and Godowns in TallyPrime
For apparel distributors, a useful structure in TallyPrime often begins with stock groups and categories. Stock groups may represent product families such as shirts, trousers, kurtis, uniforms, ethnic wear, innerwear, winter wear or accessories. Stock categories may represent size, colour, brand, season, fabric or channel, depending on how the business wants to analyze stock. The right choice depends on reporting needs.
Godowns or locations are equally important. Many distributors physically store stock in more than one place, even when they think they have only one warehouse. There may be ready stock, damaged stock, returned stock, display stock, packing area stock, transport pending stock and branch stock. If everything is treated as one location, the system may show inventory that cannot actually be sold.
Practical godown structure for an apparel distributor
- Main Warehouse: sellable stock ready for dispatch.
- Amazon Allocated Stock: stock reserved or planned for online sales, if the business separates it.
- Wholesale Dispatch Hold: packed stock awaiting transporter pickup.
- Return Received: stock physically returned but not yet quality checked.
- Sellable Return Stock: returned stock approved for resale.
- Damaged or Reject Stock: items not suitable for normal sale.
- Pune MIDC Stock Point: local stock if maintained near Pune buyers.
- Ahmedabad GIDC Stock Point: local stock if maintained near Ahmedabad buyers.
Not every business needs all these godowns. Too many locations can create extra work if the team is small. Too few locations can create false availability. The correct structure is the simplest structure that reflects real movement. A practical way to decide is to ask: does this stock location affect selling, dispatch, return handling or valuation? If yes, it may deserve separate tracking.
Separating Sales Channels Without Splitting the Business Into Chaos
An apparel distributor may sell through wholesale invoices, counter sales, institutional orders, Amazon, other marketplaces, B2B portals and direct social commerce. If all sales are posted to one sales ledger, it becomes difficult to know which channel is profitable. If every channel has too many ledgers, posting becomes slow and errors increase. The balance is to create enough separation for analysis and reconciliation.
For example, a business may maintain separate sales ledgers for wholesale sales, Amazon sales, other marketplace sales and export or interstate institutional sales if applicable. GST treatment, place of supply, invoice rules and documentation should be confirmed with the accountant under current law. The software structure should support the tax treatment, not guess it.
Channel separation also helps identify return behavior. If one marketplace has high returns for certain sizes, the issue may be listing content, size chart mismatch or product quality. If wholesale returns are high from one city, the issue may be dispatch packing, buyer communication or wrong assortment. Without channel-wise data, the owner hears complaints but cannot measure them.
How to Organize Amazon Sales Data in TallyPrime
Amazon sales data should be handled with care because the order report, tax report, settlement report and bank receipt do not represent the same thing. Sellers often make mistakes because they look only at the bank credit. The bank credit is only the amount received after adjustments. It is not the gross sales value, not the fee breakup, not the return position and not the full tax record.
A disciplined process begins by downloading or accessing the relevant Amazon reports for the period under review. The exact report names and formats can change, so sellers should verify the current report set available in their Amazon seller account. Generally, the business should identify reports that show orders, invoices or tax information, returns, reimbursements if any, fees or charges, settlement details and payments transferred to the bank.
In TallyPrime, the seller should decide whether Amazon invoices are recorded order-wise, summary-wise or through an import process. The right method depends on order volume, GST requirements, reconciliation expectations and accountant advice. A small seller may post order-wise entries. A high-volume distributor may use structured summaries or integration tools. The key is that the posted data must remain auditable. If a number in TallyPrime cannot be traced back to an Amazon report, month-end review becomes difficult.
Suggested data buckets for Amazon reconciliation
- Gross sales value as per Amazon sales or tax report.
- Customer returns and credit notes or reversal entries.
- Marketplace fees and commission.
- Shipping, fulfillment or logistics-related charges as applicable.
- Promotional charges, advertising or discounts if reflected in reports.
- TCS entries as reported by the marketplace, subject to current verification.
- TDS entries if applicable, subject to current verification.
- GST output and input-related entries as advised by the accountant.
- Reimbursements, claims or adjustments if any.
- Net settlement amount transferred to the bank.
Each bucket should have a clear ledger treatment. The exact ledger names may vary, but vague ledgers such as Amazon Difference or Miscellaneous Charges should be avoided unless used temporarily with review. Permanent use of vague ledgers hides profit leakage.
Marketplace Reports Are Not Bank Receipts
One of the most common reconciliation mistakes is treating the marketplace bank receipt as sales. Suppose Amazon transfers an amount to the bank. That amount may be net of several deductions and adjustments. If the seller records only the bank amount as sales, gross revenue may be understated, expenses may be missing, tax-related entries may not match reports, and returns may not be properly reflected in inventory.
The marketplace report explains why the bank receipt is what it is. The bank statement confirms money received. Both are necessary, but they answer different questions. Marketplace reports answer what happened in the marketplace account. Bank receipts answer what money actually arrived. TallyPrime should be used to connect both, not replace one with the other.
Simple example of the difference
Assume an apparel seller has gross Amazon sales for a period. During the same period, some products are returned, marketplace fees are deducted, tax-related amounts such as TCS or TDS may be reported, and the net amount is transferred to the bank. If the seller posts only the bank receipt as sales, the records do not show the actual sales value, the deductions, the return impact or the tax-related entries clearly. The business may think margin is healthy because expenses are invisible, or it may think Amazon sales are lower than they actually were.
The correct approach is to record sales, returns, deductions and settlement receipts in a way that can be reconciled. The accountant should guide the exact voucher type and tax ledger treatment. Sellers should not assume rates, thresholds or filing treatment from old habits; these must be checked against current GST, income tax and marketplace documentation.
Handling Returns Without Losing Stock Accuracy
Returns can destroy inventory accuracy if they are not given a formal workflow. In apparel, a returned item should not automatically go back into sellable stock. It must be received, inspected and classified. The classification then determines whether it can be sold again, repaired, repacked, discounted or written off according to accounting advice.
A practical return workflow may include four stages. First, record that the return is expected or has been initiated by the customer. Second, receive the physical item and move it to a return received location. Third, perform quality check and decide whether it is sellable. Fourth, move sellable items back to available stock and damaged items to a separate location. If this is not done, the sales team may promise goods that are physically present but not sellable.
Return classification examples
- Sellable return: tag intact, packaging acceptable, no damage.
- Repack required: item okay but packaging damaged.
- Alteration or repair required: minor issue that can be corrected.
- Damaged stock: not fit for regular sale.
- Wrong item return: customer returned a different item or mismatch found.
- Missing accessory or tag: requires decision before resale.
For Amazon returns, the seller should match the return report with physical receipt and settlement adjustments. A return in the marketplace report does not always mean the item is physically back in sellable condition. Similarly, a physical return without correct report matching can create accounting gaps. The inventory team and accounts team must share a common return reference.
Understanding TCS, TDS and GST Data Without Guesswork
Marketplace sellers in India often see TCS, TDS and GST-related information in reports. These terms are important, but the exact rates, applicability, thresholds, return filing treatment and reconciliation process must be verified with a qualified accountant and current official guidance. This article does not provide tax advice and does not assume specific rates.
From an inventory and accounting process perspective, the seller should ensure that tax-related data is not mixed with ordinary fees. If a marketplace report separately shows TCS or TDS, the accounting team should capture it in appropriate ledgers and reconcile it with statutory records as advised. If GST-related sales or fee invoices are available, they should be preserved and mapped to TallyPrime entries. The goal is to make the accountant's review easier and reduce last-minute searching.
GST data for apparel can be sensitive because product classification, tax rate, value, place of supply, returns, credit notes and input credits may matter. Since rates and rules require current verification, sellers should not rely on memory or old rate charts. Before configuring tax ledgers or stock item tax details, confirm the applicable treatment with the accountant and current documentation.
What sellers should confirm with their accountant
- Current GST rate and classification for each product category.
- Whether different apparel values or product types have different treatment.
- Correct handling of marketplace sales invoices and credit notes.
- Correct treatment of Amazon fees and GST charged on marketplace services.
- TCS and TDS applicability, reporting and reconciliation.
- Whether marketplace reports reconcile with GST portal data.
- Documentation required for returns and credit notes.
- How interstate sales, local sales and branch transfers should be treated.
Good software cannot compensate for incorrect tax assumptions. A clean system gives the accountant better data. The accountant gives the business correct tax interpretation.
Building a TallyPrime Ledger Structure for Marketplace Sales
A useful TallyPrime setup for marketplace sales often includes separate ledgers for sales, returns, marketplace fees, shipping or fulfillment charges, advertising or promotion charges, TCS, TDS, GST-related accounts and marketplace receivables. The exact ledger structure must be aligned with the accountant's advice. The purpose is to avoid posting everything to one ledger and losing visibility.
For Amazon, many sellers use a marketplace receivable or Amazon settlement ledger to track the amount due from the marketplace. Sales entries increase the receivable. Deductions reduce it through expense or tax-related ledgers. Bank settlement receipts reduce the receivable when money is received. At any point, the balance should broadly represent unsettled or unreconciled amounts, subject to timing differences and pending returns.
Illustrative ledger categories
- Amazon Sales: sales posted from marketplace reports.
- Amazon Returns: sales reversal or credit note-related ledger treatment as advised.
- Amazon Commission or Fees: marketplace fee deductions.
- Amazon Shipping or Fulfillment Charges: logistics-related deductions if separately identified.
- Amazon Advertising or Promotion: promotional costs if applicable.
- Amazon TCS Receivable: tax collected at source data, if applicable and advised.
- Amazon TDS Receivable: tax deducted at source data, if applicable and advised.
- Amazon Receivable or Settlement: control ledger for amounts receivable from marketplace.
- Bank Account: actual settlement receipt.
This is not a universal ledger prescription. It is a conceptual structure. The accountant may recommend different ledger grouping, voucher treatment or reporting depending on the business and current rules. What matters is that each entry can be explained and reconciled.
Voucher Discipline in TallyPrime
In busy distribution businesses, voucher discipline is often the difference between useful accounts and decorative accounts. If entries are posted late, summarized without references or adjusted manually without explanation, the software cannot produce reliable insights. Every voucher should have enough detail to trace it back to a bill, order, settlement or stock movement.
For wholesale apparel sales, invoices should clearly mention buyer details, item details, quantity, rate, tax details as applicable, transport reference if needed and payment terms. For marketplace sales, the business must decide whether to post individual invoices or summaries. If summaries are used, the source report and period should be clearly referenced. For returns, credit notes or reversal entries should be linked to reports and physical stock receipt wherever practical.
Stock transfers between godowns should not be recorded as an afterthought. If goods move from Delhi to a Pune stock point or Ahmedabad stock point, the stock location in TallyPrime should reflect the movement when it happens or as close to real time as possible. Otherwise, the team may sell goods from the wrong location or assume stock is missing.
Reconciling Amazon Settlements Step by Step
Amazon settlement reconciliation should be a routine process, not a festival-season emergency. The exact reports may differ depending on Amazon's current seller interface, but the principle remains stable: compare sales, returns, fees, taxes, adjustments and bank receipts for the same settlement period.
Step 1: Define the settlement period
Identify the exact date range of the settlement. Do not mix order date, shipment date, invoice date and settlement date without understanding the difference. Marketplace reports may use different dates for different purposes. Reconciliation should be period-based and reference-based.
Step 2: Download or export the relevant reports
Collect sales, tax, return, fee, settlement and payment reports as available. Store them in a structured folder with period names. Do not depend only on screenshots. Reports should be saved in a format that can be reviewed later by accounts or audit teams.
Step 3: Match gross sales to TallyPrime entries
Check whether gross sales as per the report have been posted correctly. If order-wise posting is used, compare order totals. If summary posting is used, compare period totals and keep the report as backup. Differences should be identified before bank reconciliation.
Step 4: Match returns and credit notes
Returns should reduce sales or be recorded through credit notes as advised by the accountant. Physical returns should also be checked by the warehouse. A return that affects money but not stock, or stock but not money, must be investigated.
Step 5: Post fees and charges separately
Marketplace commission, fulfillment, shipping, closing fees, advertising or other charges should be posted to appropriate ledgers if separately reported. Sellers should verify the nature of each charge instead of grouping all deductions together.
Step 6: Capture TCS and TDS data carefully
If the settlement report shows TCS, TDS or similar tax-related deductions, post them according to accountant guidance. These amounts may need reconciliation with statutory records, so they should not be hidden in general expense ledgers.
Step 7: Match bank receipt
After sales, returns, fees and tax-related entries are posted, the net settlement should match the bank credit, allowing for timing differences or pending adjustments. If the bank amount is forced to match by posting an unexplained difference, the problem will return later.
Step 8: Review unsettled balance
The Amazon receivable or settlement ledger should be reviewed after each cycle. A balance may represent pending settlements, timing differences, disputes, reimbursements, unposted returns or posting errors. It should not remain unexplained month after month.
Common Reconciliation Mistakes and How to Avoid Them
Most reconciliation errors happen because the team is trying to save time. Unfortunately, shortcuts in marketplace accounting usually create more work later. Apparel distributors should train staff to recognize the most common mistakes.
- Mistake 1: Recording bank receipt as sales. This hides gross sales, fees, returns and tax-related entries. Use settlement reports to post the full breakup.
- Mistake 2: Ignoring returns until month-end. Apparel returns affect stock availability immediately. Record them through a defined workflow.
- Mistake 3: Posting all deductions to one ledger. Fees, tax-related deductions, advertising and logistics charges should be understood separately.
- Mistake 4: Mixing wholesale and marketplace sales. Separate sales channels for better margin and return analysis.
- Mistake 5: Not matching physical returns with report returns. A report entry does not always mean sellable stock is back.
- Mistake 6: Using inconsistent item names. Duplicate SKUs ruin inventory analysis.
- Mistake 7: Delaying godown transfers. Stock location errors create false availability.
- Mistake 8: Assuming tax treatment from memory. Confirm current rates, thresholds and filing rules with the accountant.
A good monthly close is built from small daily habits. If sales, returns and settlements are updated weekly, month-end becomes review work instead of rescue work.
Wholesale Market Realities: Credit, Rate Differences and Partial Dispatch
Wholesale apparel trade has its own complexity. A buyer may negotiate different rates for the same item based on quantity, season, payment terms or relationship. Orders may be partially dispatched because one size is unavailable. Goods may be sent through transport, hand delivery or courier. Payment may arrive after deductions for shortage, quality issues or agreed discounts. If these realities are not recorded properly, receivables become confusing.
Smart inventory software should help record partial dispatch clearly. If a buyer ordered 500 pieces but only 420 were dispatched, the pending quantity should not disappear into conversation. If the remaining 80 pieces are cancelled, replaced or dispatched later, the records should show it. TallyPrime order processing and inventory features may help depending on configuration, but sellers should confirm current feature availability and suitability for their workflow.
Credit control is also important. Apparel distributors often focus heavily on stock but ignore customer outstanding until cash becomes tight. Channel-wise and customer-wise receivables should be reviewed regularly. A buyer with high sales but slow payment may be less profitable than a buyer with moderate sales and reliable payment.
Managing Stock Across Pune MIDC and Ahmedabad GIDC
When distributors supply industrial hubs, stock planning must consider geography. Pune MIDC customers may need faster replenishment for uniforms, workwear, promotional apparel or retail-linked orders. Ahmedabad GIDC customers may be connected to textile processing, garment trade, industrial supply or export-linked requirements. If stock is centralized far away, transport time can affect service. If stock is decentralized without control, inventory can get stuck in the wrong place.
A smart setup uses location-wise inventory. The owner should know not only total quantity but also quantity by location. For example, 1,000 pieces of a style may look sufficient, but if 700 are in Delhi, 200 are in Pune, 100 are in return inspection and Ahmedabad needs 300 urgently, the business has a fulfillment problem. Total stock is not the same as available stock.
Location-wise reorder planning can also reduce dead stock. Pune buyers may prefer different colours or sizes than Ahmedabad buyers. Industrial uniform buyers may order standard sizes in bulk, while retail wholesalers may demand more variety. Reports should show movement by location and channel so purchasing decisions are based on demand patterns, not assumptions.
Using Size and Colour Analysis for Better Purchase Planning
Apparel profitability is often hidden in size and colour movement. A product line may appear successful overall, but the profit may come from only a few combinations. Medium and large sizes may sell quickly while XS and XXL remain slow. Black, navy and white may move faster than experimental colours. If purchase planning is done only at style level, the distributor may reorder poor combinations and miss fast-moving ones.
Smart inventory reporting should show movement by SKU. If the business uses proper SKU naming and stock categories, it can identify which combinations sell, return or remain unsold. This helps negotiate better with suppliers. Instead of ordering an equal quantity of every size and colour, the distributor can order according to actual demand.
Practical purchase planning questions
- Which sizes sold fastest in the last 30, 60 and 90 days?
- Which colours have high return rates?
- Which styles sell well in wholesale but poorly on Amazon?
- Which Amazon listings generate sales but weak margin after fees?
- Which stock is blocked in one location while another location has demand?
- Which supplier styles produce fewer defects and returns?
- Which seasonal items need liquidation before the next season?
The answers depend on clean data. If the same item is entered under multiple names, reports will mislead the buyer. If returns are not posted correctly, movement analysis will exaggerate demand.
Margin Tracking After Marketplace Fees
Many sellers celebrate online sales volume without checking net margin. Apparel can have attractive gross margins, but returns, packaging, shipping, commission, advertising, discounts and damages can reduce profitability. Amazon sales should be reviewed after all deductions, not only on listed selling price.
A simple product profitability review compares purchase cost, selling price, marketplace fees, logistics or fulfillment charges, advertising cost if applicable, return rate, damaged return loss and tax impact as advised. Some products may be excellent for wholesale but weak for marketplace because of high return rates. Some products may work online only when bundled. Some may need better size charts or images to reduce returns.
TallyPrime can hold accounting and inventory data, but channel-wise profitability may require disciplined ledger use, item-wise cost tracking and sometimes additional analysis. Sellers should verify current reporting options and consider whether a Tally partner or accountant can help structure reports. The objective is not to create complicated dashboards. The objective is to stop selling products that create turnover without profit.
Data Import, Integration and Manual Entry: Choosing the Right Approach
Apparel distributors often ask whether Amazon data should be imported automatically into TallyPrime. The answer depends on order volume, staff capability, reconciliation needs and budget. Manual entry may work for low volume but can become slow and error-prone. Import utilities or integrations can save time but must be configured carefully and reviewed. Automation is useful only when mapping is correct.
Before choosing an integration, the seller should define what data must enter TallyPrime. Is it order-wise sales? Summary sales? Tax invoice details? Fees? Returns? Settlement entries? Inventory adjustments? If the answer is unclear, automation may simply move confusion faster. Start with a clear accounting design, then automate.
Questions to ask before automating
- Which Amazon reports will be used as the source?
- Will sales be posted order-wise or summary-wise?
- How will returns and credit notes be handled?
- How will item names in Amazon match stock items in TallyPrime?
- How will fees, TCS, TDS and GST-related entries be mapped?
- Who will review exceptions and failed imports?
- Can the accountant trace imported entries back to source reports?
- What happens if Amazon changes a report format?
Automation should reduce repetitive work, not remove accountability. A weekly review of imported data is still necessary.
Inventory Controls for Warehouse Teams
Software accuracy depends on warehouse discipline. If the warehouse dispatches goods without entries, receives returns without tagging, or substitutes sizes without informing accounts, the system will fail. The team must understand that every physical movement needs a record.
A practical warehouse process includes picking lists, packing checks, dispatch confirmation, return receipt tagging and periodic cycle counts. The warehouse should not wait for annual stock verification to find differences. In apparel, cycle counts by category or location can catch errors early. For example, count fast-moving Amazon SKUs every week, wholesale bulk stock every fortnight and slow-moving seasonal stock monthly.
Warehouse checklist
- Use consistent SKU labels on cartons and shelves.
- Separate sellable stock from return inspection stock.
- Do not mix damaged pieces with ready stock.
- Record stock transfers when goods move, not days later.
- Match picked items with invoice or order details before packing.
- Record shortages immediately.
- Tag returned goods with source, date and reason.
- Perform cycle counts for fast-moving SKUs.
The best accounting setup cannot overcome a warehouse that treats stock movement informally. Smart inventory software works when people follow the process.
GST Readiness and Document Discipline
GST readiness is not only about filing dates. It is about whether the records behind the return are clear. Apparel sellers should maintain sales invoices, purchase bills, credit notes, debit notes, marketplace reports, fee invoices, transport documents where relevant and reconciliation summaries. The exact documents required may depend on the nature of transactions and should be confirmed with the accountant.
When Amazon or another marketplace provides tax-related reports or invoices for fees, sellers should download and store them regularly. Do not wait until the portal removes old reports or the team forgets the period. File naming matters. A folder called Amazon September 2026 Settlement Reports is more useful than a desktop full of random downloads.
In TallyPrime, GST ledgers and item tax details should be configured only after confirming current tax treatment. If product categories have different rates or conditions, they should not be grouped casually. Incorrect configuration can lead to repeated correction work.
Monthly Closing Routine for Apparel Distributors
A monthly closing routine converts scattered activity into reliable financial records. The routine should begin before the month ends. Waiting until the accountant asks for data creates pressure and errors.
Suggested monthly close workflow
- Confirm all purchase bills are entered.
- Confirm all wholesale sales invoices are posted.
- Confirm Amazon sales reports are downloaded and recorded.
- Record returns and classify return stock.
- Post marketplace fees and settlement deductions.
- Reconcile TCS, TDS and GST-related entries with accountant guidance.
- Match marketplace settlement ledgers with bank receipts.
- Review customer outstanding and supplier payable balances.
- Check negative stock or unusual stock balances.
- Review godown-wise stock and investigate differences.
- Prepare GST data for accountant review.
- Lock or internally freeze reviewed periods if your process supports it.
This routine should be documented. If only one person knows it, the business is vulnerable. A simple written checklist can prevent repeated mistakes.
Useful Checklist Before Implementing Smart Inventory Software
Before implementing or improving inventory software, apparel distributors should prepare their master data and process decisions. Software implementation fails when businesses try to configure everything during a crisis.
- List all product categories and decide stock groups.
- Create a standard SKU naming format.
- Identify size, colour, fabric, brand and season attributes needed for reporting.
- Clean duplicate item names before migration or restructuring.
- Define godowns or stock locations.
- Separate sellable, returned and damaged stock.
- Decide sales channel ledgers.
- Define Amazon settlement ledger structure with accountant input.
- Confirm GST treatment for each product category.
- Confirm TCS and TDS handling for marketplace reports.
- Decide whether marketplace entries will be manual, imported or integrated.
- Train warehouse staff on stock movement discipline.
- Set weekly reconciliation days.
- Prepare a monthly closing checklist.
- Assign responsibility for report downloads and backup.
This checklist is not theoretical. It is the foundation for cleaner books, better purchase planning and fewer month-end surprises.
How TallyPrime Fits Into the Apparel Distributor's Workflow
TallyPrime is commonly used by Indian businesses for accounting, inventory and statutory reporting workflows. For apparel distributors, it can support structured item masters, stock groups, godowns, vouchers, ledgers, receivables, payables and GST-related accounting depending on configuration and current product capabilities. Sellers should verify exact features in their version and consult an authorized Tally partner for setup decisions.
A practical TallyPrime workflow for apparel distribution may connect purchase entry, stock receipt, location movement, sales invoice, return entry, credit note, marketplace settlement, bank receipt and GST review. The software should become the central record, not a place where numbers are typed after the real business happens elsewhere.
If the business uses Tally@Cloud, the advantage is operational accessibility for teams that need to work from different places, subject to licensing, security and implementation design. A distributor with accounts in Delhi, warehouse coordination for Pune orders and management review from another location may benefit from controlled access to the accounting environment. The exact setup, user access, backup process and security controls should be planned with a qualified service provider.
Tally@Cloud for Multi-Location Apparel Distribution
Tally@Cloud can be useful when the business wants authorized users to access Tally in a hosted environment instead of depending only on one office computer. For apparel distributors working across Karol Bagh, Pune MIDC, Ahmedabad GIDC and wholesale networks, this can support faster coordination if implemented correctly. However, cloud access should be treated seriously. User permissions, data backup, login discipline and access control matter.
A cloud-enabled Tally environment can help accounts teams update entries, management review reports and remote staff coordinate information, depending on the setup. It should not be used as an excuse for uncontrolled access. Every user should have a role. Sensitive accounting data should not be shared casually. The business should discuss security, backup and performance expectations with the service provider before implementation.
The best implementation combines TallyPrime knowledge, apparel inventory understanding and reconciliation discipline. Technology gives access. Process gives accuracy.
Reporting That Owners Should Review Every Week
Owners do not need to review every voucher, but they should review the right reports regularly. Weekly review prevents small issues from becoming month-end shocks.
Weekly owner reports
- Top-selling SKUs by channel.
- Slow-moving stock by age.
- Negative stock or unusual stock report.
- Godown-wise stock summary.
- Amazon settlement pending report.
- Marketplace fees as a percentage of sales.
- Returns by SKU and channel.
- Customer outstanding and overdue balances.
- Supplier payable summary.
- Gross margin or contribution review where data is available.
These reports help the owner ask better questions. Why are returns high for one size? Why is one Amazon settlement pending? Why is Pune stock low but Delhi stock high? Why are fees rising faster than sales? Better questions lead to better control.
Practical Example: From Order to Settlement
Consider an apparel distributor selling a branded kurti style through Amazon and wholesale. The item is KURTI-KR220-MRN-L. The business purchases 500 pieces and stores them in the main warehouse. It allocates 150 pieces for Amazon, keeps 300 for wholesale and leaves 50 as buffer. In TallyPrime, the item is created once with a consistent SKU. Stock locations show where the pieces are held.
During the week, Amazon sells 40 pieces. Wholesale buyers purchase 120 pieces. Ten Amazon customers initiate returns, but only six pieces are physically received by the weekend. Of those six, four are sellable and two are damaged. If the business simply reduces sales by ten and adds ten pieces back to stock, it will overstate sellable inventory. The correct process is to match marketplace return data with physical receipt and quality check.
At settlement time, Amazon transfers a net amount to the bank after deductions. The business posts gross sales, returns, fees, tax-related entries as advised, and the bank receipt. The Amazon receivable ledger is checked for pending balances. The warehouse stock shows remaining sellable pieces, return inspection pieces and damaged pieces separately. Now the owner can see the real picture: sales happened, some returns are pending, two pieces are damaged, fees reduced margin and the bank receipt is reconciled.
This is the difference between activity and control. Many businesses have sales activity. Fewer have inventory and accounting control.
Practical Example: Wholesale Partial Dispatch to Pune MIDC
Suppose a Pune MIDC buyer orders 600 corporate polo T-shirts in navy and grey across multiple sizes. The distributor has enough total stock but not enough XL in grey. Instead of delaying the entire order, the seller dispatches 480 pieces and keeps 120 pending. The invoice, delivery note or order record should clearly show what was dispatched and what remains pending, according to the business's documentation process.
If the pending 120 pieces are not tracked, the sales team may forget the commitment or purchase excess stock later. If the buyer cancels the pending quantity, the order status should be updated. If substitute sizes are accepted, the stock records should reflect the actual dispatch. This is especially important for industrial and institutional buyers, where repeat orders depend on reliability.
A smart inventory setup helps the distributor identify shortages before promising delivery. It also helps purchasing teams replenish the right sizes instead of ordering a random mix.
Practical Example: Ahmedabad GIDC Buyer and Location Planning
An Ahmedabad GIDC-linked buyer regularly purchases workwear trousers. The distributor notices that demand from Ahmedabad is stronger for darker colours and larger sizes, while Pune buyers order more standard size mixes. If all stock is analyzed only at company level, this pattern may remain hidden. If reports are reviewed by location and buyer type, the distributor can keep a better assortment near the relevant demand center.
Location planning does not always mean opening a full warehouse. It may mean reserving stock, planning transport earlier, or creating a reorder alert for certain buyers. The important point is that stock decisions should follow data. Apparel stock loses value when it sits in the wrong place for too long.
How to Reduce Dead Stock Without Panic Discounts
Dead stock is common in apparel. Sizes, colours and seasonal designs can stop moving. Panic discounts may clear space but can damage margins. A better approach is to identify slow-moving stock early and decide action by category.
Some slow-moving items can be bundled with fast-moving products. Some can be offered to wholesale buyers at negotiated lots. Some can be used for institutional promotions. Some can be listed online with improved images or size details. Some should be liquidated quickly before storage and ageing reduce value further. The right decision depends on age, condition, demand and margin.
Smart inventory reports should show stock ageing. If an item has not moved in 90 or 180 days, depending on the business cycle, it deserves review. The exact ageing threshold should be decided by the distributor. Fashion apparel may need faster action than uniform basics.
Training Staff to Use the System
Software implementation often fails because only the owner understands why it matters. Staff members see it as extra work. The owner must explain how accurate entries reduce daily conflict. Sales staff get reliable availability. Warehouse staff receive clearer picking instructions. Accounts staff avoid month-end pressure. Management sees cash and margin more clearly.
Training should be role-based. Warehouse staff do not need deep accounting theory, but they must understand SKU labels, godown movement and return classification. Accounts staff must understand settlement reports, ledgers and bank reconciliation. Sales staff must understand stock availability, order status and customer outstanding. Managers must understand review reports.
Training topics by role
- Warehouse: SKU identification, stock movement, return tagging, cycle counts.
- Accounts: voucher posting, marketplace settlement, fees, TCS, TDS, GST data, bank reconciliation.
- Sales: stock availability, order status, credit limits, partial dispatch.
- Purchase: reorder analysis, supplier performance, size and colour movement.
- Management: dashboards, exception reports, margin review, ageing stock.
Short, repeated training is better than one long session. Review errors weekly and correct the process, not just the entry.
Security, Backups and Access Control
Inventory and accounting data is sensitive. If TallyPrime is accessed through a hosted or cloud environment, security must be planned. Businesses should define who can create masters, alter vouchers, view reports, export data and change configurations. Not every user needs full access.
Backups are equally important. A business should have a documented backup routine and should test restoration periodically. A backup that cannot be restored is only a false comfort. If using a service provider, discuss backup frequency, retention, access control and support process. Do not assume; document.
Access discipline also matters when staff leave the company. User access should be reviewed and removed when no longer required. Shared passwords should be avoided. The cost of weak access control can be much higher than the effort required to manage it properly.
Choosing the Right Implementation Partner
For apparel distributors, the right implementation partner should understand both TallyPrime and business reality. A purely technical setup may ignore returns, marketplace settlements and warehouse behavior. A purely accounting setup may ignore SKU discipline and stock locations. The best partner asks questions before configuring.
Questions to ask a Tally partner
- Have you handled inventory setups with size and colour variations?
- How should we structure stock items, groups and godowns?
- Can you help map Amazon settlement reports to TallyPrime ledgers?
- What should be confirmed by our accountant before setup?
- How will returns be recorded from both inventory and accounting perspectives?
- Can you support Tally@Cloud access planning and user permissions?
- How will backups and security be handled?
- Will you train our staff by role?
A good partner will not promise that software alone will solve every issue. They will help create a workable process and make sure the team can follow it.
Implementation Roadmap for Apparel Distributors
A phased roadmap reduces disruption. Trying to fix inventory, marketplace accounting, GST data, cloud access and staff training in one weekend is risky. A better approach is to stabilize the foundation first.
Phase 1: Discovery and cleanup
List current problems, duplicate items, stock locations, sales channels, Amazon report sources, GST concerns and reconciliation gaps. Clean obvious master data errors. Identify who owns each process.
Phase 2: Master design
Define SKU naming, stock groups, categories, godowns, ledgers and voucher workflows. Confirm tax treatment with the accountant. Decide reporting requirements before configuration.
Phase 3: TallyPrime configuration
Configure masters and ledgers according to the approved design. Verify current TallyPrime features and documentation. Test entries for purchase, sale, return, transfer and settlement.
Phase 4: Marketplace workflow
Map Amazon reports to accounting entries. Decide manual, import or integration process. Test one settlement period fully before scaling.
Phase 5: Staff training
Train warehouse, accounts, sales and management separately. Use real business examples. Create written checklists.
Phase 6: Parallel review
Run the improved process for a short period and compare results with old reports. Correct mapping errors and process gaps.
Phase 7: Monthly close discipline
Set weekly and monthly review dates. Use exception reports. Keep accountant review proactive instead of last-minute.
This roadmap is practical because it recognizes that people, data and process must change together.
What Not to Expect From Smart Inventory Software
It is important to avoid unrealistic expectations. Smart inventory software will not automatically fix poor item naming, untrained staff, ignored returns or missing reports. It will not replace accountant advice on tax treatment. It will not make dead stock profitable by itself. It will not prevent errors if users bypass the system.
What it can do is create visibility. It can show where stock is, what sold, what returned, what remains unsettled, which fees were deducted and which balances need attention. It can reduce confusion when used consistently. It can help the owner make decisions with evidence instead of instinct alone.
The best results come when software is treated as an operating system for the business, not just an accounting requirement.
Conclusion
Apparel distribution across Pune MIDC, wholesale markets and Ahmedabad GIDC is full of opportunity, but the opportunity becomes profitable only when records are reliable. Sellers who manage many styles, sizes, colours, locations and channels cannot depend on memory or bank credits alone. Amazon sales must be separated from bank settlements. Returns must be physically and financially tracked. Fees, TCS, TDS and GST-related data must be organized for accountant review. TallyPrime can become a strong foundation when stock masters, ledgers, godowns, vouchers and reconciliation routines are designed carefully and verified against current product documentation and tax guidance.
The practical benefit is simple: fewer surprises, cleaner books, better stock decisions and a calmer month-end. A distributor who knows what is sellable, what is returned, what is damaged, what is pending from Amazon and what is receivable from wholesale buyers can act faster and protect margin.
For help designing a TallyPrime and Tally@Cloud workflow for apparel inventory, marketplace reconciliation and multi-location access, contact Tally@Cloud powered by Binarysoft Technologies, Authorized Tally Partner. Visit or reach us at 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi - 110005, INDIA. Call +91 7428779101, 9205471661 or email tally@binarysoft.com. Contact hours are 10:00 AM - 6:00 PM, Mon-Fri.
FAQ
What is smart inventory software for apparel distributors?
Smart inventory software for apparel distributors is a structured system for tracking stock by style, size, colour, location, sales channel, returns and accounting impact. In a TallyPrime environment, it usually means well-designed stock items, stock groups, godowns, ledgers, vouchers and reconciliation processes rather than only a modern-looking dashboard.
Can TallyPrime manage apparel inventory with sizes and colours?
TallyPrime can be configured for inventory tracking using stock items, groups, categories and godowns, subject to the features available in the current product version. Apparel distributors should verify current TallyPrime documentation or consult an authorized Tally partner to design the best structure for size, colour, style and location tracking.
How should Amazon sales be recorded in TallyPrime?
Amazon sales should be recorded using marketplace reports, not only bank receipts. Sellers should separate gross sales, returns, fees, tax-related entries such as TCS or TDS where applicable, GST-related data and the final settlement amount. The exact voucher and ledger treatment should be confirmed with the accountant.
Why is the Amazon bank settlement not the same as sales?
The bank settlement is usually the net amount received after marketplace deductions, returns, fees and other adjustments. Gross sales, charges, returns and tax-related entries may appear in marketplace reports. Recording only the bank credit as sales can understate revenue and hide expenses or reconciliation issues.
How should apparel returns be handled in inventory?
Returns should first be received into a return location, then quality checked. Sellable items can be moved back to available stock, while damaged, repack-required or disputed items should be tracked separately. This prevents returned goods from being treated as ready stock before inspection.
Do apparel sellers need to verify GST, TCS and TDS details every year?
Yes. Tax rates, thresholds, applicability and filing treatment should be verified with a qualified accountant and current official guidance. Sellers should not rely on old assumptions, especially when dealing with marketplace reports, credit notes, fees and tax-related deductions.
Is Tally@Cloud useful for distributors working across multiple locations?
Tally@Cloud can be useful when authorized users need controlled access to Tally from different locations, such as accounts, warehouse coordination and management review. The setup should include proper user permissions, backup planning, security controls and implementation support.
What is the first step before implementing smart inventory software?
The first step is to clean and standardize master data. Decide SKU naming, stock groups, size and colour structure, godowns, sales channel ledgers and return workflow before importing or automating data. A clear structure makes TallyPrime reports more reliable and easier to reconcile.
Frequently Asked Questions
What is smart inventory software for apparel distributors?
Smart inventory software for apparel distributors is a structured system for tracking stock by style, size, colour, location, sales channel, returns and accounting impact. In a TallyPrime environment, it usually means well-designed stock items, stock groups, godowns, ledgers, vouchers and reconciliation processes rather than only a modern-looking dashboard.
Can TallyPrime manage apparel inventory with sizes and colours?
TallyPrime can be configured for inventory tracking using stock items, groups, categories and godowns, subject to the features available in the current product version. Apparel distributors should verify current TallyPrime documentation or consult an authorized Tally partner to design the best structure for size, colour, style and location tracking.
How should Amazon sales be recorded in TallyPrime?
Amazon sales should be recorded using marketplace reports, not only bank receipts. Sellers should separate gross sales, returns, fees, tax-related entries such as TCS or TDS where applicable, GST-related data and the final settlement amount. The exact voucher and ledger treatment should be confirmed with the accountant.
Why is the Amazon bank settlement not the same as sales?
The bank settlement is usually the net amount received after marketplace deductions, returns, fees and other adjustments. Gross sales, charges, returns and tax-related entries may appear in marketplace reports. Recording only the bank credit as sales can understate revenue and hide expenses or reconciliation issues.
How should apparel returns be handled in inventory?
Returns should first be received into a return location, then quality checked. Sellable items can be moved back to available stock, while damaged, repack-required or disputed items should be tracked separately. This prevents returned goods from being treated as ready stock before inspection.
Do apparel sellers need to verify GST, TCS and TDS details every year?
Yes. Tax rates, thresholds, applicability and filing treatment should be verified with a qualified accountant and current official guidance. Sellers should not rely on old assumptions, especially when dealing with marketplace reports, credit notes, fees and tax-related deductions.
Is Tally@Cloud useful for distributors working across multiple locations?
Tally@Cloud can be useful when authorized users need controlled access to Tally from different locations, such as accounts, warehouse coordination and management review. The setup should include proper user permissions, backup planning, security controls and implementation support.
What is the first step before implementing smart inventory software?
The first step is to clean and standardize master data. Decide SKU naming, stock groups, size and colour structure, godowns, sales channel ledgers and return workflow before importing or automating data. A clear structure makes TallyPrime reports more reliable and easier to reconcile.
CA. Vedant Jhaveri works on GST compliance, accounting systems, and business reporting for growing enterprises. His approach combines accounting discipline with practical workflows suited to everyday business operations.