Call CA Tally HelpDesk
+91 9205471661,
7428779101
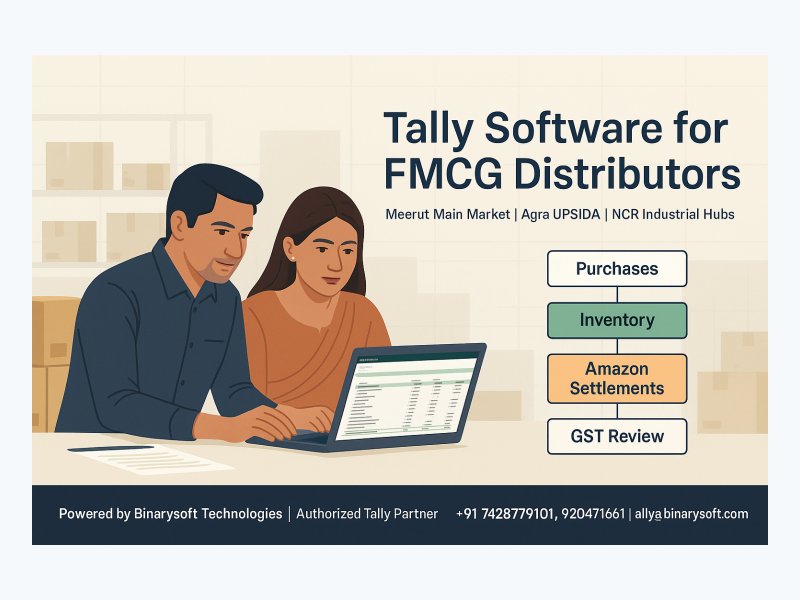
In 2026, the biggest change for FMCG distributors is not one dramatic new tax rule. It is the speed at which buying, selling, returns, payments, marketplace deductions, GST reporting, and stock movement now collide in the same business day. A Meerut Main Market distributor may invoice local retailers in the morning, ship stock to Agra UPSIDA by afternoon, receive Amazon settlement data in the evening, and face supplier payment pressure before the bank closes. When records are maintained only through WhatsApp messages, Excel sheets, and bank entries, profit looks healthy until fees, expired stock, return claims, and tax credits are reconciled. Getting records right in TallyPrime or Tally@Cloud gives sellers a practical benefit: cleaner cash visibility, faster GST review, better stock control, and fewer surprises when accountants, suppliers, banks, or marketplace reports ask for proof.
Suggested URL slug: tally-software-fmcg-distributors-meerut-agra-upsida-industrial-hubs
Why This Guide Matters for FMCG Distributors Across Meerut, Agra UPSIDA and North India Hubs
FMCG distribution is a volume business. The margin on each unit may be small, but the number of transactions is high. A distributor dealing in packaged food, personal care, household cleaning products, cosmetics, beverages, health supplements, stationery consumables, or daily-use items must track purchase bills, sales invoices, schemes, credit notes, stock transfers, batch expiry, damaged goods, retailer claims, marketplace returns, bank receipts, transport payments, and GST data. When the business operates across Meerut Main Market, Agra UPSIDA, Delhi NCR, Ghaziabad, Noida, Sahibabad, Faridabad, Sonipat, Panipat, Aligarh, Mathura, or other industrial belts, the pressure increases because each location may follow a different rhythm of dispatch, payment, and documentation.
TallyPrime remains a familiar accounting and inventory platform for many Indian businesses because it can be configured for day-to-day invoicing, GST-ready records, inventory movement, ledger control, cost tracking, and reporting. Tally@Cloud extends that practical value when owners, accountants, sales teams, warehouses, and branch users need controlled access from different locations. The purpose is not to make accounting fashionable. The purpose is to make business data reliable enough for decisions.
This article is written for distributors, wholesale traders, Amazon sellers, warehouse operators, accountants, and business owners who want a structured way to use Tally software for FMCG operations. It focuses on practical record design, Amazon settlement accounting, GST data discipline, reconciliation mistakes, stock management, and implementation steps. Tax rates, filing rules, thresholds, e-invoicing limits, e-way bill requirements, TDS provisions, TCS treatment, and product-level GST rates change or depend on facts. Confirm those with your accountant, GST consultant, and current TallyPrime product documentation before finalizing entries.
The Business Reality of FMCG Distribution in 2026
FMCG distributors in industrial and commercial hubs do not run a simple buy-and-sell business anymore. Many work through multiple channels at the same time. One invoice may go to a kirana retailer in Meerut Main Market. Another may go to a supermarket chain near Agra. A third dispatch may be a B2B supply to a canteen vendor inside an industrial area. A fourth order may come through Amazon or another marketplace. The same SKU may move through wholesale, retail, institutional, and online channels with different margins, discounts, and return behavior.
The pressure comes from four directions. First, suppliers want faster payments and better secondary sales data. Second, retailers demand credit, replacement, and scheme benefits. Third, marketplaces show sales and deductions in reports that do not look like simple bank receipts. Fourth, GST records must agree with invoices, returns, debit notes, credit notes, and supplier data. If the distributor waits until month end to understand the numbers, the month may already be lost.
In earlier years, many traders could survive with a sales register, purchase register, stock diary, and bank statement. Today, that approach creates gaps. The owner may know total monthly turnover but not know which brand contributes profit after schemes. The accountant may know GST liability but not know which stock is close to expiry. The sales team may promise replacement without checking actual batch availability. The warehouse may dispatch stock but not post the entry on time. The bank may show Amazon money received, but the business may not have recorded commission, shipping fee, refund, reserve amount, TCS, TDS, or GST on marketplace services correctly.
TallyPrime can help when the structure is planned before data entry begins. The software is not a magic shortcut. If ledgers are poorly named, stock items are duplicated, invoices are entered late, and settlement reports are ignored, even the best system becomes a digital version of confusion. But when masters, ledgers, vouchers, inventory settings, user access, and reconciliation routines are designed carefully, Tally becomes the daily control room of the FMCG business.
Meerut Main Market, Agra UPSIDA and the Industrial Hub Challenge
Meerut Main Market is known for dense trading activity, fast movement of goods, distributor networks, and retailer relationships built over years. In such markets, business depends on speed and trust. Sales teams may take orders on phone calls. Retailers may ask for same-day supply. Payment collection may be partly bank transfer, partly cheque, partly cash within legal limits, and partly adjusted against claims. This kind of market rewards businesses that know their outstanding balances clearly.
Agra UPSIDA and surrounding industrial areas bring a different type of activity. Businesses may supply canteens, institutional buyers, factories, worker colonies, retail counters, wholesale agents, and local distributors. Dispatch documentation, gate entry requirements, transport coordination, and GST records become important. If the distributor serves several industrial hubs, every consignment must have supporting documents. The accountant should not be chasing the dispatch team after two weeks to understand which goods actually moved.
Major business hubs across North India add more complexity. Ghaziabad and Sahibabad may involve industrial buyers and wholesale movement. Noida and Greater Noida may include modern retail, ecommerce sellers, and warehouse operations. Delhi markets such as Karol Bagh, Gaffar Market, Sadar Bazaar, Lajpat Rai Market, Okhla, and Naraina may mix traditional trading with online selling. Faridabad, Kundli, Sonipat, Panipat, Aligarh, Mathura, and Bhiwadi may involve different transport lanes, credit cycles, and customer expectations.
The accounting system must reflect this geography. A distributor may create godowns or locations for Meerut, Agra, Delhi warehouse, Amazon FBA or marketplace warehouse if applicable, damaged stock, expired stock, and goods in transit. Cost centres or cost categories may be used to understand branch-wise profitability, sales team performance, route-wise collections, or channel-wise costs, depending on the version and configuration being used. The exact setup should be confirmed with the accountant and TallyPrime documentation.
A common mistake is to treat the whole business as one stock pool and one sales channel. That may work for a very small operation, but it fails when a sales return from Amazon is mixed with a retailer replacement, or when expired stock from one godown is shown as saleable stock at another location. FMCG requires stock clarity because dates, batches, schemes, and margins decide whether the business is earning money or simply moving cartons.
A Clearly Illustrative Story From Karol Bagh and Gaffar Market
Consider an illustrative story, not a real customer case. Ravi is a second-generation trader operating near the Karol Bagh and Gaffar Market belt in Delhi. His father built the business through personal trust. Retailers would call late in the evening, ask for cartons of personal care items, packaged accessories, or household consumables, and someone from the shop would arrange dispatch. Payments were written in a diary. Supplier claims were remembered by the elder brother. Returns were kept in one corner of the shop until there was time to sort them.
For years, this worked because the business was local and relationships were direct. Then Ravi expanded. He started supplying shops in Meerut, sending stock toward Agra industrial buyers, and experimenting with Amazon for selected SKUs. Sales looked exciting. The family saw more orders, more packing, more transport, and more bank messages. But after three months, Ravi felt something was wrong. Bank balance did not match the sales excitement. Suppliers were calling for overdue payments. His younger brother blamed marketplace fees. His father blamed credit sales. The accountant said GST data needed cleaning before filing review.
The emotional pressure was real. Ravi was not careless. He was working twelve hours a day. His wife had started asking why sales were increasing but home cash flow was getting tighter. At the shop, staff members were tired because Amazon returns were arriving without clear mapping to original orders. Some retail customers claimed they had paid through UPI, but the entries were not matched. A few damaged cartons were mixed with saleable goods. Nobody knew whether the problem was low margin, poor collection, excessive returns, or missing records.
When Ravi sat with his accountant, the first discovery was simple but painful. Amazon bank receipts had been entered as sales. That meant the business had not separately recorded gross sales, returns, marketplace fees, shipping deductions, TCS, TDS, or GST on marketplace services. Second, several retailer replacement claims had been adjusted informally without credit notes. Third, two similar SKUs had been created with slightly different names, so stock reports were misleading. Fourth, purchase schemes from suppliers were recorded only when cash discounts appeared, not when free quantity or credit notes were issued.
The solution was not dramatic. Ravi did not need a slogan. He needed discipline. The team redesigned ledgers, standardized stock item names, separated offline wholesale sales from marketplace sales, created a process for returns, mapped bank receipts to settlement reports, and reviewed ageing weekly. The father still trusted relationships, but now the diary was not the only proof. The accountant could explain which money was receivable, which stock was blocked, and which fees reduced marketplace margin. Ravi could finally see that some Amazon SKUs were profitable, some were only creating volume, and some wholesale customers needed tighter credit control.
This story matters because many distributors are in the same emotional space. They are not failing because they do not work hard. They are struggling because the business has become too fast for memory-based accounting. TallyPrime, when used properly, gives such businesses a system where family trust, market speed, and financial discipline can work together.
What TallyPrime Can Do for an FMCG Distributor
TallyPrime can be used to maintain accounting, inventory, invoicing, tax-related records, receivables, payables, bank reconciliation, stock reports, and management views. Depending on the edition, license, configuration, add-ons, and current product capabilities, it may also support features related to GST, e-way bill, e-invoicing, batch details, cost centres, multiple godowns, price levels, voucher classes, security controls, and data synchronization or connected services. Because features evolve, businesses should verify current availability with official Tally documentation or an authorized Tally partner.
For FMCG distributors, the practical value begins with master design. The master list includes ledgers, stock groups, stock items, units of measure, godowns, GST classifications where applicable, customer groups, supplier groups, expense ledgers, marketplace ledgers, tax ledgers, discount ledgers, and bank ledgers. If masters are clean, daily entries become easier. If masters are messy, every report becomes doubtful.
A distributor can organize customers by area, route, channel, or sales representative. For example, customer groups may include Meerut retailers, Agra institutional buyers, Delhi wholesale, NCR modern trade, Amazon customers or marketplace sales, and inter-branch transfers. Suppliers may be grouped by brand, manufacturer, super stockist, packaging vendor, logistics vendor, and marketplace service provider. This helps the owner see not just total sales, but the nature of sales.
Inventory can be structured through stock groups such as packaged food, beverages, personal care, household cleaning, cosmetics, baby care, health and wellness, stationery consumables, seasonal packs, and promotional bundles. Stock categories or additional classification may be used where suitable. Stock items should have consistent naming. A good naming format may include brand, product name, size, pack type, and variant. For example, a 500 ml floor cleaner variant should not appear in three different names because one entry used ml, another used millilitre, and another used bottle.
Batch and expiry tracking is especially important in FMCG. Many products lose value as expiry approaches. Some buyers refuse short-expiry stock. Some suppliers accept expiry claims only within a defined process. Some marketplaces may restrict saleable stock based on shelf-life requirements. TallyPrime configuration can help track batch-wise stock where enabled and correctly used. Businesses should train warehouse staff to enter batch details at purchase and dispatch, not later by guesswork.
Multiple godowns or locations are useful when stock is physically stored at different places. A distributor may maintain a Delhi warehouse, Meerut godown, Agra dispatch point, damaged goods location, expired stock location, promotional stock location, and marketplace or FBA location if relevant. Goods movement between these locations should be recorded through stock transfer or appropriate inventory vouchers as advised by the accountant. Without this, stock shown in books may be physically unavailable for dispatch.
Receivables control is another major benefit. FMCG distributors often sell on credit. Retailers may pay weekly, fortnightly, or after the next purchase. Institutional buyers may take longer. If the owner checks only total outstanding, collection discipline weakens. Tally reports can help review party-wise ageing, overdue amounts, bill-wise tracking, and payment history. The business can then decide whether to hold further supply, reduce credit limit, collect old dues, or adjust claims properly.
Tally@Cloud for Owners, Accountants and Branch Teams
Tally@Cloud is useful when the business wants Tally access from multiple locations without depending only on one office computer. A distributor may have an owner in Delhi, an accountant in Karol Bagh, a warehouse in Meerut, a dispatch coordinator serving Agra UPSIDA, and a consultant reviewing data remotely. Cloud access can reduce delays, provided user roles, backups, passwords, device security, and data ownership are handled properly.
The important point is that cloud hosting does not change accounting principles. If the Amazon settlement is wrongly entered, cloud access will only make the wrong entry visible faster. If stock items are duplicated, cloud access will not automatically clean them. The benefit of Tally@Cloud comes when a well-designed TallyPrime system is made available to the right people at the right time with controlled permissions.
For example, the sales coordinator may be allowed to create sales orders or view stock, while the accountant posts tax-sensitive entries. The warehouse operator may record dispatch or stock transfer under supervision. The owner may view outstanding, stock summary, cash flow, and profitability reports. The auditor or GST consultant may access data during review hours instead of waiting for backup files. The exact access structure should be planned based on internal control and current Tally and hosting capabilities.
Cloud access also helps businesses that operate across busy markets. A distributor cannot always bring the accountant to Meerut, Agra, Delhi, Noida, and Ghaziabad physically. But if records are updated daily, the accountant can identify missing purchase bills, unmatched bank receipts, negative stock, unadjusted credit notes, or pending marketplace settlements earlier. Early correction is cheaper than year-end correction.
Designing the Chart of Accounts for FMCG Operations
The chart of accounts should match the way the business earns and spends money. A generic ledger list may be enough for a small shop, but a distributor handling wholesale, industrial supply, and Amazon sales needs more clarity. The goal is not to create hundreds of unnecessary ledgers. The goal is to separate items that require different treatment, review, or reconciliation.
Sales ledgers may be organized by channel, such as local wholesale sales, Meerut retail distribution, Agra UPSIDA institutional sales, NCR industrial supply, modern trade sales, Amazon marketplace sales, and export or interstate sales if applicable. GST treatment, place of supply, invoice format, and reporting requirements should be reviewed with the accountant.
Purchase ledgers may be grouped by taxable purchases, exempt purchases if any, packaging purchases, promotional material, purchase returns, supplier claims, and inward freight where applicable. The business should confirm whether freight, discounts, and schemes are part of purchase cost or treated separately according to accounting policy and tax advice.
Expense ledgers should separate ordinary operating expenses from marketplace deductions. For example, rent, salaries, transport, loading, packaging, bank charges, electricity, internet, sales promotion, and local delivery should not be mixed with Amazon commission, shipping fee, closing fee, storage fee, advertising fee, refund administration charge, or other marketplace charges. Marketplace fee names should be based on current reports and accountant guidance.
Tax ledgers should be created carefully. GST output, GST input, reverse charge if applicable, TCS, TDS, and other tax-related ledgers should follow professional advice. Do not create random tax ledgers simply because a report has a deduction column. The accountant must decide whether the amount is tax collected, tax deducted, expense, receivable, payable, or adjustment.
Customer and supplier ledgers should use consistent names, GSTIN details where applicable, addresses, state, contact numbers, credit terms, and bill-wise tracking. For Amazon and other marketplaces, businesses often require separate ledgers for marketplace receivable, marketplace fees payable or expenses, TCS receivable, TDS receivable, and settlement clearing. The exact structure may vary, but the principle remains: gross sales and deductions must be visible separately.
Bank and payment ledgers should include each bank account separately. UPI collections, payment gateway receipts, cheque deposits, cash, and marketplace settlements should be traceable. If multiple staff members collect money, the business may use collection control accounts or cost centres, subject to accountant advice. Avoid entering unidentified receipts directly against sales without party mapping.
Inventory Master Setup for FMCG: The Foundation of Profit Control
Inventory master design is where many FMCG distributors either win or lose control. When stock items are created casually, the same product appears under multiple names. When units are unclear, cartons and pieces are confused. When batch numbers are skipped, expired and fresh stock merge. When schemes are not recorded properly, margin reports mislead the owner.
A practical stock item naming format should be written down and followed by everyone. For example, the format can be brand name, product description, variant, size, pack count, and unit. If the product is a 100 gram pack sold in a carton of 48, the business should decide how it wants to maintain primary and alternate units. TallyPrime supports unit configuration, but the right method depends on purchase pattern, sales pattern, and reporting needs.
FMCG businesses should also define stock groups before entering thousands of items. A useful structure may include food and snacks, beverages, personal care, cosmetics, home care, cleaning products, health products, baby products, pet products, paper goods, seasonal products, promotional packs, and damaged or expired stock. Some businesses may prefer brand-wise grouping. Others may prefer category-wise grouping. The best approach is the one that helps purchasing, sales, and profitability review.
Batch-wise details help with expiry control. If enabled, every purchase should capture batch number, manufacturing date or expiry date where required, and quantity. Every sale should reduce the correct batch. If the warehouse dispatches first-expiry stock first but the accounting entry uses a different batch, reports become unreliable. Staff training is essential because batch discipline is operational, not just accounting.
Godown setup should reflect physical movement. A common design may include main warehouse, branch warehouse, van stock, damaged stock, expired stock, sample stock, promotional stock, goods in transit, and marketplace warehouse where relevant. Stock transferred from Delhi to Meerut should not remain visible as Delhi saleable stock. Goods sent to Amazon fulfillment, if applicable, should be tracked separately based on marketplace reports and physical movement documents.
Price levels and rate controls may be useful for distributors selling to retailers, wholesalers, institutions, and online channels at different rates. However, price controls should not replace review. FMCG prices change due to MRP revision, supplier schemes, festive offers, near-expiry liquidation, and competitor pressure. Any automated price list must be maintained regularly.
Sales, Schemes, Credit Notes and Claims
FMCG sales rarely happen at plain list price. Distributors deal with cash discounts, turnover schemes, free quantity, quantity discounts, festival schemes, retailer incentives, display support, damage claims, expiry claims, and rate difference claims. If these are handled outside Tally, the profit and outstanding reports become incomplete.
Suppose a Meerut retailer buys 100 cartons of a packaged product and receives 5 cartons free under a supplier-backed scheme. The distributor must decide how to record the free quantity, purchase support, and sale value in consultation with the accountant. If the free goods are simply dispatched without entry, stock becomes short. If the scheme is recorded only as discount but not quantity, margin may be wrong. If supplier reimbursement is expected but not tracked, receivables from supplier may be forgotten.
Credit notes are equally important. When a retailer returns damaged goods, the entry should show which party returned the goods, what quantity came back, whether it is saleable, damaged, or expired, and whether GST credit note treatment is applicable. The accountant should confirm documentation requirements and time limits as per current law. Never treat every return as a simple cash adjustment.
Rate difference claims occur when a supplier reduces price or supports a distributor after stock is already billed. These claims should be tracked separately so the owner knows what is recoverable. Without a ledger or report, such claims remain in emails and WhatsApp chats. At year end, nobody remembers them accurately.
Retailer incentives and sales team incentives should also be recorded transparently. If a salesman offers additional discount without approval, the margin drops. If the discount is approved but not entered correctly, the customer ledger may show a dispute. Good Tally configuration cannot replace management approval, but it can make unauthorized leakage visible.
GST Data Discipline Without Guesswork
GST reporting for FMCG distributors depends on accurate invoice data, correct party details, correct product classification, proper tax ledgers, purchase reconciliation, credit notes, debit notes, and timely review. This article does not provide tax rates, filing thresholds, e-invoice limits, e-way bill rules, TCS or TDS applicability, or return deadlines because these must be verified from current law, official portals, and your accountant. Product-level GST classification should also be confirmed carefully because FMCG categories can vary by composition, packaging, and notification.
In TallyPrime, businesses usually maintain GST-ready records by entering GSTIN, state, registration type, taxability, HSN or SAC details where applicable, place of supply, and correct tax ledgers. The exact screens and options should be checked in the current product version. The discipline is simple: do not postpone GST fields until filing day. If invoice data is incomplete at entry time, the accountant must spend extra time cleaning it later.
Purchase reconciliation is critical. Input tax credit depends on correct supplier invoices and matching with available data as per current GST process. Businesses should regularly review supplier bills, missing GSTIN, wrong invoice numbers, wrong dates, duplicate bills, and credit notes. If supplier data is not appearing as expected, the distributor should follow up early. Waiting until the filing deadline creates stress.
Sales returns and credit notes must be handled carefully. FMCG returns may arise because of damage, expiry, wrong dispatch, pricing dispute, customer refusal, or marketplace refund. Each reason may have different accounting and tax implications. The accountant should confirm whether and how a GST credit note is to be issued, what time limits apply, and how it affects returns.
For interstate movement, e-way bill requirements may apply depending on value, product, state rules, and movement type. For e-invoicing, applicability may depend on turnover and notified rules. Do not rely on old thresholds. Confirm current requirements before configuring Tally or dispatching goods.
Amazon Sales Are Not the Same as Bank Receipts
One of the most important lessons for FMCG distributors selling on Amazon is this: the amount received in the bank is not the sale amount. The bank receipt is a net settlement. It may include customer payments collected by Amazon, refunds, commission, shipping fees, closing fees, storage or fulfillment charges, advertising charges, GST on marketplace services, TCS, TDS, reimbursements, reserves, previous period adjustments, and other deductions or credits. If the distributor enters only the bank receipt as sales, the books will be incomplete.
Marketplace reports and bank receipts serve different purposes. Marketplace reports show the business activity behind the settlement. Bank receipts show cash movement. TallyPrime should be used to record the accounting impact of both. The gross sale belongs in sales records. Returns should be recorded as sales returns or credit notes as advised. Marketplace fees should be recorded as expenses. Tax withheld or collected should be recorded in appropriate tax receivable ledgers if applicable. The final bank receipt should clear the marketplace receivable or settlement account.
For Amazon, sellers should download and preserve order reports, settlement reports, tax reports, return reports, fee reports, advertising reports, reimbursement reports, inventory reports, and TCS or TDS certificates as applicable. Report names and formats may change, so sellers should check the current Amazon Seller Central reports. The accountant should define which report is the primary source for sales, which report supports fees, and which report supports tax credits or claims.
A practical Tally structure may include ledgers such as Amazon Marketplace Receivable, Amazon Sales, Amazon Sales Return, Amazon Commission, Amazon Shipping Fee, Amazon Closing Fee, Amazon Advertising Expense, Amazon GST on Fees, Amazon TCS Receivable, Amazon TDS Receivable, Amazon Reimbursement, Amazon Reserve or Settlement Clearing, and Amazon Bank Settlement. The final names may differ, but the separation is important.
FMCG sellers should also understand the difference between fulfilled by merchant, fulfilled by marketplace, and other fulfillment models where applicable. Stock movement, fee structure, storage charges, return handling, customer refunds, and reimbursement treatment may differ. Do not assume that every Amazon transaction follows the same entry pattern. Discuss the workflow with your accountant and verify with current marketplace reports.
How to Organize Amazon Data in TallyPrime
The first step is to decide the accounting period for posting Amazon data. Some sellers post each order separately. That gives maximum detail but may be time-consuming for high-volume sellers. Some post daily summaries. Some post settlement-wise entries. The right method depends on invoice generation, GST reporting needs, volume, return frequency, and accountant preference. Whatever method is chosen, the business should be able to trace totals from Amazon reports to Tally entries and then to bank receipts.
Step one: capture gross sales. Gross sales should come from order or tax reports, not from bank credit. The entry should reflect sales value, applicable GST treatment, customer or marketplace structure, and invoice requirements. If invoices are generated outside Tally, the accountant should decide whether to import or summarize them. If invoices are generated in Tally, order data must be entered or integrated accurately.
Step two: capture returns and refunds. Amazon returns may happen in the same settlement period or later. The returned item may be saleable, damaged, used, lost, or reimbursed. The accounting entry should not simply reduce cash. It should show sales return, stock impact where applicable, GST credit note treatment if applicable, and claim or reimbursement if applicable. Confirm the correct treatment with the accountant.
Step three: record marketplace fees. Amazon fees are business expenses and should be classified according to report type. Commission, shipping fee, closing fee, storage fee, fulfillment fee, advertisement, refund fee, technology fee, or other charges should not all be dumped into one ledger if management needs margin clarity. At minimum, separate major recurring fee categories so the owner can see whether online sales are profitable.
Step four: record GST on marketplace services. Marketplace invoices for fees may include GST on services. Whether and how input tax credit is available depends on law, eligibility, documentation, and the nature of expense. Do not assume. Record the data based on valid tax invoices and accountant guidance.
Step five: record TCS and TDS separately. Marketplaces may collect or deduct amounts under tax provisions as applicable. These are not ordinary expenses. They may be receivable or adjustable subject to legal rules, portal data, certificates, and accountant review. Treating TCS or TDS as commission expense is a common mistake that distorts profit and tax receivable balances.
Step six: reconcile the settlement. The Amazon settlement report should explain how gross sales and credits minus refunds, fees, taxes, reserves, and adjustments arrive at the net amount paid to the bank. In Tally, a settlement clearing account can help. The bank receipt should be matched against the settlement amount, not treated as new sales.
Step seven: reconcile with bank. Bank reconciliation confirms whether the net settlement amount actually arrived. It does not prove that sales and fees are correctly recorded. Both reconciliations are required: marketplace report to Tally, and Tally to bank.
Step eight: preserve reports. Download reports regularly and store them period-wise. Marketplace portals may change report formats or availability. A disciplined folder structure by month, settlement number, and report type saves time during audit, GST review, or internal analysis.
Illustrative Amazon Settlement Example
Assume an FMCG distributor sells selected personal care packs through Amazon. During a settlement cycle, marketplace reports show gross customer invoices of ₹1,00,000. Returns and refunds are ₹12,000. Marketplace fees are ₹9,500 plus applicable tax as per marketplace invoice. TCS and TDS appear in separate report columns. A small reimbursement for a lost item is also shown. The net amount credited to the bank is ₹74,800. These figures are illustrative only and not a tax calculation.
If the distributor records ₹74,800 as sales, several things go wrong. Sales are understated. Returns are invisible. Marketplace fees are missing. TCS and TDS are not tracked. GST on marketplace fees may not be reviewed. Reimbursement is mixed with sales. Profitability analysis becomes impossible. The owner may think Amazon margin is higher or lower than reality because the deductions are hidden inside the bank receipt.
A better approach is to post gross sales, returns, fees, tax components, receivables, reimbursement, and settlement clearing separately. Then the bank receipt clears the net settlement balance. At month end, the Amazon Marketplace Receivable or Settlement Clearing ledger should not carry unexplained balances. If it does, the accountant should identify whether the reason is reserve, pending settlement, mismatch, missing fee entry, refund timing, or bank delay.
This example also applies to other marketplaces. The names of reports and deductions may differ, but the principle remains the same. Gross business activity must be separated from net cash received.
Common Reconciliation Mistakes FMCG Sellers Make
Mistake one: entering bank receipts as sales. This is the most common error in Amazon accounting. It hides deductions and makes GST and profit reports unreliable.
Mistake two: posting settlement reports twice. Some sellers enter individual orders and then also enter settlement sales summaries, creating duplicate sales. Decide one method and reconcile carefully.
Mistake three: ignoring returns. FMCG returns may come later, may be damaged, or may be reimbursed. If returns are ignored, stock and sales remain wrong.
Mistake four: treating TCS and TDS as expenses. These amounts should be reviewed separately because they may be creditable or adjustable subject to rules and records. Confirm with the accountant.
Mistake five: mixing Amazon fees with general bank charges. Marketplace fees are channel-specific costs. If they are mixed with bank charges, online profitability cannot be measured.
Mistake six: not matching settlement period with invoice period. Sales may happen in one period and settlement may arrive in another. Month-end closing must account for pending receivables and later refunds.
Mistake seven: ignoring reserve balances. Marketplaces may hold amounts for future claims or settlement timing. If reserve movements are not tracked, clearing ledgers remain confusing.
Mistake eight: not reconciling GST reports with Tally data. Marketplace tax reports, sales invoices, credit notes, and Tally entries should be reviewed together. Do not assume the bank settlement proves tax correctness.
Mistake nine: using one stock item for multiple variants. Different pack sizes, variants, or bundles should be tracked properly. Otherwise Amazon returns may not match stock.
Mistake ten: failing to record damaged or expired returns separately. Returned stock is not always saleable. FMCG businesses must separate saleable, damaged, expired, and claimable stock.
Wholesale and Industrial Supply Example for Meerut and Agra
Imagine a distributor receives an order from a Meerut retailer for mixed cartons of household cleaning products. The invoice includes regular items, a quantity discount, and one promotional display pack. The sales team promises replacement for any damaged units reported within an agreed period. The correct Tally workflow should capture the customer, item-wise quantity, rate, discount, batch if applicable, GST details, dispatch location, and credit terms. If the retailer later returns damaged stock, a separate entry should record the return and stock condition.
Now consider an Agra UPSIDA institutional buyer ordering monthly consumables for a factory canteen and housekeeping department. The buyer may require a purchase order reference, delivery challan, invoice, e-way bill if applicable, and payment after approval. If the distributor does not record order reference and dispatch details, payment follow-up becomes slow. In Tally, the business can maintain party ledgers, bill-wise tracking, references, and outstanding reports so the sales and accounts teams speak from the same data.
The difference between these two examples is operational, but the accounting principle is the same. Every sale must create a reliable trail from order to invoice, stock reduction, dispatch, receipt, payment, and claim adjustment. Tally software supports this discipline when the business uses it daily rather than treating it as a month-end typing tool.
Daily, Weekly and Monthly Workflow for FMCG Distributors
A practical workflow prevents accounting from piling up. Daily discipline is more valuable than a heroic month-end cleanup. The following structure can be adapted to business size.
Daily workflow
- Enter purchase bills received with correct supplier, invoice number, date, GST details, item quantity, batch, and godown.
- Record sales invoices, delivery challans, or sales orders as per the business process.
- Update stock transfers between Delhi, Meerut, Agra, warehouse, damaged stock, and marketplace locations.
- Post collections against customer bills instead of entering vague receipts.
- Download or note marketplace settlement activity if a settlement is due.
- Check negative stock, unusual rate differences, and missing batch details.
- Record expenses such as transport, loading, packaging, and local delivery with proper references.
Weekly workflow
- Review party-wise outstanding and overdue balances.
- Compare physical fast-moving stock with Tally stock summary.
- Review near-expiry stock and plan liquidation or supplier claim action.
- Reconcile Amazon and marketplace settlements received during the week.
- Check supplier claims, rate difference claims, and pending credit notes.
- Review sales by channel, area, and salesperson if cost centres or reports are configured.
- Back up data and verify that cloud access and user permissions are functioning correctly.
Monthly workflow
- Reconcile bank accounts, UPI receipts, cheques, and marketplace settlements.
- Review GST data with the accountant before filing decisions.
- Match supplier invoices and credit notes with available GST data as per current process.
- Review Amazon TCS, TDS, fee invoices, reimbursements, and pending reserves.
- Check inventory valuation, damaged stock, expired stock, and slow-moving stock.
- Review gross margin by product category, brand, area, and channel where data is available.
- Close unexplained balances in clearing accounts before they become old.
Useful Checklist Before Implementing Tally for FMCG Distribution
- Define locations: List every warehouse, branch, market office, van stock point, damaged stock area, expired stock area, and marketplace stock location.
- Standardize stock names: Decide a naming format for brand, product, variant, size, pack, and unit.
- Confirm units: Decide how pieces, cartons, boxes, cases, strips, kilograms, litres, and alternate units will be used.
- Plan batch tracking: Identify which products require batch and expiry tracking and train staff accordingly.
- Clean customer ledgers: Capture GSTIN, address, state, phone, credit period, route, and salesperson where needed.
- Separate channels: Keep wholesale, retail, institutional, modern trade, and marketplace sales distinguishable.
- Create marketplace ledgers: Separate Amazon sales, returns, fees, taxes, TCS, TDS, reimbursement, and settlement clearing.
- Verify GST setup: Confirm HSN, taxability, registration details, and reporting needs with the accountant.
- Decide voucher workflow: Choose how sales orders, delivery challans, invoices, credit notes, debit notes, and receipts will flow.
- Set user permissions: Give staff only the access they need. Protect alteration rights for sensitive entries.
- Schedule reconciliation: Fix daily, weekly, and monthly review tasks with named responsibility.
- Plan backups: Maintain secure backups and test restore procedures periodically.
Security, Controls and User Rights in Tally@Cloud
Cloud access increases convenience, but it also requires discipline. Every user should have a separate login where possible. Passwords should not be shared casually. Staff who only need to enter dispatch data should not have unrestricted rights to alter tax ledgers or delete vouchers. Owners should review user rights periodically, especially when employees change roles or leave the organization.
Data backup is non-negotiable. Businesses should maintain a backup policy that covers frequency, storage location, restoration testing, and responsibility. A backup that has never been tested may fail when it is needed most. Ask your Tally partner or IT provider about backup options, security practices, and data recovery process.
Cloud performance also depends on internet quality, hosting configuration, number of users, data size, and working habits. A distributor with high invoice volume should discuss expected usage before choosing a hosting plan. The goal is stable access for accountants, owners, and operational users without compromising data safety.
Internal controls should be built into daily work. For example, sales returns above a certain value may require approval. Rate changes may require owner confirmation. Old outstanding balances may trigger a credit hold. Stock adjustment entries should be reviewed. Marketplace settlement entries should be posted by trained staff and checked by the accountant. Tally reports can support these controls, but management must enforce them.
Reports Every FMCG Distributor Should Review
Stock summary: Shows quantity and value of stock. Review category-wise and godown-wise where configured.
Batch and expiry reports: Help identify near-expiry stock, expired stock, and batch availability. Confirm report availability and setup in the current TallyPrime version.
Outstanding receivables: Shows party-wise dues. Use bill-wise ageing to focus collection efforts.
Payables: Helps plan supplier payments and avoid supply disruption.
Sales register: Shows sales by period, ledger, item, and party depending on configuration.
Purchase register: Helps reconcile supplier bills and input tax data.
Gross profit or margin reports: Useful if purchase cost, sales price, schemes, and stock valuation are recorded correctly.
Bank reconciliation: Confirms whether book balances match bank statement movements.
Marketplace settlement report in Tally: If designed through ledgers and clearing accounts, it helps compare Amazon reports with accounting entries.
GST-related reports: Used for review before filing. Always verify with accountant and current law.
How Tally Helps Owners Make Better Decisions
Good accounting is not only for tax filing. It helps the owner answer everyday business questions. Which market gives better collection? Which brand has high sales but low profit? Which salesperson brings orders that do not pay on time? Which Amazon SKU creates returns? Which supplier gives schemes that are actually received? Which product is near expiry? Which customer has crossed the credit limit? Which warehouse is showing unexplained shortage?
When records are accurate, the owner can make decisions earlier. A distributor may stop pushing a high-volume Amazon product if fees and returns remove profit. Another may increase focus on Agra industrial buyers because payment is slower but margin is stable. Another may reduce credit in Meerut for customers who delay beyond agreed terms. Another may negotiate better supplier schemes after showing clean sales data.
TallyPrime reports become powerful only when entries are timely and structured. If purchase bills are entered late, stock reports are wrong. If returns are not posted, sales are inflated. If Amazon fees are hidden, channel profitability is false. If customer receipts are posted without bill references, ageing reports lose value. Decision-making begins with data discipline.
Implementation Roadmap for a Distributor Moving to Tally or Tally@Cloud
Phase one: business mapping. List locations, products, channels, suppliers, customers, sales process, purchase process, return process, marketplace process, GST review process, and reporting needs. This prevents random configuration.
Phase two: master cleanup. Clean customer, supplier, item, unit, godown, tax, expense, bank, and marketplace ledgers. Remove duplicates. Standardize names. Confirm opening balances.
Phase three: inventory setup. Configure stock groups, units, godowns, batch details, expiry tracking, and valuation method as advised. Verify with sample entries before importing or entering large data.
Phase four: voucher process. Decide how orders, challans, invoices, returns, credit notes, debit notes, receipts, payments, stock transfers, and journal entries will be used. Train staff with real examples.
Phase five: Amazon process. Select the reporting method, create settlement ledgers, define entry format, reconcile a sample settlement, and document the steps. Do not wait until many settlements are pending.
Phase six: cloud access and controls. Set up Tally@Cloud access, users, roles, passwords, backup process, and support contact. Test performance and access from required locations.
Phase seven: parallel review. For the first month, compare Tally reports with physical stock, bank statements, Amazon reports, and accountant review. Correct configuration issues early.
Phase eight: management reporting. Once entries are stable, create routine reports for outstanding, stock ageing, sales by channel, marketplace profitability, GST review, and cash flow planning.
What Not to Expect From Tally Software
Tally software can organize records, but it cannot fix unclear business rules. If the sales team gives unauthorized discounts, the software can reveal the loss but cannot prevent it unless approval controls exist. If warehouse staff dispatch without documents, Tally cannot create accurate stock automatically. If Amazon reports are not downloaded, Tally cannot guess settlement details. If the accountant is not consulted on GST treatment, entries may still be wrong.
Do not expect any software to guarantee tax compliance, profit growth, or zero errors. Compliance depends on correct configuration, valid documents, updated legal understanding, timely filing, and professional review. Profit depends on pricing, purchasing, credit control, stock rotation, claims, returns, and market strategy. Tally is a strong business tool, but it works best when paired with disciplined people and clear processes.
Practical Tips for Better FMCG Control
- Do not create new stock items without checking whether the item already exists.
- Use batch and expiry tracking for products where shelf life matters.
- Separate saleable, damaged, expired, and claimable stock.
- Review outstanding every week, not only when cash is short.
- Record Amazon sales from marketplace reports, not from bank receipts alone.
- Keep TCS and TDS ledgers separate and reconcile them with certificates and portal data as advised.
- Reconcile settlement clearing accounts after every payout cycle.
- Match physical stock with Tally stock for fast-moving and high-value products regularly.
- Train staff before giving them access to live company data.
- Keep backups and test restore procedures.
Choosing the Right Tally Partner
A good Tally partner should understand both software and business workflow. FMCG distribution is not only about installing TallyPrime. It is about configuring inventory, GST data, batch tracking, godowns, credit control, marketplace accounting, user rights, cloud access, backup, and reports in a way that matches the distributor's reality. The partner should ask questions about your products, channels, warehouses, Amazon reports, customer credit, and accountant's requirements before suggesting a setup.
For businesses across Meerut Main Market, Agra UPSIDA, Karol Bagh, Gaffar Market, Delhi NCR, and other industrial hubs, local understanding also matters. Market practices, transport patterns, staff skills, and documentation habits affect implementation. A practical partner helps simplify the system so the team can actually use it daily.
Natural Closing Call to Action
If you are an FMCG distributor, wholesaler, Amazon seller, or industrial supplier looking to organize TallyPrime or Tally@Cloud for inventory, GST-ready accounting, Amazon settlement reconciliation, and branch access, you can speak with Binarysoft Technologies for guided setup and support.
Powered by Binarysoft Technologies
Authorized Tally Partner
Address: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi - 110005, INDIA
Phone: +91 7428779101, 9205471661
Email: tally@binarysoft.com
Contact hours: 10:00 AM - 6:00 PM, Mon-Fri
Conclusion
FMCG distribution across Meerut Main Market, Agra UPSIDA and major industrial hubs is becoming faster, more data-heavy, and more competitive. The businesses that survive are not necessarily those with the most orders. They are the ones that know which orders are profitable, which customers pay on time, which stock is saleable, which marketplace deductions are reducing margins, and which records need accountant review before deadlines.
TallyPrime and Tally@Cloud can provide a strong foundation for this control when implemented thoughtfully. The key is to separate marketplace reports from bank receipts, maintain clean inventory masters, track batches and expiry, reconcile Amazon sales and fees, review GST data without guesswork, and create daily accounting discipline. Software alone does not create discipline, but the right Tally setup makes discipline easier to follow.
For an FMCG distributor, accurate records are not paperwork. They are working capital protection, profit visibility, tax preparedness, and peace of mind. Whether your business operates from Delhi, Meerut, Agra, NCR, or multiple industrial routes, the time to clean the system is before confusion becomes costly.
FAQ
Is TallyPrime suitable for FMCG distributors in Meerut Main Market and Agra UPSIDA?
Yes, TallyPrime can be suitable for FMCG distributors when configured correctly for inventory, GST-ready records, batch details, godowns, receivables, payables, and channel-wise reporting. The setup should reflect your actual business process, including wholesale sales, institutional supply, branch movement, damaged stock, expiry tracking, and marketplace transactions. Confirm current product features and configuration options with an authorized Tally partner.
How should Amazon sales be entered in TallyPrime?
Amazon sales should not be entered only from the bank amount received. Sellers should use marketplace reports to capture gross sales, returns, fees, GST on marketplace services where applicable, TCS, TDS, reimbursements, reserves, and settlement adjustments. The bank receipt should then be matched against the net settlement. Your accountant should decide whether entries are posted order-wise, daily, or settlement-wise.
What is the difference between an Amazon settlement report and a bank receipt?
An Amazon settlement report explains the business activity behind a payout, including sales, refunds, marketplace charges, tax deductions or collections, reimbursements, reserves, and adjustments. A bank receipt only shows the net cash received. Treating bank receipts as sales hides deductions and may distort GST review, profit reporting, and tax receivable tracking.
Can Tally@Cloud help if my accountant, warehouse and owner work from different locations?
Yes, Tally@Cloud can help teams access Tally from different locations with controlled permissions, subject to hosting setup, internet quality, user rights, and security practices. It is useful for distributors operating across Delhi, Meerut, Agra, NCR and industrial hubs. However, cloud access does not replace proper accounting design, staff training, backups, and reconciliation routines.
Should FMCG distributors use batch and expiry tracking in Tally?
For many FMCG products, batch and expiry tracking is very useful because it helps identify near-expiry stock, expired goods, supplier claims, and saleable inventory. It is especially important for food, health, personal care, cosmetics, and other shelf-life-sensitive products. The exact configuration should be tested with sample entries and aligned with warehouse discipline.
How often should marketplace settlements be reconciled?
Marketplace settlements should ideally be reconciled after every payout cycle and reviewed again at month end. High-volume sellers may need daily or weekly review. The reconciliation should match Amazon reports with Tally entries and then match the net settlement with the bank statement. Unexplained balances in clearing ledgers should be investigated early.
Can Tally calculate GST correctly for all FMCG items automatically?
Tally can help maintain GST-ready records when masters, tax ledgers, product details, party details, and voucher entries are configured properly. However, product classification, tax rates, input credit eligibility, filing rules, e-invoicing, e-way bill requirements, TCS, and TDS treatment must be verified with current law, official sources, and your accountant. Do not rely on old assumptions.
What should I prepare before implementing Tally for an FMCG distribution business?
Prepare a clean list of customers, suppliers, products, units, godowns, opening stock, outstanding balances, bank accounts, tax details, sales channels, Amazon reports, and business workflows. Decide how purchases, sales, returns, credit notes, stock transfers, collections, and marketplace settlements will be entered. A structured implementation saves time and reduces errors later.
Frequently Asked Questions
Is TallyPrime suitable for FMCG distributors in Meerut Main Market and Agra UPSIDA?
Yes, TallyPrime can be suitable for FMCG distributors when configured correctly for inventory, GST-ready records, batch details, godowns, receivables, payables, and channel-wise reporting. The setup should reflect your actual business process, including wholesale sales, institutional supply, branch movement, damaged stock, expiry tracking, and marketplace transactions. Confirm current product features and configuration options with an authorized Tally partner.
How should Amazon sales be entered in TallyPrime?
Amazon sales should not be entered only from the bank amount received. Sellers should use marketplace reports to capture gross sales, returns, fees, GST on marketplace services where applicable, TCS, TDS, reimbursements, reserves, and settlement adjustments. The bank receipt should then be matched against the net settlement. Your accountant should decide whether entries are posted order-wise, daily, or settlement-wise.
What is the difference between an Amazon settlement report and a bank receipt?
An Amazon settlement report explains the business activity behind a payout, including sales, refunds, marketplace charges, tax deductions or collections, reimbursements, reserves, and adjustments. A bank receipt only shows the net cash received. Treating bank receipts as sales hides deductions and may distort GST review, profit reporting, and tax receivable tracking.
Can Tally@Cloud help if my accountant, warehouse and owner work from different locations?
Yes, Tally@Cloud can help teams access Tally from different locations with controlled permissions, subject to hosting setup, internet quality, user rights, and security practices. It is useful for distributors operating across Delhi, Meerut, Agra, NCR and industrial hubs. However, cloud access does not replace proper accounting design, staff training, backups, and reconciliation routines.
Should FMCG distributors use batch and expiry tracking in Tally?
For many FMCG products, batch and expiry tracking is very useful because it helps identify near-expiry stock, expired goods, supplier claims, and saleable inventory. It is especially important for food, health, personal care, cosmetics, and other shelf-life-sensitive products. The exact configuration should be tested with sample entries and aligned with warehouse discipline.
How often should marketplace settlements be reconciled?
Marketplace settlements should ideally be reconciled after every payout cycle and reviewed again at month end. High-volume sellers may need daily or weekly review. The reconciliation should match Amazon reports with Tally entries and then match the net settlement with the bank statement. Unexplained balances in clearing ledgers should be investigated early.
Can Tally calculate GST correctly for all FMCG items automatically?
Tally can help maintain GST-ready records when masters, tax ledgers, product details, party details, and voucher entries are configured properly. However, product classification, tax rates, input credit eligibility, filing rules, e-invoicing, e-way bill requirements, TCS, and TDS treatment must be verified with current law, official sources, and your accountant. Do not rely on old assumptions.
What should I prepare before implementing Tally for an FMCG distribution business?
Prepare a clean list of customers, suppliers, products, units, godowns, opening stock, outstanding balances, bank accounts, tax details, sales channels, Amazon reports, and business workflows. Decide how purchases, sales, returns, credit notes, stock transfers, collections, and marketplace settlements will be entered. A structured implementation saves time and reduces errors later.
CA. Mayankh Singhaal is a Chartered Accountant experienced in accounting systems, statutory audits, and compliance advisory. He has worked with businesses across different sectors to improve reporting accuracy and inventory tracking. His writing focuses on structured growth and compliance-ready operations.