Call CA Tally HelpDesk
+91 9205471661,
7428779101
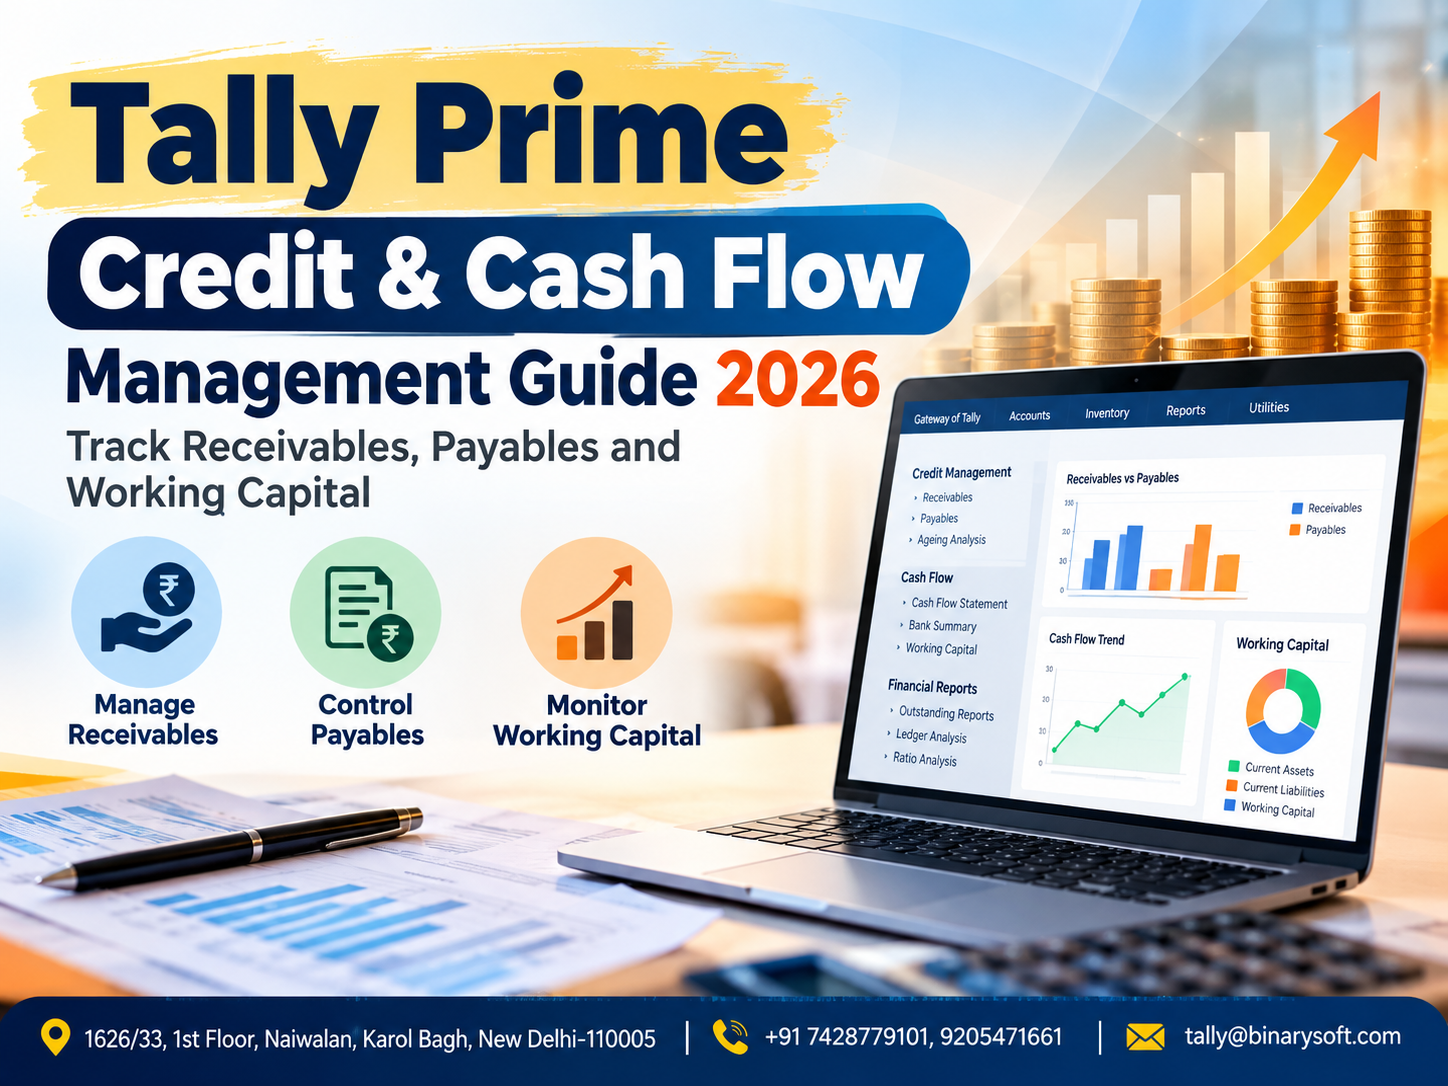
Introduction: Why Credit and Cash Flow Management Have Become Critical for Indian Businesses in 2026
In 2026, Indian businesses are facing increasing pressure to manage customer credit, delayed payments, supplier obligations, rising inventory costs, and unpredictable cash requirements. A company may report strong monthly sales yet struggle to pay suppliers, salaries, rent, or taxes because a large portion of its revenue remains locked in unpaid invoices. For retailers, wholesalers, distributors, manufacturers, and service providers, understanding the difference between sales, profit, and available cash has become essential for financial stability.
TallyPrime provides integrated accounting capabilities that help businesses monitor receivables, track payables, maintain bill-wise outstanding records, reconcile bank transactions, and review cash flow information. When combined with disciplined collection procedures and accurate transaction recording, these features can improve financial visibility and support better working capital decisions.
This Tally Prime Credit and Cash Flow Management Guide 2026 explains how businesses can use TallyPrime to strengthen credit control, reduce payment delays, manage financial commitments, and support sustainable growth.
1. Understanding Credit and Cash Flow Management in TallyPrime
Credit and cash flow management are two closely connected areas of business finance.
Credit management focuses on controlling money owed by customers and managing payment obligations to suppliers.
Cash flow management focuses on understanding the movement of money into and out of a business.
A profitable business may still experience financial difficulties when customer collections are delayed or significant funds remain invested in inventory.
TallyPrime provides accounting and reporting features that help businesses maintain relevant financial records and analyze their position.
Important Components of Credit and Cash Flow Management
-
Accounts receivable
-
Accounts payable
-
Customer credit periods
-
Supplier payment terms
-
Bill-wise outstanding balances
-
Customer payment collections
-
Supplier payment planning
-
Cash and bank balances
-
Bank reconciliation
-
Inventory investment
-
Working capital requirements
-
Financial reporting
-
Cash flow analysis
These components help business owners understand how much money is expected from customers, how much must be paid to suppliers, and whether sufficient funds are available for upcoming obligations.
2. A Business Story: Strong Sales but Not Enough Cash
Consider the illustrative story of Rakesh, a wholesale electrical goods distributor operating in Delhi.
Rakesh started his business with a small rented shop and gradually developed relationships with retailers, contractors, and commercial customers.
Over twelve years, his business expanded into electrical cables, switches, lighting products, and industrial accessories.
His sales team regularly reported growing monthly revenue.
Customers were placing larger orders, and suppliers were offering additional product lines.
From the outside, the business appeared successful.
However, Rakesh began experiencing an uncomfortable financial problem.
Every month, he struggled to arrange sufficient money for supplier payments.
His customers were purchasing goods on credit, but many payments were arriving later than expected.
One afternoon, a major supplier informed him that future deliveries could be delayed unless an outstanding invoice was cleared.
Rakesh checked his bank balance and realized that he could not immediately arrange the required amount.
He felt frustrated and worried.
His warehouse contained valuable inventory, and his sales records showed substantial business activity, yet his available cash was insufficient.
When he reviewed his customer accounts, he discovered that several invoices had remained unpaid for more than sixty days.
Some customers had made partial payments, but the receipts had not been allocated correctly against individual invoices.
His accounting team was recording transactions, but outstanding balances were not being reviewed systematically.
Rakesh decided to improve his credit management process using TallyPrime.
He introduced bill-wise accounting, reviewed customer outstanding reports every week, monitored supplier due dates, and began examining cash and bank balances before making major purchase commitments.
His team also started contacting customers before payment due dates rather than waiting until invoices became significantly overdue.
Over time, the business developed better collection discipline and clearer financial visibility.
The lesson from Rakesh's experience is important: increasing sales does not automatically create financial security. A business must convert sales into timely collections while managing inventory and payment obligations responsibly.
3. What Is Accounts Receivable Management?
Accounts receivable represents money owed to a business by customers for goods or services supplied on credit.
For example, when a wholesaler sells goods worth ₹1,00,000 and allows the customer to pay after thirty days, the amount becomes a receivable until it is collected or otherwise settled.
Receivable management involves monitoring these balances and ensuring that customers pay according to agreed terms.
Why Receivable Management Matters
Delayed collections can affect:
TallyPrime supports customer ledger management, bill-wise accounting, and outstanding receivables reports that help businesses review these obligations.
4. Customer Ledger Management in TallyPrime
Customer ledgers provide the foundation for receivable tracking.
Each customer can be maintained under an appropriate accounting group, such as Sundry Debtors, according to the business's accounting structure.
Important Customer Ledger Information
-
Customer name
-
Address and contact details
-
GST registration information, where applicable
-
Opening balance
-
Credit period
-
Credit limit, where configured
-
Recorded sales transactions
-
Receipts and adjustments
-
Closing balance
Practical Example
A distributor creates a customer ledger for ABC Electronics.
The customer purchases goods worth ₹80,000 on credit.
The transaction is recorded through a sales voucher.
When ABC Electronics pays ₹50,000, the receipt is recorded and allocated appropriately.
Remaining outstanding balance: ₹30,000.
The business can review the ledger and relevant outstanding reports to identify the unpaid amount.
5. Bill-Wise Accounting for Accurate Customer Outstanding Tracking
Bill-wise accounting is one of the most useful features for businesses dealing with credit transactions.
It allows receivables and payables to be tracked against individual invoices.
Without bill-wise details, a business may know the total customer balance but struggle to identify which invoices remain unpaid.
Example
A customer receives three invoices:
| Invoice | Amount | Payment Status |
|---|
| INV-101 |
₹40,000 |
Fully paid |
| INV-102 |
₹65,000 |
Partially paid |
| INV-103 |
₹95,000 |
Unpaid |
Suppose ₹25,000 has been received against INV-102.
The remaining balance on that invoice is ₹40,000.
Total outstanding across these invoices:
₹40,000 + ₹95,000 = ₹1,35,000.
With correct bill-wise allocation, TallyPrime can help the business identify the individual unpaid invoices rather than relying only on a consolidated ledger balance.
6. Credit Period Management
A credit period is the agreed time allowed to a customer for payment.
Common commercial credit periods include:
-
7 days
-
15 days
-
30 days
-
45 days
-
60 days
The appropriate period depends on customer relationships, industry practices, financial risk, and business policy.
TallyPrime supports relevant credit-period information and bill-wise due-date tracking.
Practical Example
A wholesaler sells goods worth ₹1,50,000 on 1 October 2026 with a thirty-day credit period.
The agreed payment due date is calculated according to the applicable terms.
The business can use outstanding reports to monitor the amount and follow up when necessary.
Benefits
Improved collection planning: Identify invoices approaching their due dates.
Better customer communication: Remind customers about agreed payment terms.
Reduced overdue exposure: Review delayed payments before they accumulate.
More disciplined credit decisions: Consider payment history before extending additional credit.
7. Customer Credit Limits in TallyPrime
A credit limit represents the maximum amount of credit a business is willing to extend to a customer.
For example, a distributor may approve a credit limit of ₹2,00,000 for a regular retailer.
If the customer's outstanding balance reaches ₹1,80,000, management may review whether additional credit should be approved.
TallyPrime provides credit-related controls and information, subject to the relevant configuration and transaction workflow.
Why Credit Limits Are Important
Credit limits can help businesses:
-
Control exposure to individual customers
-
Reduce excessive outstanding balances
-
Encourage timely collections
-
Establish consistent credit policies
-
Improve financial discipline
However, credit limits should not be treated as a guarantee of payment.
Businesses should also evaluate customer payment history, financial reliability, and commercial circumstances.
8. Outstanding Receivables Reports
Outstanding receivables reports help businesses review amounts owed by customers.
These reports are especially useful for wholesalers, distributors, manufacturers, and service providers.
Important Information to Review
Example
| Customer | Outstanding Amount | Days Overdue |
|---|
| Customer A |
₹75,000 |
10 |
| Customer B |
₹1,20,000 |
25 |
| Customer C |
₹90,000 |
45 |
| Customer D |
₹65,000 |
60 |
Total outstanding: ₹3,50,000.
The business can prioritize collection efforts based on overdue periods, amounts, customer relationships, and credit risk.
This helps the accounts team move from reactive collection to a more structured process.
9. Receivables Ageing Analysis
Receivables ageing classifies outstanding customer balances according to how long they have remained unpaid or overdue, depending on the report configuration.
A common management approach is to divide receivables into ageing groups.
Illustrative Receivables Ageing Report
| Ageing Category | Outstanding Amount |
|---|
| 0–30 days |
₹2,50,000 |
| 31–60 days |
₹1,75,000 |
| 61–90 days |
₹95,000 |
| More than 90 days |
₹80,000 |
| Total |
₹6,00,000 |
This example shows that ₹1,75,000 is outstanding in the categories above sixty days.
Management may decide to prioritize these balances for review.
Benefits of Ageing Analysis
-
Identify long-overdue invoices
-
Prioritize customer follow-up
-
Review credit exposure
-
Detect collection problems
-
Support cash flow planning
-
Evaluate potential doubtful debts
Ageing analysis becomes more useful when the business maintains accurate invoice dates, due dates, and receipt allocations.
10. Understanding Accounts Payable Management
Accounts payable represents money owed by a business to suppliers and other creditors.
When a distributor purchases goods on credit, the amount becomes payable until it is settled.
Payable management involves recording supplier invoices, tracking due dates, and planning payments.
Why Payable Management Matters
Late supplier payments may lead to:
At the same time, paying suppliers unnecessarily early may reduce cash available for other business needs.
A balanced payable management process helps businesses maintain supplier relationships while protecting liquidity.
11. Supplier Ledger and Bill-Wise Payables
TallyPrime supports supplier ledger management and bill-wise payable tracking.
Practical Example
A business purchases electronic components from three suppliers.
| Supplier | Amount Payable | Due Period |
|---|
| Supplier A |
₹1,80,000 |
15 days |
| Supplier B |
₹2,40,000 |
30 days |
| Supplier C |
₹95,000 |
45 days |
Total supplier payables: ₹5,15,000.
The business can review payable reports and plan payments according to agreed terms and available funds.
Benefits
-
Better supplier payment planning
-
Reduced risk of missed due dates
-
Improved purchase accounting
-
More accurate liability reporting
-
Better working capital visibility
12. Planning Supplier Payments Without Creating Cash Shortages
Businesses should evaluate upcoming payment obligations before committing to additional purchases or expenses.
Example
A wholesaler expects:
Customer collections next week: ₹4,00,000
Supplier payments due: ₹3,20,000
Salaries and operating expenses: ₹1,10,000
Total expected outflows: ₹4,30,000.
Expected collections alone would be insufficient by ₹30,000.
However, the actual cash position also depends on opening cash and bank balances, other inflows, and additional obligations.
This example demonstrates why businesses should consider both expected collections and scheduled payments.
TallyPrime provides relevant accounting information that can support this planning process.
13. Cash Flow Management in TallyPrime
Cash flow management involves monitoring cash inflows and outflows.
Cash Inflows May Include
-
Customer collections
-
Cash sales
-
Loan proceeds
-
Capital contributions
-
Interest receipts
-
Other business receipts
Cash Outflows May Include
-
Supplier payments
-
Salaries
-
Rent
-
Utility expenses
-
Loan repayments
-
Tax payments
-
Equipment purchases
-
Other operating expenses
TallyPrime provides cash, bank, and financial reports that help businesses understand recorded cash movements.
Important Distinction
Accounting profit and cash flow are not the same.
A business may report a profit while holding substantial receivables or inventory.
Likewise, receiving a loan may increase cash without increasing operating profit.
Understanding this difference is essential for sound financial management.
14. Cash Flow Statement in TallyPrime
A cash flow statement helps explain changes in cash and cash equivalents over a reporting period.
Depending on the accounting requirements and reporting framework, cash flows may be analyzed under operating, investing, and financing activities.
Operating Activities
Cash movements related to normal business operations.
Examples include customer collections and supplier payments.
Investing Activities
Cash movements related to relevant investments and long-term assets.
Examples include purchasing equipment or disposing of certain assets.
Financing Activities
Cash movements related to financing arrangements.
Examples include borrowing funds, repaying loan principal, or receiving capital contributions.
TallyPrime provides cash flow reporting capabilities that help users examine financial movements based on recorded transactions.
Businesses should review the relevant report structure and accounting treatment for their reporting requirements.
15. Cash Flow Forecasting Using Accounting Information
Cash flow forecasting estimates future cash inflows and outflows.
A forecast helps businesses identify potential funding gaps before they occur.
TallyPrime provides accounting data that can support cash flow forecasting.
However, detailed forward-looking forecasts may require management assumptions, spreadsheet models, or additional planning tools.
Illustrative Monthly Cash Flow Forecast
| Particulars | Amount |
|---|
| Opening cash and bank balance |
₹3,00,000 |
| Expected customer collections |
₹8,00,000 |
| Other expected receipts |
₹50,000 |
| Total cash available |
₹11,50,000 |
| Expected supplier payments |
₹6,00,000 |
| Salaries and operating expenses |
₹2,00,000 |
| Taxes and other payments |
₹1,00,000 |
| Total expected outflows |
₹9,00,000 |
| Forecast closing cash balance |
₹2,50,000 |
The forecast should be updated when payment expectations or business conditions change.
16. Bank Reconciliation for Accurate Cash Balances
Bank reconciliation compares transactions recorded in accounting books with transactions reflected in bank statements.
It helps identify missing entries, timing differences, and other discrepancies.
TallyPrime supports bank reconciliation functionality, with additional features depending on the installed release and supported banking arrangements.
Common Reconciliation Differences
-
Bank charges
-
Interest credits
-
Unpresented cheques
-
Deposits awaiting clearance
-
Incorrect transaction amounts
-
Duplicate entries
-
Missing bank transactions
Example
Book balance: ₹4,50,000
Bank statement balance: ₹4,48,500
Unrecorded bank charges: ₹1,500
After recording the charges correctly, the book balance becomes ₹4,48,500.
Regular reconciliation improves the reliability of cash and bank information.
17. Working Capital Management in TallyPrime
Working capital represents the difference between current assets and current liabilities.
Formula
Working Capital = Current Assets – Current Liabilities
Current assets may include:
-
Cash and bank balances
-
Accounts receivable
-
Inventory
-
Other current assets
Current liabilities may include:
Practical Example
A distributor has:
Current assets: ₹25,00,000
Current liabilities: ₹17,00,000
Working capital:
₹25,00,000 – ₹17,00,000 = ₹8,00,000
This indicates positive working capital of ₹8 lakh.
However, positive working capital does not automatically mean that sufficient cash is available.
A large portion of current assets may consist of slow-moving inventory or overdue receivables.
18. Working Capital Ratio Analysis
Financial ratios help businesses evaluate liquidity and operational efficiency.
Current Ratio
The current ratio compares current assets with current liabilities.
Current Ratio = Current Assets ÷ Current Liabilities
Example:
Current assets = ₹24 lakh
Current liabilities = ₹16 lakh
Current ratio = 1.5.
The ratio indicates that the business has ₹1.50 of current assets for every ₹1 of current liabilities.
Whether this is adequate depends on the industry, cash conversion cycle, asset quality, and business circumstances.
Quick Ratio
The quick ratio focuses on more liquid current assets.
A common simplified formula is:
Quick Ratio = (Current Assets – Inventory – Prepaid Expenses) ÷ Current Liabilities
This ratio can help assess liquidity without relying on inventory conversion.
TallyPrime financial statements can provide inputs for calculating these ratios.
19. Inventory and Its Impact on Cash Flow
Inventory is an important part of working capital.
Businesses invest money in products before receiving cash from customers.
Excess inventory can create financial pressure, especially when products remain unsold for long periods.
Example
An electronics distributor purchases inventory worth ₹15 lakh.
Only ₹9 lakh of that inventory is sold during the expected period, measured at its relevant cost.
The remaining ₹6 lakh continues to be invested in unsold stock.
If customer payments are also delayed, the business may face additional cash pressure.
How TallyPrime Helps
TallyPrime provides inventory records and reports that can help businesses review:
-
Stock quantities
-
Inventory values
-
Stock movement
-
Stock ageing
-
Product groups
-
Warehouse-wise balances
-
Reorder requirements
Businesses can use this information to improve purchasing decisions and reduce unnecessary inventory accumulation.
20. Understanding the Cash Conversion Cycle
The cash conversion cycle measures the approximate time required to convert investment in inventory and receivables into cash, after considering supplier payment periods.
Formula
Cash Conversion Cycle = Days Inventory Outstanding + Days Sales Outstanding – Days Payable Outstanding
Example
Days Inventory Outstanding: 45 days
Days Sales Outstanding: 35 days
Days Payable Outstanding: 30 days
Cash conversion cycle:
45 + 35 – 30 = 50 days.
This indicates an illustrative fifty-day cash conversion cycle.
A shorter cycle may reduce working capital requirements, although the appropriate target depends on the business model.
TallyPrime can provide transaction and financial data needed for calculating relevant measures.
21. Days Sales Outstanding and Collection Efficiency
Days Sales Outstanding, or DSO, is a measure of how long a business takes to collect receivables.
A common formula is:
DSO = (Average Accounts Receivable ÷ Net Credit Sales) × Number of Days
Example
Average receivables: ₹5,00,000
Net credit sales during a 30-day period: ₹10,00,000
DSO:
(₹5,00,000 ÷ ₹10,00,000) × 30 = 15 days.
This indicates an illustrative collection period of fifteen days.
Businesses can monitor DSO over time to understand whether collection efficiency is improving or deteriorating.
Accurate credit sales and receivable information are essential for meaningful calculations.
22. Days Payable Outstanding and Supplier Credit
Days Payable Outstanding, or DPO, measures the approximate time a business takes to pay suppliers.
A common formula is:
DPO = (Average Accounts Payable ÷ Cost of Goods Sold) × Number of Days
Example
Average accounts payable: ₹4,00,000
Cost of goods sold during a 30-day period: ₹8,00,000
DPO:
(₹4,00,000 ÷ ₹8,00,000) × 30 = 15 days.
Businesses should interpret DPO carefully.
A longer payment period may support liquidity, but excessive delays can damage supplier relationships or create additional costs.
23. Credit Notes and Debit Notes in Credit Management
Credit notes and debit notes help businesses record appropriate transaction adjustments.
Credit Notes
A credit note may be used for eligible sales returns, price reductions, or other relevant adjustments.
Debit Notes
A debit note may be used for applicable purchase-related adjustments or other accounting circumstances.
Example
A customer purchases goods worth ₹1,00,000 before tax.
Goods worth ₹10,000 before tax are subsequently returned.
The business may need to record an appropriate sales return or credit note with the relevant GST treatment.
Correct adjustment entries help maintain accurate customer balances.
24. Payment Follow-Up and Collection Discipline
Accounting software provides information, but collection discipline requires action.
Businesses should establish a structured payment follow-up process.
Suggested Collection Schedule
Before the due date: Review invoices approaching maturity.
On the due date: Verify whether payment has been received.
Seven days overdue: Contact the customer and request an expected payment date.
Fifteen days overdue: Escalate according to the company's credit policy.
Thirty days overdue: Review further credit exposure and possible management intervention.
These are illustrative internal procedures, not statutory deadlines.
The appropriate approach should reflect customer relationships, agreed terms, and applicable legal requirements.
Benefits
-
More consistent collections
-
Better customer communication
-
Reduced overdue balances
-
Improved cash flow planning
-
Clearer credit accountability
25. Customer Credit Risk Assessment
Not all customers present the same credit risk.
Businesses should consider several factors before approving significant credit sales.
Important Factors
TallyPrime can provide relevant accounting records, but a comprehensive credit assessment may require additional information.
Example
Customer A regularly pays within fifteen days.
Customer B frequently pays after sixty days.
If both request the same credit limit, management may decide to apply different credit terms based on their payment histories and risk assessments.
This supports more disciplined credit decisions.
26. Managing Supplier Relationships Through Better Payable Planning
Supplier relationships are important for business continuity.
A distributor that regularly delays payments may experience reduced credit availability or supply disruptions.
Recommended Practices
-
Record supplier invoices promptly
-
Maintain accurate due dates
-
Review payable reports regularly
-
Communicate expected payment schedules
-
Avoid unnecessary payment disputes
-
Reconcile supplier statements
-
Monitor available cash before large purchases
TallyPrime supports the accounting records needed for these activities.
However, maintaining supplier trust also requires clear communication and honoring agreed payment terms.
27. Financial Reports That Support Credit and Cash Flow Decisions
TallyPrime provides several reports that can support credit management.
Outstanding Receivables
Review amounts due from customers.
Outstanding Payables
Review amounts owed to suppliers.
Cash Flow Report
Examine relevant cash movements.
Cash and Bank Books
Review recorded cash and bank transactions.
Balance Sheet
Understand assets, liabilities, and financial position.
Profit and Loss Account
Evaluate income, expenses, and profitability.
Sales Register
Review sales transactions.
Purchase Register
Review purchase transactions.
Stock Summary
Understand recorded inventory quantities and values.
These reports provide different perspectives on financial performance and liquidity.
28. How TallyPrime Supports Retailers, Wholesalers and Distributors
Retail Businesses
Retailers can use TallyPrime to monitor daily sales, cash receipts, supplier balances, and inventory investment.
Wholesale Businesses
Wholesalers can manage customer credit, supplier payments, bill-wise outstanding balances, and cash flow information.
Distribution Businesses
Distributors can review receivables, payables, inventory values, and relevant financial reports across their operations.
Manufacturing Businesses
Manufacturers can use accounting and inventory information to evaluate raw material investment, supplier obligations, and customer collections.
Service Businesses
Service providers can track invoices, customer payments, operating expenses, and cash balances.
Each business should configure its accounting processes according to its specific requirements.
29. Common Credit and Cash Flow Management Mistakes
Businesses should avoid several common mistakes.
Confusing Sales with Cash
Credit sales increase receivables but do not immediately increase available cash.
Ignoring Overdue Invoices
Delayed follow-up can allow receivables to accumulate.
Incorrect Receipt Allocation
Payments applied to the wrong invoices can create misleading outstanding reports.
Excessive Customer Credit
Extending credit without suitable limits can increase financial risk.
Paying Suppliers Without Planning
Poor payment scheduling may create unnecessary cash shortages.
Holding Excess Inventory
Unsold products tie up working capital.
Ignoring Bank Reconciliation
Unrecorded transactions can distort cash balances.
Failing to Prepare Forecasts
Businesses may overlook upcoming funding gaps.
Not Reviewing Financial Reports
Accounting data provides limited value when management does not analyze it.
Avoiding these mistakes can improve financial discipline and business resilience.
30. Best Practices for Credit and Cash Flow Management in 2026
Maintain Accurate Ledgers
Create and update customer and supplier records consistently.
Use Bill-Wise Accounting
Track individual invoices and allocate payments correctly.
Review Receivables Weekly
Identify overdue balances and prioritize collections.
Monitor Supplier Due Dates
Plan payments according to obligations and available funds.
Reconcile Bank Accounts
Maintain reliable cash and bank information.
Prepare Cash Flow Forecasts
Estimate future receipts and payments.
Review Inventory Investment
Identify slow-moving or excess stock.
Establish Credit Policies
Define customer credit limits and payment terms.
Monitor Working Capital Ratios
Review liquidity and operating efficiency.
Maintain Secure Backups
Protect accounting records through regular backup and restoration testing.
Train Accounting Employees
Ensure employees understand credit, payment allocation, and reporting procedures.
31. Credit and Cash Flow Management: Manual Methods vs TallyPrime
| Business Activity | Manual Management | TallyPrime |
|---|
| Customer balances |
Registers or spreadsheets |
Customer ledgers |
| Invoice tracking |
Manual follow-up |
Bill-wise accounting |
| Receivables ageing |
Manual calculation |
Outstanding and ageing analysis |
| Supplier balances |
Separate records |
Supplier ledgers |
| Payment planning |
Manual lists |
Payable reports |
| Bank reconciliation |
Manual comparison |
Reconciliation functionality |
| Cash reporting |
Manual consolidation |
Cash and bank reports |
| Financial statements |
Manual preparation |
Built-in reports |
| Inventory valuation |
Manual calculations |
Inventory reporting |
| Credit monitoring |
Separate tracking |
Credit-related ledger controls and reports |
| Working capital analysis |
Spreadsheet calculations |
Accounting data for financial analysis |
TallyPrime can simplify the recording and review of financial information, but successful credit control depends on business policies and management action.
32. How Binarysoft Technologies Can Help with TallyPrime Credit and Cash Flow Management
Effective credit and cash flow management requires accurate accounting configuration and consistent financial review.
Binarysoft Technologies Pvt. Ltd., an Authorized Tally Partner based in Karol Bagh, New Delhi, can be contacted for TallyPrime-related assistance and guidance.
Areas of Assistance
Customer ledger configuration: Organizing customer accounts and relevant credit information.
Supplier ledger management: Setting up appropriate payable records.
Bill-wise accounting: Understanding invoice-wise receivable and payable tracking.
Outstanding reports: Reviewing customer and supplier balances.
Bank reconciliation: Guidance on available banking features.
Financial reporting: Understanding cash flow, Profit and Loss, and Balance Sheet information.
Inventory-related accounting: Reviewing how inventory affects business financial records.
TallyPrime training: Helping employees understand relevant accounting workflows.
Businesses should discuss their operational requirements and confirm the scope of any proposed services before implementation.
33. Practical Credit and Cash Flow Management Checklist
| Area | Recommended Action | Business Benefit |
|---|
| Customer credit |
Define suitable credit terms |
Controlled exposure |
| Receivables |
Review outstanding invoices |
Better collection planning |
| Bill-wise accounting |
Allocate receipts correctly |
Accurate balances |
| Credit limits |
Review customer exposure |
Reduced credit risk |
| Payables |
Track supplier due dates |
Better payment planning |
| Bank reconciliation |
Reconcile regularly |
Reliable cash balances |
| Cash flow |
Monitor receipts and payments |
Better liquidity visibility |
| Forecasting |
Prepare future cash estimates |
Early identification of funding gaps |
| Inventory |
Review stock investment |
Improved working capital |
| Financial reports |
Review monthly |
Better management decisions |
| Backups |
Maintain verified copies |
Data protection |
| Employee training |
Standardize procedures |
Improved accounting accuracy |
Conclusion: Strengthen Financial Stability with Better Credit and Cash Flow Management
Credit and cash flow management are essential for businesses that want to maintain financial stability, protect supplier relationships, and support long-term growth.
In 2026, Indian retailers, wholesalers, distributors, manufacturers, and service providers must pay closer attention to customer receivables, supplier obligations, inventory investment, and available cash.
TallyPrime provides integrated accounting features that help businesses maintain customer and supplier ledgers, track bill-wise outstanding balances, review receivables and payables, reconcile bank transactions, and analyze financial information.
These capabilities can improve visibility into business finances and support more disciplined decision-making.
However, accounting software alone cannot eliminate delayed payments or cash shortages.
Businesses must establish suitable credit policies, follow up on overdue invoices, plan supplier payments, control inventory investment, and regularly review financial reports.
The most effective approach combines accurate accounting records with responsible financial management.
With appropriate TallyPrime configuration, employee training, and regular review procedures, businesses can strengthen working capital control, improve collection efficiency, and build a more resilient financial foundation.
Powered by Binarysoft Technologies
Authorized Tally Partner
Location: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact Us: +91 7428779101, 9205471661
Email: tally@binarysoft.com
Business Hours: 10:00 AM – 6:00 PM, Monday to Friday
Frequently Asked Questions
What is credit management in TallyPrime?
Credit management in TallyPrime involves maintaining customer and supplier ledgers, recording credit transactions, tracking bill-wise outstanding balances, and reviewing relevant credit information.
How does TallyPrime help manage cash flow?
TallyPrime provides cash, bank, receivable, payable, and financial reports that help businesses understand recorded cash movements and financial obligations.
Can TallyPrime track customer outstanding payments?
es. TallyPrime supports customer ledgers, bill-wise accounting, and outstanding receivables reports.
Does TallyPrime support supplier payable management?
Yes. Businesses can maintain supplier ledgers, record purchase transactions, and review outstanding payable reports.
CA. Vedant Jhaveri works on GST compliance, accounting systems, and business reporting for growing enterprises. His approach combines accounting discipline with practical workflows suited to everyday business operations.