Call CA Tally HelpDesk
+91 9205471661,
7428779101
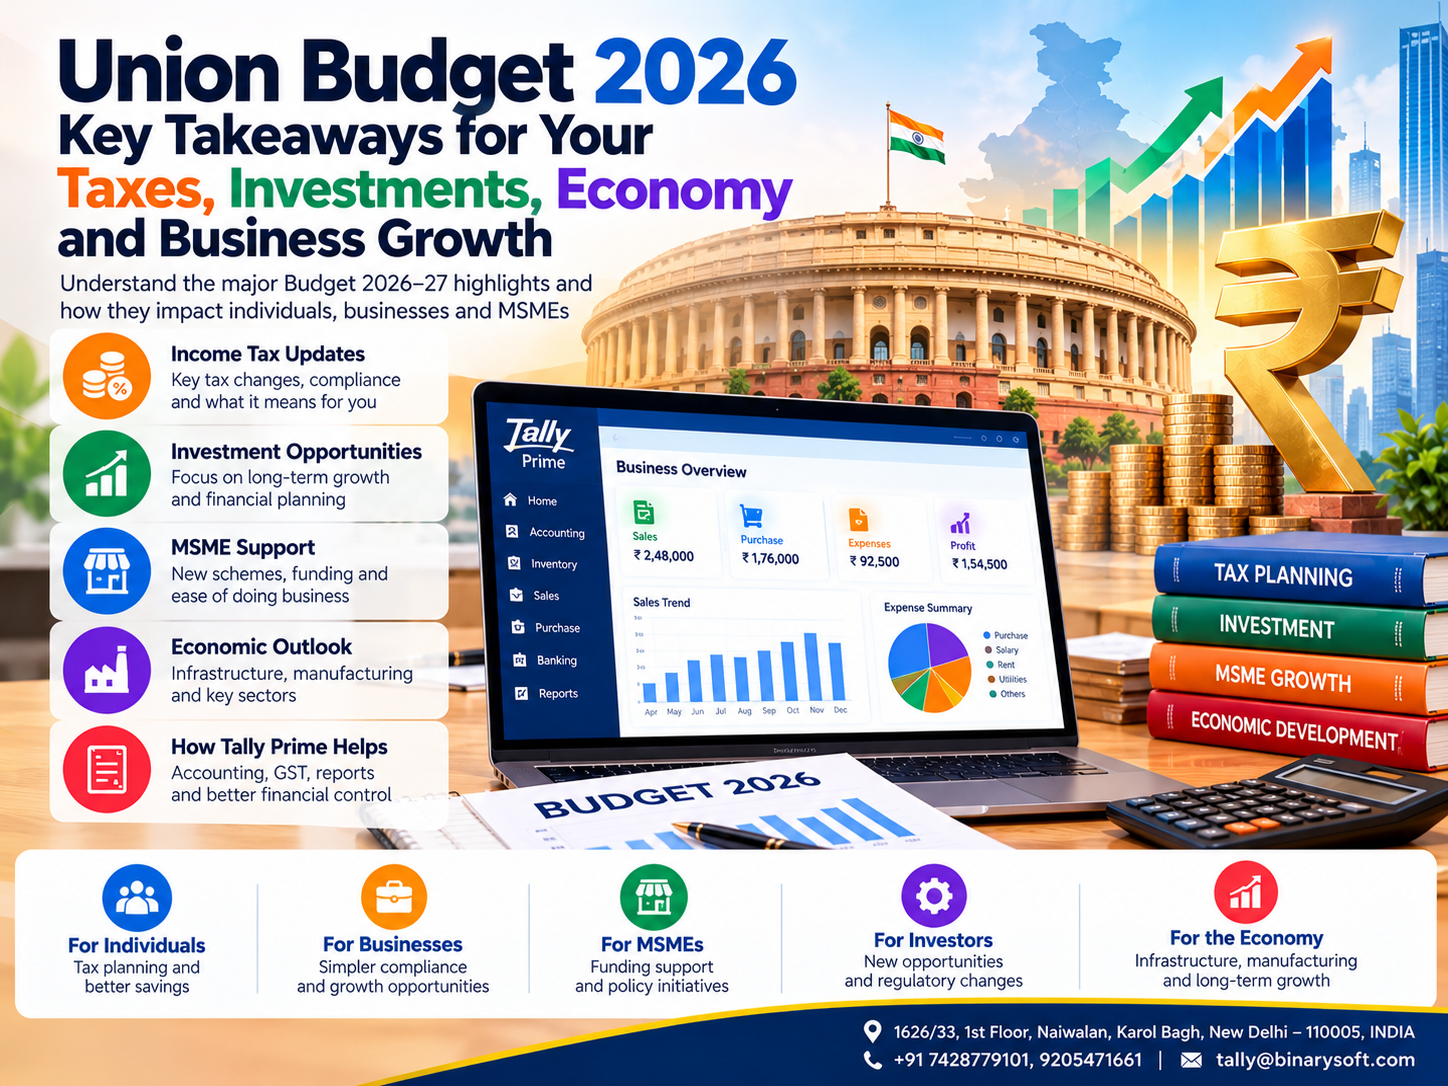
Introduction: How Union Budget 2026 Is Reshaping Financial Decisions for Indian Businesses
For millions of Indian families and business owners, the Union Budget is more than an annual government announcement. It influences household savings, business investments, taxation, employment opportunities and long-term financial planning.
Union Budget 2026–27, presented on 1 February 2026, placed significant emphasis on economic growth, manufacturing, infrastructure development, MSME support and tax administration reforms.
Rather than announcing another broad revision of individual income tax slabs, the Budget focused on simplifying compliance, strengthening investment opportunities and improving the environment for businesses.
The introduction of the Income Tax Act, 2025 from April 2026 represents an important change in the direct-tax framework. Meanwhile, proposed measures for MSME financing, public infrastructure and selected industries aim to support economic activity.
For small businesses, the central question is practical: how can these changes improve cash flow, reduce compliance difficulties and create opportunities for growth?
This guide explains the major Budget 2026 announcements, their implications for taxpayers and businesses, and how Tally Prime can support better accounting and financial management.
1. What Is the Union Budget and Why Does It Matter?
The Union Budget is the Government of India's annual financial statement, presenting estimated receipts and expenditure for the coming financial year.
It outlines taxation proposals, government spending priorities, borrowing requirements and economic-development initiatives.
The Budget influences several areas of business activity.
Tax proposals may change compliance requirements and transaction costs. Infrastructure spending can create demand for goods and services. MSME initiatives may improve access to financing, while sector-specific measures can encourage investment.
Businesses should distinguish between Budget announcements, enacted legislation and operational schemes. Some proposals require legislative approval, notifications or implementation guidelines before they become applicable.
2. An Emotional Story: A Small Business Owner Waiting for Financial Relief
Rajesh operated a small electrical equipment distribution business in Delhi.
His father had established the shop many years earlier, and Rajesh had gradually expanded it into a wholesale operation.
Although annual sales were increasing, financial pressure remained constant.
Customers frequently requested extended credit periods, suppliers expected timely payments and warehouse expenses continued rising.
One evening, Rajesh sat with his accountant reviewing outstanding invoices.
He had worked throughout the year, yet much of his business capital remained locked in customer receivables.
When Budget 2026 was presented, Rajesh paid particular attention to announcements concerning MSME financing and payment liquidity.
He hoped that better financing mechanisms could eventually help businesses like his manage working capital more effectively.
His accountant explained that government schemes could create opportunities, but eligibility, implementation and documentation would still matter.
Together, they began improving the company's accounting records, outstanding payment reports and cash flow planning through Tally Prime.
Rajesh realized that financial growth required more than waiting for government assistance.
It also required disciplined accounting, accurate records and timely business decisions.
For him, the Budget represented an opportunity to prepare his family business for a more stable future.
This is an illustrative story, not a documented account of an actual beneficiary.
3. Major Highlights of Union Budget 2026–27
The Budget introduced several important fiscal and economic measures.
Union Budget 2026–27: Selected budget estimates
Total expenditure
₹53.5 lakh cr
Capital expenditure
₹12.2 lakh cr
Fiscal deficit target
4.3% of GDP
SME Growth Fund proposal
₹10,000 cr
Rounded budget estimates and announced funding proposals; these are not actual expenditure or disbursement figures.
The Budget also emphasized strategic manufacturing, infrastructure, business financing, technology development and tax administration simplification.
These measures aim to support economic activity while maintaining fiscal discipline.
4. Income Tax Slabs Under the New Tax Regime
One important point for individual taxpayers is that Budget 2026 did not introduce a fresh general revision of the new-regime income tax slabs.
The applicable slab structure includes:
|
Taxable income
|
New-regime tax rate
|
|---|
|
Up to ₹4,00,000
|
Nil
|
|
₹4,00,001–₹8,00,000
|
5%
|
|
₹8,00,001–₹12,00,000
|
10%
|
|
₹12,00,001–₹16,00,000
|
15%
|
|
₹16,00,001–₹20,00,000
|
20%
|
|
₹20,00,001–₹24,00,000
|
25%
|
|
Above ₹24,00,000
|
30%
|
Eligible resident individuals may receive a rebate under Section 87A, subject to applicable conditions.
Under the relevant provisions, the rebate threshold is ₹12 lakh of taxable income, with a maximum rebate of ₹60,000 and marginal relief provisions.
Special-rate income may not qualify for the rebate.
Taxpayers should also consider the applicable cess, surcharge, deductions and other provisions when calculating final tax liability.
5. Income Tax Act, 2025: A Major Compliance Transition
One of the significant developments associated with Budget 2026 is the implementation of the Income Tax Act, 2025 from 1 April 2026.
The new legislation is intended to simplify the structure and presentation of income tax law.
For businesses and taxpayers, this transition makes it important to review terminology, return-filing requirements and relevant compliance procedures.
Why the transition matters
Businesses maintain accounting records throughout the financial year, but income tax compliance involves separate classifications, adjustments and reporting requirements.
A change in the statutory framework may require updates to internal processes and professional guidance.
Accountants should review applicable forms, notifications and filing procedures rather than assuming that older references remain unchanged.
How Tally Prime helps
Tally Prime can help maintain organized accounting ledgers, income records, expense classifications and financial statements.
These records support tax computation and reconciliation, although income tax returns and specialized calculations may require separate tools or professional review.
6. Budget 2026 and MSME Growth Opportunities
Micro, Small and Medium Enterprises are central to India's employment, manufacturing and commercial activity.
Budget 2026 proposed a three-part approach to support MSME development through equity financing, improved liquidity and professional assistance.
SME Growth Fund
A dedicated ₹10,000 crore SME Growth Fund was proposed to support the development of promising enterprises.
The initiative is intended to help eligible businesses access growth-oriented capital.
Actual eligibility and financing depend on the scheme's operational framework.
Self-Reliant India Fund
An additional ₹2,000 crore was proposed for the Self-Reliant India Fund to strengthen risk-capital support.
Liquidity support
The Budget also emphasized strengthening receivables financing through mechanisms associated with the Trade Receivables Discounting System.
These initiatives are important because delayed customer payments can create substantial financial pressure for MSMEs.
However, funding announcements should not be interpreted as automatic financial assistance to every registered business.
7. Understanding TReDS and MSME Payment Liquidity
TReDS is an electronic platform designed to facilitate financing of eligible trade receivables.
For qualifying transactions, it can help MSMEs obtain financing against invoices accepted by buyers.
Why receivables financing matters
Consider a manufacturer that supplies goods worth ₹10 lakh to a large customer.
The customer may have agreed to pay after a specified credit period.
Meanwhile, the manufacturer must continue paying employees, suppliers and operating expenses.
An eligible invoice-financing arrangement may help the business receive funds earlier, subject to platform rules and financing terms.
Role of accounting software
Accurate invoice records, customer balances and supporting documentation are important for receivables management.
Tally Prime can help businesses maintain sales invoices, bill-wise receivables and outstanding reports.
However, the availability of direct TReDS integration depends on the relevant platform and any supported external solution.
8. Government Capital Expenditure and Economic Development
Budget 2026–27 provided for approximately ₹12.2 lakh crore in central government capital expenditure.
Capital expenditure supports the creation or improvement of long-term assets such as roads, railways and other infrastructure.
Public infrastructure investment can influence demand across several industries.
Construction companies may require more equipment and materials.
Electrical suppliers may benefit from infrastructure-related procurement.
Logistics businesses may experience opportunities from transport-network development.
Manufacturers may also benefit from improvements in connectivity and industrial infrastructure.
However, individual businesses should evaluate actual projects, procurement conditions and customer demand before making investment decisions.
9. Manufacturing and Industrial Development
The Budget emphasized manufacturing growth in strategic sectors.
Announcements included measures related to biopharmaceuticals, electronics, critical minerals and other industries.
These initiatives aim to improve domestic production capabilities and strengthen industrial competitiveness.
For MSMEs, opportunities may arise through component supply, packaging, distribution, maintenance and other supporting services.
A small manufacturer should not assume that sectoral incentives apply directly to its business.
Eligibility may depend on industry classification, investment requirements, location and scheme-specific conditions.
10. Budget 2026 and Investment Taxation
Investors should pay attention to the Budget's proposals concerning securities transactions and taxation.
Securities Transaction Tax
The Budget proposed increases in STT on specified derivatives transactions.
In particular, the proposed rate for futures transactions increased from 0.02% to 0.05%.
Changes affecting options transactions were also announced.
These measures may increase transaction costs for certain market participants.
Share buybacks
Changes were proposed to the tax treatment of share buybacks, including capital gains treatment and additional provisions affecting promoters.
Investors should review the applicable legislation, transaction date and tax classification before calculating liability.
Investment planning
Tax treatment is only one part of an investment decision.
Investors should also consider risk, liquidity, investment horizon and personal financial objectives.
The Budget does not guarantee higher returns from any asset class.
11. TDS and TCS Changes Affecting Taxpayers
Budget 2026 included proposals to rationalize certain Tax Deducted at Source and Tax Collected at Source provisions.
Among the announcements were reductions in TCS rates for specified overseas tour packages and certain education or medical remittances under the Liberalised Remittance Scheme.
The Budget also proposed changes affecting manpower services and selected other transactions.
These measures may simplify compliance or reduce upfront cash outflows in qualifying situations.
However, businesses must check the effective dates, statutory conditions and applicable transaction categories before changing deductions or collections.
How Tally Prime can help
Tally Prime supports TDS and TCS accounting features where applicable.
Businesses can maintain relevant ledgers, configure statutory information and review transaction records.
Software configuration should be checked whenever tax rates or legal requirements change.
12. Case Study One: A Wholesale Distributor Strengthens Cash Flow Planning
Illustrative case study
A wholesale electrical distributor in Karol Bagh, Delhi, supplied products to contractors and retailers.
The company experienced steady sales growth but faced delays in customer collections.
The challenge
Large outstanding balances created pressure on supplier payments.
Management also struggled to identify which customers had exceeded agreed credit periods.
The solution
The business reviewed Budget 2026 initiatives relating to MSME liquidity while independently improving its financial controls.
Using Tally Prime, the accounts team organized customer ledgers, maintained bill-wise outstanding information and reviewed receivables reports.
Management also introduced more structured customer follow-ups.
The outcome
The company gained better visibility into overdue invoices and working capital requirements.
It became easier to prepare documentation for discussions with financial institutions.
The example demonstrates how accurate accounting records can help MSMEs prepare for financing opportunities.
It does not imply that the business received government funding.
13. Case Study Two: A Manufacturing Company Prepares for Expansion
Illustrative case study
A manufacturing business in Noida supplied engineering components to industrial customers.
Management wanted to invest in additional machinery but was uncertain about its financial capacity.
The challenge
The company lacked a consolidated view of operating expenses, inventory investment and available cash.
The solution
The business reviewed its financial statements and studied the potential opportunities arising from infrastructure and manufacturing initiatives.
Its accounting team used Tally Prime to examine purchase records, inventory values, profitability and outstanding balances.
Management then developed a phased investment plan based on projected cash flows.
The outcome
The company improved financial visibility before committing to major capital expenditure.
The example shows how accounting information can support expansion planning, regardless of whether a business qualifies for government incentives.
14. How Union Budget 2026 Affects Household Financial Planning
Individual taxpayers should review how the applicable tax regime influences take-home income and savings.
Important considerations include salary structure, eligible deductions, investment income and tax liabilities.
Families should also evaluate emergency savings, insurance needs and long-term financial commitments.
For example, a salaried employee planning to purchase a home should assess loan affordability based on actual disposable income rather than expected tax relief alone.
Similarly, retirement planning should reflect investment risk, inflation and long-term financial objectives.
Budget announcements can influence financial decisions, but a suitable personal plan must account for individual circumstances.
15. How Budget 2026 Can Influence Small Business Investment
Business owners may consider expanding operations when economic conditions and demand appear favourable.
However, investment decisions should be based on realistic financial analysis.
Before purchasing machinery, opening another branch or increasing inventory, management should review expected revenue, operating costs and funding requirements.
Cash flow forecasts are particularly important because profitable businesses can still face liquidity problems.
Tally Prime supports this process by maintaining accounting records and providing financial reports.
These reports can help owners evaluate whether expansion plans are financially sustainable.
16. How Tally Prime Supports Budget-Related Financial Compliance
Businesses need reliable accounting information to respond effectively to changing tax and economic conditions.
Tally Prime offers several capabilities that can support financial management.
GST accounting
Businesses can record GST-related transactions and review relevant tax information.
TDS and TCS records
Applicable statutory features help maintain relevant deduction and collection records.
Financial statements
Profit and Loss Accounts and Balance Sheets help management understand business performance.
Cash and bank management
Cash books, bank ledgers and reconciliation processes support financial monitoring.
Receivables and payables
Outstanding reports help identify customer dues and supplier obligations.
Inventory management
Stock reports provide visibility into quantities, values and inventory movements.
Business reporting
Management can examine transaction information and financial results over selected periods.
Tally Prime should be configured according to applicable legal requirements and the company's accounting policies.
17. Budget Planning and Cost Control Using Tally Prime
Budget preparation is not limited to government finances.
Every business benefits from preparing its own operating and financial budgets.
For example, a distributor may estimate annual sales of ₹2 crore and plan purchases, employee expenses, transportation costs and marketing expenditure accordingly.
Tally Prime provides budgeting and variance-analysis capabilities that can help compare planned figures with actual results.
Practical budgeting process
First, estimate expected revenue using historical sales information.
Next, identify major expense categories.
Prepare budgets for relevant departments, cost centres or ledgers where appropriate.
Review actual results periodically.
Investigate significant differences between planned and actual performance.
Update future plans when business conditions change.
This process can help businesses respond more effectively to economic uncertainty.
18. The Role of Digital Accounting in Tax Compliance
Tax compliance requires accurate documentation, timely recording and reliable financial information.
Businesses relying entirely on manual registers may experience difficulties reconciling invoices, payments and statutory records.
Digital accounting systems can improve consistency and make relevant information easier to retrieve.
However, software does not eliminate the need for professional judgment.
Incorrect ledger classification, missing transactions or outdated tax settings can still create compliance problems.
Businesses should maintain regular backups, review statutory configurations and conduct periodic reconciliations.
19. Budget 2026 and the Outlook for the Indian Economy
The Budget's fiscal strategy combines growth-oriented spending with continued attention to government borrowing and debt.
The fiscal deficit target of 4.3% of GDP reflects the government's planned borrowing requirement relative to the economy.
Capital expenditure and manufacturing initiatives are intended to support long-term economic activity.
Nevertheless, actual economic outcomes depend on multiple factors, including private investment, global demand, inflation, interest rates and implementation effectiveness.
For small businesses, the most practical approach is to monitor market conditions while maintaining financial discipline.
Growth opportunities should be evaluated alongside financing costs and operational risks.
20. Practical Financial Checklist for Businesses After Budget 2026
Businesses should review their accounting and tax procedures in light of applicable changes.
Businesses should also consult qualified tax and financial professionals when evaluating material compliance changes or investment decisions.
Conclusion
Union Budget 2026–27 introduced important measures relating to tax administration, MSME financing, manufacturing, infrastructure and investment taxation.
For individual taxpayers, the continuation of the existing new-regime slab structure and the transition to the Income Tax Act, 2025 are significant considerations.
For MSMEs, proposals involving growth capital, receivables financing and professional support may create opportunities, subject to implementation and eligibility.
For investors, changes to securities transaction taxation and other provisions require careful review.
Tally Prime can help businesses respond to these developments by maintaining accurate accounting records, monitoring receivables, managing inventory and supporting financial planning.
Ultimately, successful financial management depends on understanding applicable rules, maintaining reliable records and making decisions based on realistic business conditions.
Powered by Binarysoft Technologies
Authorized Tally Partner
Location: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact Us: +91 7428779101, 9205471661
Email: tally@binarysoft.com
Business Hours: 10:00 AM – 6:00 PM, Monday to Friday
Frequently Asked Questions
How can Binarysoft Technologies help businesses manage accounting changes?
Binarysoft Technologies can assist with Tally Prime implementation, statutory configuration, GST accounting, TDS and TCS workflows, financial reporting, budgeting, inventory management and employee training.
How can small businesses prepare for Budget-related changes?
Businesses should review applicable tax provisions, update accounting configurations, monitor receivables, maintain documentation and evaluate relevant financing opportunities.
Can Tally Prime help with tax compliance?
Yes. Tally Prime supports GST accounting, applicable TDS and TCS records, financial statements and other accounting processes, subject to proper configuration and review.
Did Budget 2026 introduce changes to securities transaction taxation?
Yes. Changes to STT on specified derivatives transactions were announced, including an increase in the rate applicable to futures.
CA. Yuvan Rajagopal specializes in accounting advisory, statutory compliance, and financial consulting. He writes extensively on business automation, inventory management, and accounting best practices.