Call CA Tally HelpDesk
+91 9205471661,
7428779101
What Changed for Manufacturing Businesses in 2026?
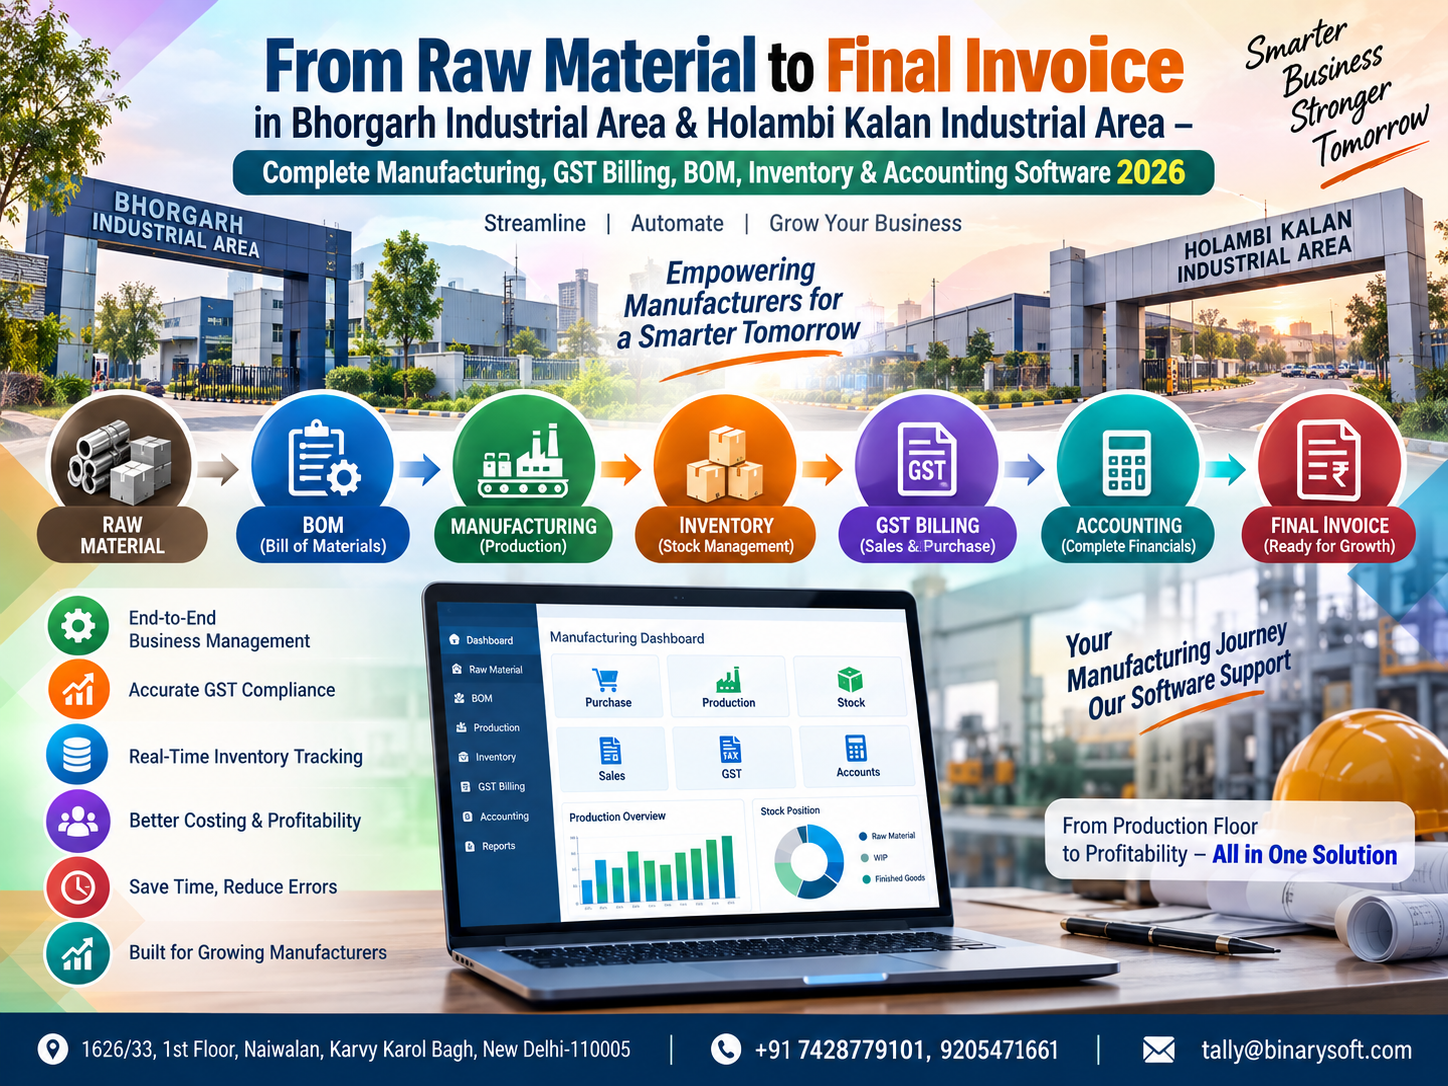
In 2026, manufacturers in Bhorgarh Industrial Area and Holambi Kalan Industrial Area are under growing pressure to know exactly what happens between raw-material purchase and the final customer invoice. Rising input costs, multiple components, production wastage, changing stock levels, GST documentation and tighter delivery schedules make disconnected spreadsheets and manual registers increasingly difficult to control. A manufacturer may be generating healthy sales yet still lose margin because raw-material consumption, work-in-process, finished goods and actual production costs are not visible together. This is where integrated Manufacturing, GST Billing, BOM, Inventory & Accounting Software can make a practical difference. By connecting purchases, Bill of Materials, manufacturing entries, stock movement, finished goods, GST invoices and accounts, businesses gain clearer operational visibility. The benefit is straightforward: fewer repetitive entries, better material control, faster billing, improved cost awareness and more reliable information for everyday production and financial decisions.
Manufacturing in 2026: The Journey From Raw Material to Final Invoice
Manufacturing is not simply the process of buying material and selling a finished product.
Between these two activities lies an entire chain of business processes.
A typical manufacturing cycle may involve:
Raw-material purchase
Material receipt
Quality verification
Raw-material storage
Production planning
Bill of Materials
Material issue for production
Production or assembly
Wastage and scrap
Work-in-process
Finished goods
Finished-goods storage
Sales order
Packing
Dispatch
GST invoice
Customer outstanding
Accounting
Management reporting
If these stages are maintained independently, management can struggle to understand what is actually happening inside the factory.
A properly configured manufacturing and accounting system connects these activities and helps create a more reliable flow of information from the first purchase to the final sale.
Why Bhorgarh Industrial Area Manufacturers Need Integrated Software
Manufacturing units operating in and around Bhorgarh Industrial Area may deal with raw materials, components, semi-finished products, finished products, suppliers, customers and production activities every day.
As the volume of operations increases, basic questions become surprisingly difficult to answer when records are fragmented.
How much raw material is currently available?
How much has been consumed?
How many finished units were produced?
What quantity was rejected?
What is waiting for production?
What stock is ready for dispatch?
Which customer orders are pending?
How much money is outstanding?
Which supplier needs to be paid?
What is the profitability of the business?
An integrated software environment can bring much of this information together.
Instead of relying on multiple spreadsheets and registers, management can use transaction-based reports for better visibility.
Manufacturing Software for Holambi Kalan Industrial Area
Holambi Kalan and nearby industrial locations support a variety of manufacturing, trading, warehousing and commercial activities.
For a manufacturing business, physical activity happens continuously.
Materials arrive.
Components move to production.
Finished products return to stores.
Orders are packed.
Goods are dispatched.
Invoices are generated.
Payments are collected later.
The challenge is ensuring that the software records reflect these physical movements.
When the factory floor and accounting records tell different stories, management loses visibility.
Manufacturing software aims to reduce this gap.
From Raw Material to Finished Goods: How an Integrated Workflow Works
Consider a simplified example.
A manufacturer receives an order for 500 finished units.
The business first checks whether sufficient finished stock already exists.
If not, production requirements must be calculated.
The Bill of Materials identifies the components required for each unit.
The system can then help determine the approximate material requirement for the planned quantity.
Raw materials are issued.
Production takes place.
Finished goods are recorded.
Applicable wastage or by-products are accounted for.
Finished stock becomes available.
The sales invoice is generated when goods are dispatched.
Accounting records are updated according to the transaction workflow.
The entire process creates a connected information chain.
That is the fundamental advantage of integrated manufacturing software.
A Factory Owner’s Story: The Order That Looked Profitable
Consider a fictional manufacturer operating near Holambi Kalan.
The owner had spent years building the business.
He knew his customers personally, negotiated purchases himself and often remained at the factory long after employees had left.
One month, the company received one of its biggest orders.
Everyone was excited.
Production worked overtime.
The goods were completed and dispatched before the deadline.
The customer was happy.
The invoice value looked impressive.
The owner believed it had been one of the company's most profitable orders.
Several weeks later, while reviewing purchases and expenses, something did not feel right.
Raw-material consumption had been much higher than expected.
Extra components had been purchased during production.
Scrap had not been properly recorded.
Overtime costs had increased.
Some unused materials were lying on the factory floor but were still considered consumed in the spreadsheet.
Nobody could tell him the actual cost of producing the order.
The invoice showed revenue.
But revenue could not tell him the real margin.
For the owner, the uncomfortable question was simple:
“We completed the order successfully, but how much did we actually earn?”
That question changed how he looked at software.
He no longer wanted an application that simply printed invoices.
He wanted a system that could help connect material consumption, production, inventory and accounting.
As the processes became more structured, the benefit was not just cleaner reports.
It was confidence that business decisions were being made using better information.
What Is Manufacturing ERP Software?
Manufacturing ERP software integrates different business processes into a structured system.
Depending on the software, configuration and business requirements, this can include:
Purchase management
Raw-material inventory
Bill of Materials
Production entries
Manufacturing journals
Finished-goods inventory
Godown management
Sales orders
GST invoicing
Customer receivables
Supplier payables
Accounting
Banking
Cost tracking
Business reports
The objective is to reduce information gaps between the factory, warehouse, sales department and accounts team.
Raw Material Inventory Management
Raw materials are the starting point of production.
If raw-material information is inaccurate, production planning becomes unreliable.
Imagine that the system reports 2,000 units of a component.
Production requires 1,500.
The production manager assumes sufficient stock exists.
But when employees check the warehouse, only 1,200 usable units are available.
Production stops.
Purchasing receives an emergency requirement.
The supplier charges a higher price for urgent delivery.
The customer dispatch is delayed.
A seemingly small inventory discrepancy can therefore create a chain reaction.
Accurate raw-material inventory is essential for manufacturing control.
Bill of Materials: The Foundation of Production Planning
A Bill of Materials, commonly called BOM, defines the materials or components required to manufacture a finished product.
For example, suppose a manufacturer produces Product A.
One unit might require:
2 units of Component X
4 units of Component Y
1 unit of Component Z
0.5 kg of Material M
Packaging material
If the company plans to manufacture 1,000 units, the BOM provides a structured basis for calculating material requirements.
Without a standardized BOM, material consumption can become dependent on individual employee knowledge or manual calculations.
Why BOM Management Matters
A properly maintained BOM can help a manufacturer understand the relationship between raw materials and finished products.
It supports questions such as:
What materials are required?
How much material should be consumed?
What quantity is required for the production plan?
Which component could create a shortage?
How does actual consumption compare with expected consumption?
When BOM data is maintained carefully, it can become an important foundation for inventory and production control.
Multi-Level BOM for Complex Manufacturing
Some finished products are not manufactured in one simple step.
A finished product may contain a sub-assembly.
That sub-assembly may itself contain several components.
This creates a multi-level production structure.
For example:
Finished Product
Sub-Assembly A
Component 1
Component 2
Sub-Assembly B
Component 3
Component 4
Packaging Material
Businesses with such processes should evaluate whether their manufacturing solution can represent the level of production complexity they actually require.
Production Planning
Production should ideally begin with a clear understanding of demand and available inventory.
A manufacturer may need to consider:
Confirmed sales orders
Expected orders
Finished-goods stock
Raw-material availability
Production capacity
Delivery commitments
Pending purchase orders
Production planning connects customer demand with factory activity.
Without this visibility, factories can produce too much of the wrong product while running short of the product customers actually need.
Material Requirement Planning
Once production quantity is known, the next question is:
“What materials do we need?”
A BOM provides the expected material requirement.
Available stock can then be compared against this requirement.
Suppose production requires:
5,000 units of Component A
3,000 units of Component B
2,000 kg of Material C
Available stock is:
Component A – 4,200 units
Component B – 3,500 units
Material C – 1,400 kg
The business can identify shortages before production starts.
This gives purchasing teams more time to procure the required material.
Purchase Management for Manufacturers
Purchasing has a direct impact on manufacturing profitability.
A small increase in raw-material cost can significantly affect margins when production volumes are high.
Manufacturing software can help businesses maintain structured records of:
Suppliers
Purchase transactions
Material quantities
Purchase rates
Taxes
Outstanding supplier balances
Purchase returns
Historical purchases
This gives management better information when reviewing procurement activity.
Supplier Management
Reliable suppliers are critical to uninterrupted production.
A supplier delay can become a production delay.
A production delay can become a customer delivery delay.
Supplier records can help businesses review historical transactions, rates, outstanding balances and purchasing patterns.
However, software does not replace supplier relationship management.
It provides information that can support better decisions.
Goods Receipt and Raw-Material Verification
Receiving material should be treated as an important control point.
Businesses should ensure that the material recorded in software reflects what was actually received.
Depending on internal procedures, this may involve checking:
Item
Quantity
Unit
Supplier
Purchase document
Rate
Batch or lot information where relevant
Storage location
Quality status where maintained
Accurate receiving records improve the reliability of subsequent inventory reports.
Godown and Warehouse Management
Manufacturing businesses may maintain multiple storage locations.
For example:
Raw Material Store
Production Floor
Work-in-Process Area
Finished Goods Warehouse
Packing Area
Dispatch Area
Separate Warehouse
If inventory is tracked only at the company level, management may know the total quantity but not the physical location of the stock.
Location-wise inventory tracking provides better operational visibility.
Material Issue for Production
When raw materials leave the warehouse for production, the movement should be reflected in the system according to the configured workflow.
This helps distinguish between:
Material available in stores
Material issued for production
Material consumed
Finished goods produced
Material returned
Wastage or scrap
Without structured material movement, inventory reports can become misleading.
Work-in-Process Management
Not all materials issued to production immediately become finished products.
Some remain under production.
This is commonly referred to as Work-in-Process or WIP.
For businesses with longer manufacturing cycles, understanding WIP can be important for inventory and operational analysis.
Management needs to know that material has not disappeared.
It has simply moved into another stage of production.
Finished Goods Inventory
Once production is completed, finished goods need to be recorded correctly.
The business should be able to understand:
What has been produced?
What quantity is available?
Where is it stored?
What has already been committed?
What is ready for dispatch?
What has already been sold?
Accurate finished-goods information allows sales and dispatch teams to respond to customers more confidently.
Wastage and Scrap Management
Manufacturing rarely converts every unit of raw material into saleable finished goods.
There may be:
Normal process loss
Cutting waste
Damaged components
Rejected material
Scrap
By-products
Ignoring these quantities can distort inventory and costing information.
A structured process for recording wastage and scrap improves transparency.
Production Variance
Suppose a BOM indicates that 100 units of material should produce 95 finished units.
Actual production produces only 89.
That difference deserves attention.
Possible reasons might include:
Higher wastage
Machine issues
Quality rejection
Incorrect material issue
Process inefficiency
Data-entry mistakes
Software provides the numbers.
Management must investigate the business reason.
Manufacturing Cost Visibility
Knowing the selling price is easy.
Understanding the complete production cost can be more difficult.
Depending on the accounting and costing methodology used by the business, cost analysis may involve:
Raw materials
Components
Packaging
Labour
Power
Factory overheads
Freight
Subcontracting
Wastage
Other production expenses
Better cost information helps management evaluate pricing and margins more carefully.
GST Billing Software for Manufacturing Businesses
After production comes sale and dispatch.
Manufacturers need an organized billing process that captures relevant transaction details.
A GST invoice may include applicable information such as:
Supplier details
Customer details
GSTIN
Invoice number
Invoice date
Item description
HSN information where applicable
Quantity
Rate
Taxable value
CGST
SGST
IGST
Total invoice value
Place of supply and other relevant information
The exact tax treatment and documentation requirements depend on applicable GST provisions and the transaction involved.
Businesses should ensure their software configuration reflects current statutory requirements.
Local and Interstate GST Transactions
A Delhi manufacturer may sell goods within Delhi as well as to customers in other states.
The applicable GST treatment differs depending on the nature and place of supply of the transaction.
An appropriately configured accounting system can help businesses maintain the relevant tax information for their invoices.
However, businesses should verify their tax configuration with applicable GST rules and professional advice when required.
E-Invoicing Integration
Businesses covered by applicable e-invoicing requirements may need to generate invoices according to the prescribed GST e-invoicing process.
An appropriate software setup can reduce repeated manual entry and support a more structured invoicing workflow.
Businesses should verify current eligibility thresholds and compliance requirements from official GST sources because statutory rules can change.
E-Way Bill Workflow
Movement of goods may also require an e-way bill depending on the transaction and applicable rules.
For manufacturers dispatching goods regularly, integrating billing and dispatch-related information can reduce repetitive data entry.
Again, businesses should verify current legal requirements for their specific transactions.
Sales Order to Dispatch
A structured sales workflow can include:
Customer enquiry
Quotation
Sales order
Production requirement
Stock confirmation
Packing
Invoice
Dispatch
Payment follow-up
This creates visibility from customer demand to final delivery.
Faster GST Billing
Once finished goods are ready, invoice creation should not become a bottleneck.
Maintaining structured customer and item masters can reduce repetitive data entry.
Information such as customer details, tax information, product details, units and rates can be reused according to the configured workflow.
This improves billing efficiency.
Inventory and Accounting Integration
Inventory tells you what the business physically has.
Accounting tells you what the business financially owns, owes, earns and spends.
Manufacturers need both views.
A purchase affects inventory and supplier balances.
Production affects raw-material and finished-goods quantities.
A sale affects finished inventory, revenue and customer balances.
Payments affect receivables and bank or cash accounts.
Integration makes these relationships easier to track.
Customer Outstanding Management
Manufacturing businesses frequently sell on credit.
The invoice may be generated today while payment is received weeks later.
Customer outstanding reports can help businesses monitor:
Total receivables
Customer balances
Invoice-wise pending amounts
Overdue transactions
Payment history
Collection requirements
Sales growth without collection discipline can put pressure on cash flow.
Supplier Payables
Manufacturers must also manage money owed to suppliers.
Supplier payable information can help the accounts team understand:
Which suppliers need payment?
How much is outstanding?
What bills remain unpaid?
What payments have already been recorded?
What upcoming cash requirements may exist?
This supports better working-capital planning.
Cash Flow Matters as Much as Profit
A profitable business can still face cash-flow pressure.
For example, raw materials may need to be purchased today.
Employees and operating expenses must be paid.
But customers may pay after 30, 45 or 60 days.
This creates a working-capital gap.
Integrated accounting information helps management monitor receivables, payables, cash and bank positions more effectively.
Accounting Reports for Management
A properly maintained accounting system can provide important financial reports, including:
Profit & Loss Account
Balance Sheet
Trial Balance
Ledger Reports
Receivables
Payables
Cash Book
Bank Book
Sales Reports
Purchase Reports
Inventory Reports
These reports provide different views of business performance.
TallyPrime for Manufacturing Businesses
TallyPrime can support accounting, inventory, GST and various manufacturing-related business processes depending on the required configuration.
A manufacturing setup may involve:
Stock groups
Stock items
Units
Godowns
Bill of Materials
Manufacturing/stock journal workflows
Raw materials
Finished goods
Customer ledgers
Supplier ledgers
GST configuration
Sales vouchers
Purchase vouchers
Accounting reports
Inventory reports
The appropriate structure depends on the actual manufacturing process.
TallyPrime BOM for Manufacturing
Bill of Materials functionality can be useful for businesses that assemble or manufacture products from defined components.
A properly maintained BOM helps create consistency in expected material consumption.
However, BOMs should reflect real production processes.
If production specifications change, the master information should also be reviewed.
Outdated BOM data can produce misleading reports.
Manufacturing Journal and Stock Movement
Manufacturing and stock journal workflows can be used to record movement between raw materials and finished products depending on the configuration.
This can help businesses document the transformation of inventory rather than simply adjusting stock manually.
A disciplined transaction process improves the reliability of inventory reports.
Barcode and Item Identification
Manufacturers handling large numbers of components and finished goods may consider barcode-based identification where appropriate.
Barcodes can help improve item identification during warehouse and dispatch activities.
The suitability depends on the nature of the products, warehouse environment and workflow.
Multi-User Manufacturing Operations
Growing factories often require multiple employees to use business software.
For example:
Accounts team handles accounting.
Billing team creates invoices.
Warehouse team manages stock-related activity.
Management reviews reports.
The software environment should therefore be planned around user requirements, controls and data security.
User Access and Internal Control
Not every employee needs unrestricted access.
Where supported, businesses should consider appropriate access based on job responsibilities.
Sensitive accounting or management information should be accessible only to authorized users.
Internal controls become increasingly important as the number of employees using the system grows.
Data Backup for Manufacturing Businesses
Manufacturing data represents years of transactions and operational history.
A system failure without a usable backup can disrupt:
Billing
Accounting
Inventory
Customer records
Supplier records
Production information
Management reporting
Businesses should establish a regular backup process and periodically verify that backups can actually be restored.
Why Excel Alone Becomes Difficult as a Factory Grows
Excel is extremely useful for analysis and reporting.
But using multiple spreadsheets as the primary transaction system becomes increasingly difficult as operations grow.
Imagine separate files for:
Purchases
Raw materials
Production
Finished goods
Sales
Outstanding payments
Expenses
Every file depends on manual updating.
If one transaction is missed, reports begin to disagree.
Integrated ERP reduces the need for this duplication.
One Transaction, Multiple Business Effects
Consider a customer sale.
One transaction can affect:
Finished-goods stock
Sales revenue
GST information
Customer receivable
Profitability
Sales reports
When these effects are maintained in separate systems, reconciliation becomes necessary.
When transactions are integrated, information can flow more consistently.
Reduce Manual Data Entry
Repetitive data entry consumes employee time and increases the risk of mistakes.
A manufacturer should therefore evaluate where information is being entered more than once.
If the same invoice information is manually entered into billing, inventory, accounting and management spreadsheets, there is an opportunity to improve the workflow.
Better Management Reporting
Factory owners need answers, not piles of disconnected data.
Management may want to know:
How much did we produce today?
What raw material is running low?
What finished goods are available?
What orders are pending?
How much did we sell?
How much money is outstanding?
Which suppliers require payment?
What is the current stock value?
Which products are moving?
Where are production variances occurring?
ERP reporting helps transform recorded transactions into usable management information.
Better Production Decisions
Good manufacturing decisions require timely information.
A production manager who knows the available raw material, pending orders and finished-goods stock can plan differently from one working only from estimates.
Software does not make the decision.
It improves the information available to the person making it.
Avoid Overproduction
Producing more than customers require can block working capital.
Finished products occupy warehouse space and may become obsolete or difficult to sell.
Inventory and sales information can help manufacturers compare production with actual demand.
Avoid Underproduction
Underproduction creates a different problem.
Customers may place orders that cannot be fulfilled on time.
The result can be emergency production, expensive procurement and delayed delivery.
Better demand and inventory visibility can help businesses plan production more effectively.
Track Slow-Moving Finished Goods
Finished products that remain unsold represent blocked capital.
Manufacturers should periodically review inventory movement.
Slow-moving reports can help identify items requiring management attention.
The response may involve adjusting production, reviewing pricing, improving sales activity or investigating changes in customer demand.
Improve Working-Capital Control
Manufacturing consumes capital before revenue is collected.
Money may be tied up in:
Raw materials
Work-in-process
Finished goods
Customer receivables
Reducing unnecessary inventory and improving collection visibility can therefore have a meaningful impact on working capital.
Choosing Manufacturing Software in Bhorgarh Industrial Area
Before selecting software, manufacturers should document their actual workflow.
Important questions include:
How many raw materials do we maintain?
How many finished products do we manufacture?
Do we require BOM?
Do we have multi-level production?
Do we track wastage?
Do we maintain work-in-process?
How many godowns exist?
How many users require access?
How many invoices are generated daily?
Do we sell interstate?
Do we need GST e-invoicing according to applicable rules?
What reports does management need?
What is our current accounting process?
The answers help determine the appropriate software configuration.
Choosing Manufacturing Software in Holambi Kalan Industrial Area
Businesses should avoid selecting software solely based on the number of advertised features.
A smaller manufacturer may need straightforward accounting, inventory, BOM and GST billing.
A larger factory may require more complex production, warehouse, reporting and integration workflows.
Software should match the actual business process.
Implementation Is More Important Than Installation
Installing software can take minutes.
Building a reliable business system takes planning.
Implementation may involve:
Understanding workflows
Preparing master data
Creating stock structures
Creating ledgers
Defining BOMs
Setting opening balances
Configuring GST
Setting user controls
Testing transactions
Training employees
Reviewing reports
Correcting process gaps
The quality of implementation directly affects the usefulness of the system.
Clean Master Data Before Going Live
Poor master data creates poor reports.
Before implementation, businesses should review:
Duplicate stock items
Incorrect item names
Wrong units
Duplicate customers
Duplicate suppliers
Incorrect GST details
Incorrect opening stock
Incorrect ledger balances
Old or unused masters
Starting with cleaner data makes future reporting more reliable.
Employee Training Matters
Even the best software can fail if employees do not understand the process.
Employees should know:
Which transaction to record
When to record it
Which item to select
How to handle corrections
How to record returns
How to handle material movement
How to verify reports
Training should focus on the real workflow of the business rather than only software menus.
Review After Implementation
ERP implementation should not end on the first day of use.
After employees begin working with the system, management should review:
Are reports accurate?
Are users following the process?
Are unnecessary manual spreadsheets still being maintained?
Are BOMs correct?
Are stock quantities matching physical inventory?
Are outstanding reports useful?
Are there repetitive activities that can be improved?
Continuous review helps the system evolve with the business.
From Factory Floor to Financial Statement
The strongest manufacturing system connects operational activity with financial information.
Raw material is purchased.
Material enters inventory.
Material moves into production.
Production creates finished goods.
Finished goods are sold.
Invoices create receivables.
Customers make payments.
Accounting records the financial result.
When these activities are connected, management gains a much clearer picture of the business.
Manufacturing Digital Transformation in 2026
Digital transformation does not necessarily mean replacing every human decision with automation.
For many manufacturers, transformation begins with something simpler:
Stop entering the same data repeatedly.
Stop maintaining conflicting stock records.
Stop depending entirely on individual employees for critical information.
Start creating structured transactions.
Start connecting inventory with accounting.
Start reviewing reports regularly.
Start making decisions using business data.
These improvements can have a significant impact as the company grows.
Complete Manufacturing, GST Billing, BOM, Inventory & Accounting Solution in Delhi
Manufacturing businesses in Bhorgarh Industrial Area, Holambi Kalan Industrial Area and surrounding Delhi industrial locations can evaluate TallyPrime and related solutions for accounting, inventory, GST billing and manufacturing workflows.
The appropriate configuration should be based on actual business requirements rather than a one-size-fits-all setup.
A company manufacturing 50 products with simple assembly requirements needs a different system design from a factory handling thousands of components, multiple warehouses and several production stages.
Understanding this difference is essential for successful implementation.
Powered by Binarysoft Technologies
Authorized Tally Partner
Binarysoft Technologies provides Tally-related sales, implementation and support services for businesses seeking better accounting, GST billing, inventory and manufacturing workflows.
Location:
1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact us:
+91 7428779101, 9205471661
Email us:
tally@binarysoft.com
Support Hours:
10:00 AM – 6:00 PM, Monday–Friday
Conclusion
For manufacturers in Bhorgarh Industrial Area and Holambi Kalan Industrial Area, the journey from raw material to final invoice contains many stages where information can become disconnected.
Raw materials are purchased and stored.
Materials move to production.
BOMs define expected consumption.
Manufacturing converts components into finished goods.
Wastage and scrap affect actual output.
Finished products move into inventory.
Customer orders lead to dispatch.
GST invoices are generated.
Receivables and supplier payments affect cash flow.
Accounting ultimately shows the financial impact.
Managing these activities through disconnected spreadsheets and manual registers becomes increasingly difficult as a factory grows.
An integrated Manufacturing, GST Billing, BOM, Inventory & Accounting Software solution can create a more structured information flow from purchase through production to final billing.
The real benefit is not simply faster invoice printing.
It is better visibility.
When a manufacturer can understand what materials are available, what has been consumed, what is being produced, what finished stock exists, what customers owe and what the business is earning, management can make decisions with greater confidence.
That is what turns accounting and manufacturing software from a record-keeping tool into a practical business management system.
Frequently Asked Questions
What is manufacturing ERP software?
Manufacturing ERP software is a business management system designed to connect processes such as purchasing, raw-material inventory, BOM, production, finished-goods inventory, sales, GST billing and accounting.
Is manufacturing software useful for factories in Bhorgarh Industrial Area?
Yes. Manufacturers handling raw materials, production, finished goods and regular billing can use structured software to improve inventory visibility, accounting and production-related record keeping.
CA. Darshit Malhotraa has hands-on experience in GST compliance, accounting reviews, and MSME consulting. He regularly works with businesses transitioning from manual systems to digital accounting platforms. His content emphasizes real-world problem solving and operational efficiency.