Call CA Tally HelpDesk
+91 9205471661,
7428779101
Introduction: Why Credit Control and Cash Flow Management Matter More Than Ever
In 2026, growing businesses across India face a financial challenge that is often overlooked: increasing sales do not always mean increasing cash availability.
A wholesale trader may generate lakhs of rupees in monthly revenue but struggle to pay suppliers because customers have not cleared outstanding invoices. A manufacturer may receive large orders but lack sufficient working capital to purchase raw materials. A service provider may report profits while waiting several months for client payments.
These situations reveal an important business reality: profitability and cash flow are not the same thing.
For small and medium-sized enterprises, poor credit control can result in delayed collections, excessive outstanding balances, higher borrowing costs and financial uncertainty.
Traditional spreadsheets and manual payment registers often make it difficult to identify overdue invoices, monitor customer credit exposure and plan upcoming payments.
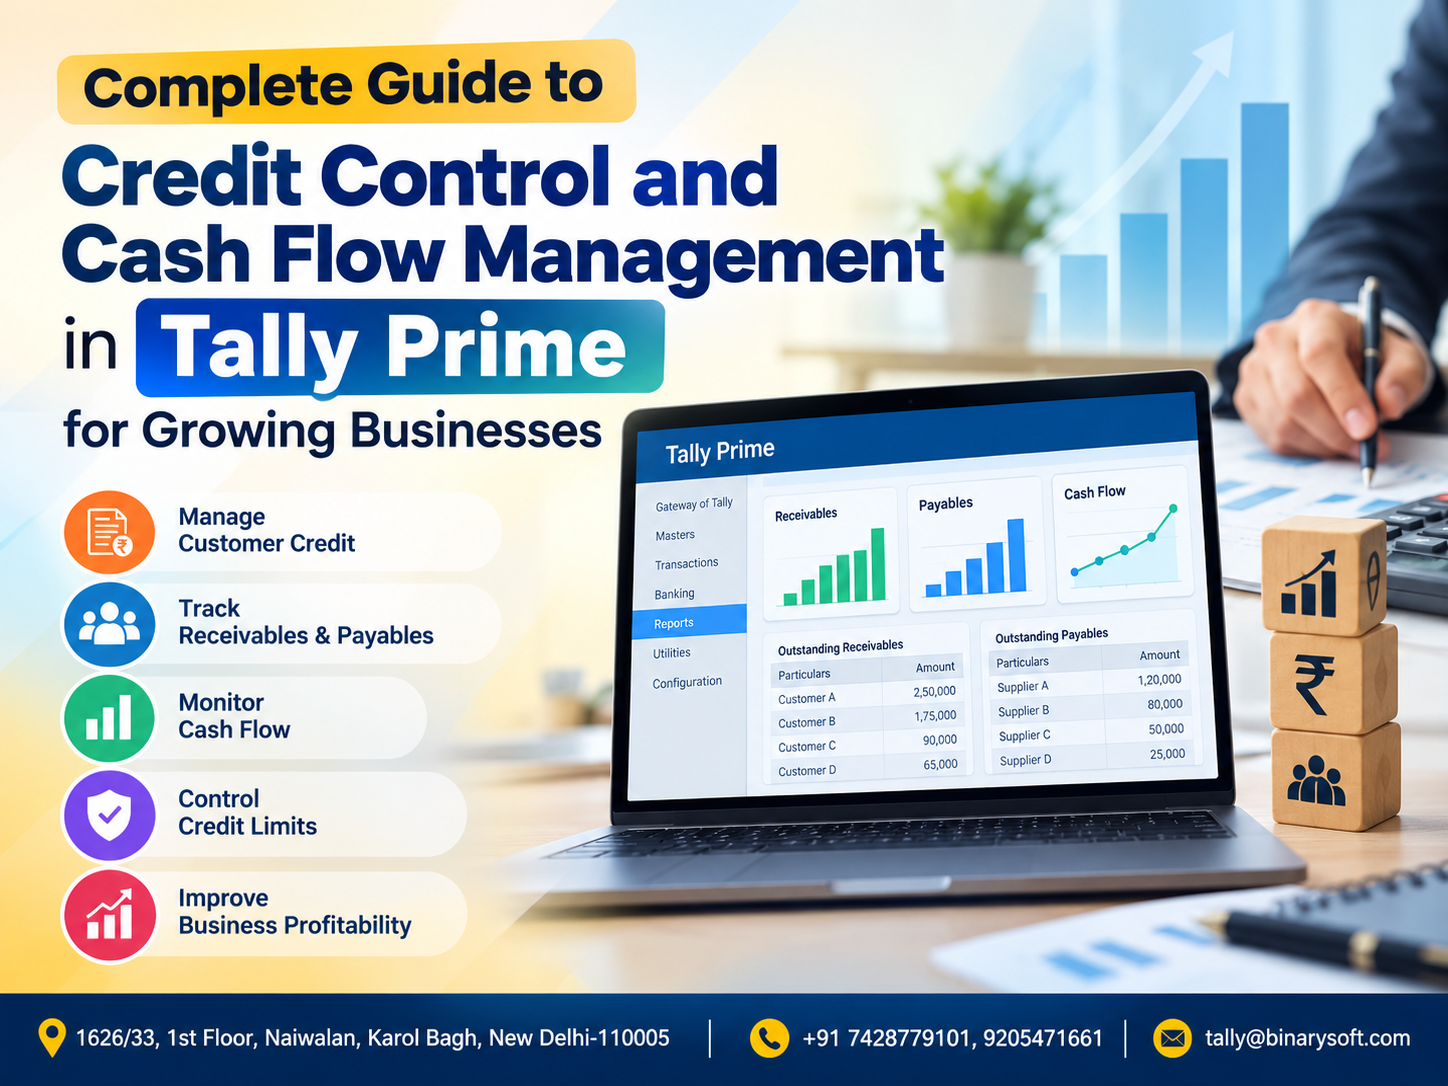
TallyPrime provides accounting and financial management features that help businesses maintain customer credit records, track receivables and payables, monitor cash and bank balances, and generate reports for better financial decisions.
By combining disciplined credit policies with accurate accounting, growing businesses can improve working capital management and build a stronger financial foundation.
1. Understanding Credit Control in Business Accounting
Credit control is the process of managing the amount of credit offered to customers and ensuring that payments are collected within agreed terms.
Many businesses allow customers to purchase goods or services immediately and make payment after 15, 30, 45 or 60 days.
Credit sales can help businesses attract customers and increase revenue. However, uncontrolled credit can create serious financial problems.
For example, a distributor selling ₹10 lakh worth of products every month may appear successful. But if ₹25 lakh remains unpaid by customers, the business may struggle to maintain inventory and meet operating expenses.
Effective credit control involves setting customer credit limits, establishing payment terms, monitoring outstanding invoices and following up on overdue balances.
Important elements of credit control
-
Customer-wise credit limits.
-
Agreed payment periods.
-
Bill-wise outstanding tracking.
-
Receivables ageing analysis.
-
Regular payment follow-ups.
-
Customer ledger reconciliation.
-
Credit exposure monitoring.
-
Periodic review of overdue accounts.
TallyPrime supports several of these activities through customer ledger configuration, bill-wise accounting and outstanding reports.
2. An Emotional Story: When Growing Sales Nearly Destroyed a Family Business
For twenty-two years, Ramesh operated a wholesale electrical goods business in Delhi.
He started with a small shop and gradually expanded into supplying electrical products to contractors, retailers and construction companies.
His reputation was built on trust.
Customers appreciated his flexible payment terms, and many considered him a reliable business partner.
As his sales increased, Ramesh began offering longer credit periods to maintain customer relationships.
Initially, everything appeared manageable.
Orders were increasing, employees were busy and the warehouse was filled with products.
But the bank balance told a different story.
Customers were delaying payments, while suppliers expected settlement within their agreed credit periods.
One afternoon, Ramesh received a call from a major supplier demanding payment for overdue invoices.
He promised to arrange the amount within three days.
That evening, he reviewed his records and discovered that customers owed his business more than ₹28 lakh.
Yet he had insufficient cash to pay salaries and purchase fresh inventory.
His wife noticed that he had stopped sleeping properly.
His son, who had recently joined the family business, asked a simple question:
"Papa, if we are selling so much, why do we never have enough money?"
Ramesh realised that he had focused on sales growth without paying enough attention to collections.
His son recommended introducing structured credit control using TallyPrime.
They organised customer ledgers, verified outstanding invoices, configured credit limits and began reviewing overdue balances every week.
The business also introduced clearer payment terms for new customers.
Over the following months, collections became more systematic.
Ramesh still faced difficult decisions, but he could now identify financial problems before they became emergencies.
One evening, he closed the shop on time and returned home to celebrate his wedding anniversary.
For him, better financial control meant more than improving accounting reports.
It meant restoring confidence, protecting his family business and finding peace of mind.
This is an illustrative story based on common working capital challenges faced by Indian businesses.
3. How TallyPrime Helps Businesses Manage Customer Credit
TallyPrime provides practical features for managing customer accounts and monitoring credit exposure.
Businesses can create separate ledgers for customers and maintain relevant credit information.
Customer credit limits
Credit limits help businesses establish how much outstanding credit may be extended to a customer.
For example, a wholesale distributor may establish the following policy:
|
Customer
|
Credit limit
|
Credit period
|
|---|
|
Customer A
|
₹2,00,000
|
30 days
|
|
Customer B
|
₹5,00,000
|
45 days
|
|
Customer C
|
₹1,00,000
|
15 days
|
TallyPrime supports credit limits and credit-period settings in customer ledger configurations.
Depending on the transaction and configuration, the system can warn users when credit conditions are exceeded.
Businesses should understand that credit warnings are not a substitute for management approval procedures.
Credit policy management
Businesses should establish clear rules for approving credit, reviewing limits and handling overdue accounts.
New customers may initially receive smaller credit limits, while established customers may qualify for higher limits based on payment history.
4. Bill-Wise Outstanding Management
One of the most useful features of TallyPrime is bill-wise accounting.
Instead of maintaining only a total customer balance, businesses can track individual invoices and related payments.
For example, a customer may have three unpaid invoices:
|
Invoice
|
Amount
|
Due date
|
|---|
|
INV-101
|
₹75,000
|
10 October
|
|
INV-102
|
₹45,000
|
20 October
|
|
INV-103
|
₹30,000
|
30 October
|
|
Total
|
₹1,50,000
|
|
Bill-wise accounting helps identify which invoices remain unpaid.
When a payment is received, the accountant can allocate it against the relevant invoice reference.
This improves customer balance accuracy and simplifies payment reconciliation.
It also helps avoid disputes when customers make partial payments or settle several invoices together.
5. Receivables Ageing Analysis for Better Collection Planning
Receivables ageing analysis helps businesses understand how long customer invoices have remained unpaid.
TallyPrime provides outstanding reports that can be analysed according to invoice age or overdue periods.
For example:
|
Outstanding age
|
Amount
|
Collection priority
|
|---|
|
0–30 days
|
₹4,00,000
|
Routine follow-up
|
|
31–60 days
|
₹2,50,000
|
High
|
|
61–90 days
|
₹1,20,000
|
Urgent
|
|
Above 90 days
|
₹80,000
|
Immediate review
|
|
Total
|
₹8,50,000
|
|
Ageing analysis helps management identify customers whose payments are becoming increasingly delayed.
Businesses can establish different follow-up procedures according to the overdue period.
For example, invoices overdue by 15 days may require a reminder, while invoices overdue by 60 days may require direct management intervention.
The objective is to improve collections while maintaining professional customer relationships.
6. Cash Flow Management: Understanding Money Coming In and Going Out
Cash flow management involves monitoring cash receipts, payments and available financial resources.
A business may be profitable on paper but unable to meet immediate expenses.
This commonly occurs when customers receive long credit periods while suppliers require faster payments.
Three important cash flow activities
Operating activities: Money generated or used through routine business operations, including customer collections and supplier payments.
Investing activities: Cash movements relating to assets and investments, such as purchasing machinery.
Financing activities: Cash received from or paid towards loans, capital and other financing arrangements.
TallyPrime provides cash flow reporting that helps businesses examine recorded cash movements.
These reports support decisions about expenditure, borrowing and working capital.
7. Cash Flow Statement and Cash Flow Projection in TallyPrime
The Cash Flow Statement helps business owners understand how cash and bank balances have changed over a selected period.
A Cash Flow Projection report helps estimate future cash movements using relevant accounting information.
Example of a monthly cash flow plan
|
Particulars
|
Amount
|
|---|
|
Opening cash and bank balance
|
₹3,00,000
|
|
Expected customer collections
|
₹8,00,000
|
|
Other expected receipts
|
₹50,000
|
|
Total available funds
|
₹11,50,000
|
|
Supplier payments
|
₹5,00,000
|
|
Salaries and wages
|
₹2,00,000
|
|
Rent and operating expenses
|
₹1,00,000
|
|
Loan instalments
|
₹75,000
|
|
Projected closing balance
|
₹2,75,000
|
This example shows how expected receipts and payments influence future liquidity.
Businesses should remember that projected collections are not guaranteed cash receipts.
Forecasts must be reviewed regularly and adjusted for delayed customer payments, unexpected expenses and changes in business activity.
8. Supplier Payment Management and Accounts Payable Control
Credit control is not limited to collecting customer payments.
Businesses must also manage payments owed to suppliers.
TallyPrime allows businesses to maintain supplier ledgers, record purchase invoices and monitor outstanding liabilities.
Why payable management matters
Paying suppliers too late can damage business relationships and interrupt the supply of goods.
Paying every supplier too early may unnecessarily reduce available working capital.
A structured payment plan helps businesses balance these competing requirements.
For example, a business may prioritise essential suppliers, invoices approaching their due dates and payments eligible for worthwhile early-payment discounts.
Supplier outstanding reports provide information required for these decisions.
9. Bank Reconciliation for Accurate Cash Balances
A reliable cash flow plan depends on accurate bank balances.
Differences between accounting records and bank statements may arise because of unpresented cheques, bank charges, delayed deposits or missing transactions.
TallyPrime provides bank reconciliation capabilities that help accountants identify and investigate these differences.
Depending on the installed release and supported bank formats, statement imports and automated reconciliation features may also be available.
Regular reconciliation helps businesses avoid making financial decisions based on incorrect bank balances.
It is particularly important for organisations processing large numbers of UPI, NEFT, RTGS and other electronic transactions.
10. Working Capital Management with TallyPrime
Working capital represents the resources available to support everyday business operations.
A commonly used calculation is:
Net Working Capital = Current Assets − Current Liabilities
Current assets may include cash, bank balances, receivables and inventory.
Current liabilities may include supplier payables, short-term borrowings and other obligations.
TallyPrime's Balance Sheet and supporting reports help businesses review these components.
Example
Suppose a trading business has current assets of ₹35 lakh and current liabilities of ₹24 lakh.
Its net working capital is ₹11 lakh.
However, positive working capital does not necessarily mean that sufficient cash is immediately available.
If a large portion of current assets consists of slow-moving inventory or overdue receivables, the business may still experience liquidity pressure.
Management should therefore examine asset quality and payment timing alongside the working capital figure.
11. How Inventory Management Affects Cash Flow
Inventory is closely connected to cash flow.
Businesses invest money in purchasing products before recovering that investment through sales and customer collections.
Excess stock can block working capital, while insufficient stock can cause lost sales.
TallyPrime provides inventory reports that help businesses monitor stock quantities, values and movements.
Practical inventory controls
Businesses can review stock ageing, monitor reorder requirements and identify slow-moving products.
For example, a distributor holding ₹10 lakh of slow-moving inventory may have limited funds available to purchase faster-selling products.
By examining stock movement reports, management can evaluate purchasing quantities and reduce unnecessary stock accumulation.
Inventory management and credit control should therefore be reviewed together.
12. Important Financial Ratios for Credit and Cash Flow Analysis
Financial ratios help management understand the effectiveness of credit and working capital policies.
Debtor Collection Period
This measures the approximate time taken to collect customer payments.
Formula:
Average Trade Receivables ÷ Net Credit Sales × Number of Days
A rising collection period may indicate slower customer payments.
Creditor Payment Period
This estimates the time taken to pay suppliers.
Formula:
Average Trade Payables ÷ Net Credit Purchases × Number of Days
The calculation should use a consistent accounting basis.
Current Ratio
Formula:
Current Assets ÷ Current Liabilities
This ratio helps assess short-term financial coverage.
Cash Conversion Cycle
The cash conversion cycle combines inventory holding time, receivables collection time and supplier payment time.
A shorter cycle generally indicates that money invested in operations is recovered more quickly.
TallyPrime provides financial and inventory information that can be used to calculate and monitor these ratios.
13. Case Study One: A Wholesale Distributor Reduces Overdue Receivables
Illustrative case study using hypothetical business figures.
A wholesale electrical distributor in Karol Bagh generated approximately ₹18 lakh in monthly credit sales.
The business supplied goods to retailers and contractors throughout Delhi NCR.
Although sales were increasing, customer collections were inconsistent.
The challenge
The distributor had outstanding receivables of ₹32 lakh, including several invoices overdue by more than 90 days.
The accounting team maintained payment follow-ups through spreadsheets.
The solution
The business introduced structured credit control using TallyPrime.
Customer credit limits and periods were configured, bill-wise outstanding tracking was implemented, and weekly ageing reports were reviewed.
The accounts team prioritised older invoices and reconciled customer statements.
Illustrative results
After four months, outstanding receivables declined from ₹32 lakh to ₹23 lakh.
The business also introduced management approval for exceptional credit sales.
The ₹9 lakh reduction represents a hypothetical improvement in outstanding balances, not additional profit.
The case demonstrates how disciplined collection procedures and reliable accounting reports can help improve working capital visibility.
14. Case Study Two: A Manufacturing Business Improves Cash Flow Planning
Illustrative case study representing a growing manufacturing enterprise.
A manufacturing company in Faridabad supplied components to industrial customers.
Its operations required regular purchases of raw materials, employee salaries and machinery maintenance.
Customers generally paid within 45–60 days, while suppliers expected payments within 30 days.
The challenge
The company frequently experienced cash shortages despite reporting operating profits.
Management had limited visibility into upcoming payments and expected collections.
The solution
The business began reviewing TallyPrime receivables, payables, cash flow and inventory reports.
A weekly cash flow forecast was prepared using recorded obligations and realistic collection assumptions.
Management also reviewed slow-moving inventory and renegotiated selected supplier payment schedules.
Illustrative outcome
The business identified periods when expected cash payments exceeded available funds.
This allowed management to plan financing requirements earlier and prioritise essential expenditure.
The case illustrates how cash flow forecasting can improve financial preparedness without guaranteeing higher profits.
15. Step-by-Step Credit Control Setup in TallyPrime
Businesses can establish a structured credit management process using the following steps.
Step 1: Enable bill-wise accounting. Open Gateway of Tally, press F11 and enable bill-wise entry under the relevant accounting features.
Step 2: Configure customer ledgers. Open or create the customer ledger under Sundry Debtors.
Step 3: Set credit limits. Enable the credit-limit field through the applicable F12 configuration and specify the approved customer limit.
Step 4: Define credit periods. Enable bill-wise balances for the customer and enter the default credit period.
Step 5: Record credit sales. Use Sales vouchers and assign appropriate bill references.
Step 6: Review receivables. Open the Bills Receivable or Outstanding reports to examine pending invoices and due dates.
Step 7: Record collections. Use Receipt vouchers and allocate payments against the appropriate outstanding references.
Step 8: Review credit exposure. Monitor overdue balances and customers approaching their credit limits.
Step 9: Analyse cash flow. Review cash and bank balances, supplier obligations and cash flow projections.
Step 10: Establish management reviews. Schedule weekly collection reviews and monthly working capital analysis.
Menu options may vary according to the installed TallyPrime release and company configuration.
16. Common Credit Control Mistakes Growing Businesses Should Avoid
One common mistake is allowing customers unlimited credit without evaluating payment history.
Another is recording receipts without allocating them against the correct outstanding invoices.
Businesses also make financial decisions based on sales figures without considering collection delays.
Other problems include inconsistent customer ledger records, incorrect opening balances and inadequate supplier payment planning.
Credit limits should be reviewed periodically rather than treated as permanent.
Businesses should also avoid assuming that every overdue customer is unwilling to pay. Invoice disputes, documentation errors and payment-processing delays may require different solutions.
Professional communication and accurate records are essential for maintaining healthy customer relationships.
17. TallyPrime on Cloud for Remote Credit and Cash Flow Monitoring
Business owners often need financial information while travelling or managing multiple offices.
TallyPrime on Cloud allows authorised users to access a centrally hosted accounting environment through a suitable internet connection.
This can help owners and accountants review receivables, payables, bank balances and financial reports from different locations.
For growing businesses, cloud hosting may simplify collaboration and reduce dependence on a single office computer.
However, cloud hosting does not automatically collect overdue payments or guarantee cash flow improvements.
Successful credit control still requires clear policies, timely accounting entries and consistent follow-up.
18. Building a Practical Credit and Cash Flow Review Routine
Growing businesses should establish a regular financial review process.
Daily reviews can focus on bank balances, major receipts and urgent payments.
Weekly reviews can examine overdue customers, supplier commitments and expected collections.
Monthly reviews should assess credit limits, receivables ageing, inventory investment and overall working capital.
Management should also compare actual collections with previous forecasts.
This helps identify whether cash flow assumptions are realistic.
Over time, a consistent review routine can improve financial discipline and reduce unexpected liquidity problems.
Conclusion: Strong Credit Control Creates Stronger Business Growth
Growing sales are important, but sustainable business growth depends on collecting payments, controlling credit exposure and maintaining sufficient working capital.
Businesses that neglect receivables and cash flow may experience financial pressure even when their sales and reported profits appear healthy.
TallyPrime provides accounting and reporting features that help organisations manage customer credit limits, track outstanding invoices, monitor supplier payments and analyse cash movements.
Its bill-wise accounting, ageing reports, bank reconciliation and financial statements support better financial visibility.
When combined with disciplined credit policies and realistic cash flow forecasting, these capabilities can help businesses make more informed decisions.
The objective of effective credit control is not simply to recover overdue payments. It is to protect customer relationships, maintain financial stability and ensure that business growth does not create unnecessary cash shortages.
Binarysoft Technologies can assist businesses in evaluating TallyPrime accounting configurations, credit management requirements, financial reporting and suitable cloud hosting arrangements.
Powered by Binarysoft Technologies Authorized Tally Partner
Location: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact us: +91 7428779101, 9205471661
Email us: tally@binarysoft.com
Business Hours: 10:00 AM – 6:00 PM, Monday to Friday
Frequently Asked Questions
What is credit control in TallyPrime?
Credit control in TallyPrime involves configuring customer credit limits and periods, tracking outstanding invoices and reviewing overdue payments through accounting reports.
Can TallyPrime set different credit limits for customers?
Yes. Businesses can configure individual credit limits for customer ledgers according to their approved credit policies.
How does TallyPrime track overdue customer payments?
TallyPrime provides bill-wise outstanding reports showing pending amounts, due dates and overdue periods.
Can TallyPrime generate a cash flow statement?
Yes. TallyPrime provides cash flow reports that help businesses analyse recorded cash inflows and outflows over selected periods.
CA. Raghav Mundhra focuses on business accounting, GST reporting, and financial reconciliations. He works with organizations to strengthen accounting processes and maintain reliable financial information for compliance and decision-making.