Call CA Tally HelpDesk
+91 9205471661,
7428779101
In 2026, many owner-managed companies in Nehru Place, Lajpat Nagar, Karol Bagh, and other Delhi trading hubs are not facing a single dramatic new accounting rule as much as a sharper operating reality. Online marketplaces, faster return cycles, tighter lender scrutiny, GST data trails, auditor questions, and management expectations are all pressing sellers to keep books that can explain every rupee from order to bank receipt. A company can show healthy sales on Amazon or other platforms and still struggle at year-end if marketplace fees, returns, tax collections, TCS, TDS, GST, and settlement deductions are not separated properly. The practical benefit of getting records right is clear: cleaner Schedule III Division I financial statements, faster audit support, more reliable profit numbers, fewer reconciliation surprises, and better decision-making before the year is closed.
Suggested URL slug: schedule-iii-division-i-tallyprime-excel-guide-2026-delhi-companies
Why This Guide Matters for Nehru Place and Lajpat Nagar Companies
Nehru Place and Lajpat Nagar are different markets, but the finance problems of their companies often look surprisingly similar. A Nehru Place company may sell laptops, printers, components, software bundles, CCTV equipment, accessories, refurbished devices, or installation services. A Lajpat Nagar company may sell garments, home decor, fashion accessories, imported lifestyle products, beauty items, or premium retail goods. Many of these companies now sell through a mix of counter sales, B2B invoices, website orders, Amazon, other marketplaces, WhatsApp enquiries, and occasional institutional supplies.
This mixed sales model creates a year-end challenge. Corporate financial statements under Schedule III Division I are not prepared from marketplace dashboards. They are prepared from books of account. If the books combine bank receipts with sales, or treat Amazon settlement deposits as the sale amount, the final balance sheet and statement of profit and loss can become misleading. The auditor may ask why sales as per GST returns do not match the ledger. The director may ask why bank deposits are lower than order value. The accountant may discover that returns were posted twice. The finance team may realize that TCS and TDS credits are lying unadjusted or are recorded under the wrong head.
Schedule III Division I is a presentation framework for companies that prepare financial statements under the relevant Indian accounting standards applicable to them, commonly non-Ind AS companies. A company must confirm its exact applicability with its accountant or statutory auditor because applicability can depend on the law, the company category, accounting standards, and updated notifications. This guide does not replace professional advice. It gives a practical route for organizing TallyPrime data, exporting it to Excel, and preparing year-end working papers that support financial statements.
The Real Accounting Pressure in 2026
The pressure in 2026 is not only from compliance. It is also from speed. Sellers are expected to decide prices quickly, hold inventory efficiently, claim tax credits on time, respond to marketplace disputes, and produce financial data whenever a lender, investor, auditor, or internal management team asks for it. A company that waits until March end to clean a full year of Amazon settlements can lose days or weeks in avoidable checking.
The pressure also comes from the nature of marketplace reports. Marketplace data is rich, but it is not the same as accounting data. An order report may show item price, shipping charge, promotional discount, tax, return status, and invoice number. A settlement report may show principal, commission, closing fee, shipping fee, technology fee, return fee, reimbursement, TCS, TDS, GST on fees, and net payable. The bank statement shows only the net amount credited. If the accountant treats the bank credit as revenue, the company loses the trail of gross sales, deductions, and statutory credits.
For corporate financial statements, these differences matter. Revenue, expenses, receivables, tax assets, GST payable or receivable, inventory, trade payables, bank balances, and other current assets must be reasonably classified and supported. Excel can be a strong bridge between TallyPrime reports and Schedule III schedules, but only when the underlying TallyPrime ledgers are clean.
Illustrative Story: A Gaffar Market Seller Who Learned the Cost of Late Reconciliation
Consider an illustrative story. It is not presented as a real customer case, but it reflects situations many Delhi sellers recognize.
Rohit runs a small private limited company near Gaffar Market. His father started with mobile accessories from a rented counter. Rohit added Amazon listings for chargers, cables, tempered glass, Bluetooth earphones, and replacement parts. During festival months, the online business moved faster than the shop. Staff packed orders late into the evening. The family felt proud when monthly marketplace orders crossed a level they had once thought impossible.
But the happiness faded during closing. The company had treated bank credits from the marketplace as sales. Returns were entered only when customers complained directly, not when the marketplace report marked an order as returned. Fees were booked as a single expense at the end of the year. TCS and TDS credits were not matched to monthly reports. GST outward data was prepared from invoices, but books were prepared from settlement receipts. Inventory showed quantities that did not agree with the warehouse count. Rohit thought the company had made a strong profit. After proper reconciliation, the profit was lower, some slow-moving items had to be reviewed, and several months of tax credits needed follow-up.
The difficult part was emotional. Rohit had not been careless; he had been busy. He knew his products, his suppliers, and his customers. What he lacked was a monthly accounting rhythm. Once the accountant separated gross sales, returns, marketplace deductions, taxes, and bank receipts, the business became clearer. He could see which product lines were profitable after fees and returns. He could answer auditor questions. He could discuss numbers with confidence. The lesson is simple: financial discipline is not a back-office luxury for sellers. It protects the business owner from making decisions on incomplete profit.
Understanding Schedule III Division I in Practical Language
Schedule III Division I gives a format and disclosure structure for corporate financial statements. For many companies using historical cost accounting under applicable Accounting Standards, it affects how the balance sheet, statement of profit and loss, and notes to accounts are presented. Companies should confirm current applicability, disclosure requirements, rounding norms, ageing schedules, ratio disclosures, and any updated MCA requirements with their statutory auditor or company secretary before finalization.
In practical terms, Schedule III Division I asks the finance team to avoid a casual ledger dump. It expects classification. Assets and liabilities are generally presented as current and non-current. Trade receivables should be separately identifiable. Trade payables should be classifiable. Borrowings, provisions, statutory dues, inventories, cash and bank balances, other financial assets where applicable, other current assets, revenue, other income, purchase of stock-in-trade, changes in inventories, employee benefit expenses, finance costs, depreciation, and other expenses need meaningful grouping.
For an Amazon seller or a multi-channel trading company, this means marketplace data cannot remain in a single ledger called Amazon. The company needs ledgers that support the required classification. Sales should not hide returns. Marketplace fees should not hide bank receipts. Tax credits should not be treated as ordinary expenses unless reviewed. Customer advances, supplier advances, inventory in transit, and statutory receivables should be visible.
Who Should Use This TallyPrime to Excel Guide
This guide is useful for private limited companies, closely held public companies, and other corporate entities in Delhi that maintain books in TallyPrime and prepare final accounts in Excel before audit. It is especially relevant for companies with online marketplace sales, mixed retail and wholesale operations, multiple GST registrations, branch stock transfers, or high-volume low-margin products.
The guide is also useful for founders who do not do the accounting themselves but want to ask the right questions. A director does not need to pass every voucher personally. However, the director should understand whether sales are recorded on an accrual basis, whether returns are posted correctly, whether marketplace deductions are separated, whether GST data agrees with books, and whether Excel schedules can be traced back to TallyPrime.
Because tax rates, thresholds, return filing rules, e-commerce tax collection rules, and TallyPrime features can change or differ by situation, this article deliberately avoids giving unsupported numerical claims. Always confirm current rates, statutory deadlines, threshold conditions, and software steps with your accountant, tax consultant, statutory auditor, and current TallyPrime product documentation.
The Big Mistake: Confusing Marketplace Reports with Bank Receipts
The most common mistake in marketplace accounting is treating the net bank settlement as the sale. The bank receipt is cash collection after multiple deductions and adjustments. It is not the same as revenue. For example, a marketplace may collect the selling price from the customer, deduct commission and fees, adjust returns, withhold statutory tax amounts, add reimbursements, and then transfer the net amount to the seller. If the seller records only the net bank amount as sales, revenue is understated, expenses are hidden, tax credits are missing, and reconciliation becomes almost impossible.
A second mistake is treating order value as final revenue without considering cancellations, returns, claims, and credit notes. Marketplace order reports often include orders that may later be cancelled, returned, or adjusted. The accounting entry should be supported by invoice status, shipping status, return status, and GST reporting logic approved by the accountant.
A third mistake is mixing marketplace receivable and marketplace fee ledgers. The marketplace can be both a collection agent and a service provider. Money receivable for customer sales should be separated from fees payable to the platform. When both are put into one ledger, year-end balances become difficult to explain.
Recommended Accounting Architecture in TallyPrime
A good TallyPrime structure begins with ledger discipline. Before posting large volumes, create a chart of accounts that supports both daily entry and year-end reporting. Avoid too many duplicate ledgers, but do not compress everything into generic names. The goal is to make the trial balance meaningful.
Sales Ledgers
Create separate sales ledgers based on business needs. A company may use ledgers such as Amazon Sales, Retail Counter Sales, B2B Sales, Website Sales, Export Sales if applicable, and Service Revenue if applicable. If GST treatment differs, consult your accountant on whether separate ledgers or voucher configurations are needed. In TallyPrime, GST classification and tax reporting depend on correct setup and voucher entry, so verify features and steps in current product documentation.
Returns and Credit Notes
Use credit notes for sales returns instead of reducing sales manually in a journal. Returns should be traceable to original invoices wherever possible. For marketplaces, return reports should be matched with order IDs, invoice numbers, SKU details, tax amounts, and whether the item was actually received back into saleable inventory. Some returns may be damaged, replaced, lost in transit, or reimbursed. Each category can have different accounting implications.
Marketplace Receivable Ledger
Create a ledger such as Amazon Marketplace Receivable under an appropriate current asset group or sundry debtor grouping, as advised by your accountant. When sales are booked, debit the marketplace receivable. When settlement is received in the bank, credit the marketplace receivable. When fees, TCS, TDS, reimbursements, claims, and adjustments are posted, they should also clear through the marketplace receivable so that the balance represents amounts still due or under reconciliation.
Marketplace Fee Ledgers
Separate major fee categories where analysis matters. Examples include marketplace commission, fulfilment fee, closing fee, shipping fee, storage fee, advertisement charges, packaging service charges, return processing fee, technology fee, and payment gateway or collection charges. Whether each category needs a separate ledger depends on volume, materiality, GST input credit tracking, and management reporting needs. Very small businesses may use fewer ledgers, but year-end clarity improves when recurring material charges are separated.
GST Ledgers
GST ledgers must be configured carefully. Output GST on sales, input GST on eligible purchases and expenses, GST on marketplace fees, GST payable, GST receivable, and adjustments should be reviewed monthly. GST eligibility, place of supply, e-invoicing applicability, credit note treatment, and return reporting should be confirmed with a tax professional. Do not assume that a marketplace deduction automatically gives eligible credit. The invoice, GSTIN, reporting, and eligibility conditions must be checked.
TCS and TDS Receivable Ledgers
Create separate ledgers for tax collected or deducted by the marketplace if applicable. These amounts are not ordinary expenses when they represent statutory credits available to the company, subject to matching and eligibility. Name them clearly, such as TCS Receivable under GST or TDS Receivable under Income Tax, based on nature. Confirm the exact treatment with your accountant because laws, rates, and credit mechanisms require current verification.
Inventory and Cost of Goods Sold
Trading companies should maintain item-wise stock where practical. Stock items should use consistent SKU mapping. If Amazon SKUs differ from internal SKUs, maintain a mapping sheet. Cost of goods sold and inventory valuation are central to profit accuracy. Schedule III presentation of inventories requires meaningful classification such as stock-in-trade, finished goods where applicable, raw materials where applicable, stores and spares, or other relevant categories depending on the business. Confirm classification with the auditor.
Amazon Data Sources: What to Collect Before Posting
Amazon and other marketplaces provide multiple reports. The exact report names and formats may change, so verify from the current seller portal. The accounting team should collect reports consistently each month, save them in a controlled folder, and avoid relying only on screenshots or dashboard totals. At a minimum, the finance file should support sales, returns, settlements, fees, tax withholding, GST reporting, inventory movement, and reimbursements.
- Order or sales report: Used to identify order IDs, invoice dates, customer charges, SKU details, tax amounts, shipping charges, discounts, cancellations, and status.
- Settlement report: Used to identify amounts collected, fees deducted, reimbursements, TCS, TDS, adjustments, and net amount transferred to bank.
- Return report: Used to identify returned orders, return dates, reasons, condition of goods, credit note requirements, and inventory impact.
- Tax report: Used to support GST outward supplies, marketplace tax collection or deduction details, and monthly return reconciliation.
- Fee invoices: Used to support marketplace fee expenses and GST input tax credit where eligible.
- Inventory report: Used to reconcile stock available, fulfilled, returned, damaged, or held in marketplace fulfilment centers, if applicable.
- Advertising report: Used when sponsored ads or promotional campaigns are charged separately or adjusted through settlements.
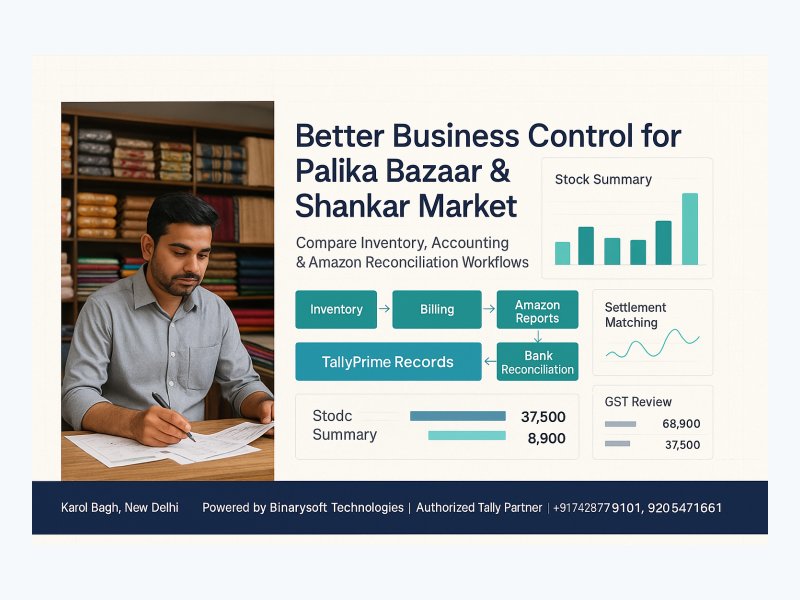
The key is not only downloading reports. The key is tying them together with order ID, settlement ID, invoice number, SKU, GSTIN, date, and amount. Excel is useful because it allows the accountant to clean, map, pivot, compare, and summarize data before posting or before finalizing schedules.
How to Record Amazon Sales in TallyPrime
The ideal method depends on volume. A low-volume seller may create invoice-level entries in TallyPrime. A high-volume seller may use summarized entries supported by detailed Excel workings, subject to auditor comfort and GST reporting requirements. The finance team should decide the policy at the start of the year, not after the audit begins.
At a conceptual level, marketplace sales accounting should capture gross sales and tax. If the marketplace is collecting money from customers on behalf of the seller, the seller records a receivable from the marketplace or customer collection agent. The bank entry later clears that receivable. This separates revenue recognition from cash receipt.
A simplified entry may look conceptually like this in accounting language: debit Amazon Marketplace Receivable, credit Sales, credit Output GST where applicable. This is only an illustrative structure. The actual entry must reflect invoice values, tax treatment, discounts, shipping charges, and any system configuration used by the company.
For companies in Nehru Place selling electronics, serial number tracking may also matter. Warranty claims, replacements, and refurbished returns can affect inventory and liabilities. For Lajpat Nagar fashion sellers, size, color, season, and return condition may matter more. The accounting system should be designed around the commercial reality of the products.
How to Record Returns Without Distorting Sales
Returns are a major reason online sales profits are misunderstood. A product may be sold in one month, returned in the next, and reimbursed or restocked later. If the return is ignored until year-end, revenue, GST, receivables, and inventory can all be wrong. If the return is posted twice, the result is equally misleading.
Use credit notes or appropriate return vouchers in TallyPrime, subject to GST and company policy. Map each return to the original sale wherever possible. The return entry should reduce receivable or create a payable adjustment through the marketplace ledger. It should also affect stock if the item is received back in saleable condition. If the item is damaged, lost, or not returned, accounting may involve claims, write-offs, or reimbursements. These should not be guessed. They should be supported by marketplace reports and reviewed by the accountant.
For Schedule III purposes, clean return accounting helps avoid inflated revenue and overstated trade receivables. It also supports better inventory valuation. If returned goods are unsaleable, the company may need to consider valuation impact. Inventory should generally not be shown above the amount expected to be realized, subject to applicable accounting standards and auditor review.
How to Record Marketplace Settlements
A settlement is the marketplace statement of what it owes the seller after collections, deductions, taxes, reimbursements, and adjustments. It is the bridge between sales and bank. The settlement entry should not be posted blindly as one receipt. It should be broken into components.
A practical settlement working in Excel usually starts with the gross amount collected for delivered orders. Then it lists deductions such as commission, fulfilment fees, shipping fees, return fees, advertising charges, service tax equivalents where historical data exists, GST on fees where applicable, TCS, TDS, refunds, claims, reimbursements, and other adjustments. The final total should match the exact amount credited to bank.
In TallyPrime, the bank receipt should be matched to the settlement ID. The entry may debit bank for the net amount, debit expense ledgers for fees, debit tax receivable ledgers for TCS or TDS, debit input GST where eligible, credit Amazon Marketplace Receivable for the gross amount adjusted, and record reimbursements or other credits appropriately. This is an illustrative approach. Actual voucher design may differ depending on TallyPrime configuration and accountant preference.
The settlement ledger balance after posting should be explainable. If there is a debit balance, it should represent unsettled sales, pending reimbursement, or timing differences. If there is a credit balance, it may indicate overposting, duplicate deductions, missing sales entries, or refunds not accounted for. Do not leave the balance unexplained at year-end.
How to Record Marketplace Fees
Marketplace fees reduce profit but should not reduce sales directly unless the accounting policy and presentation require netting in a specific situation approved by the auditor. For most trading sellers, platform fees are operating expenses. Separating them improves profitability analysis. A product that looks profitable before fees may be loss-making after commission, fulfilment, shipping, advertising, and returns.
The finance team should review fee invoices or settlement statements monthly. If GST is charged on fees and the company is eligible for input credit, the GST component should be recorded separately as input tax credit, subject to invoice availability, GSTIN correctness, matching, and eligibility conditions. If credit is not eligible or not claimed, the treatment should be reviewed with the tax consultant.
Separate advertising fees from selling commission if management wants product-level profitability. Sponsored ads can become a major cost during festival campaigns. If they are hidden in a generic marketplace expense ledger, the business may not realize why margins fell.
How to Organize TCS, TDS, and GST Data
E-commerce transactions can involve tax collected at source under GST, tax deducted at source under income tax, output GST on supplies, input GST on expenses, and credit note adjustments. The exact provisions, rates, thresholds, forms, due dates, and matching process should be confirmed with your accountant and current government portals. This guide focuses on organization, not rate advice.
Create separate ledgers for each type of tax receivable or payable. Do not mix TCS under GST with TDS under income tax. Do not put tax credits into marketplace commission. Do not leave tax credits inside the marketplace receivable ledger without a schedule. At month-end, reconcile tax credits as per marketplace report with amounts visible on relevant government portals when available. Differences should be followed up quickly because old mismatches are harder to resolve.
For GST, reconcile sales as per TallyPrime with outward supplies reported in GST returns. Reconcile credit notes as per books with credit notes reported for GST. Reconcile input tax credit on marketplace fee invoices with eligible credits as per the portal and company policy. If there are multiple GST registrations, branch-wise or GSTIN-wise separation becomes critical.
GST Data Discipline for Delhi Sellers
GST compliance is not only return filing. It is data discipline. A Delhi seller may sell within Delhi, to other states, through marketplace fulfilment centers, to business buyers, and to retail customers. Place of supply, invoice format, GSTIN details, HSN or SAC classification, taxability, discounts, credit notes, and e-way or e-invoice applicability where relevant should be reviewed with professionals. This article does not provide legal classification advice.
In TallyPrime, ensure that company GST details are set correctly, ledgers are configured consistently, stock items carry correct tax information where applicable, and vouchers are entered using the intended tax structure. Product documentation should be checked for the current release because features, screens, and workflows can evolve. If data is imported, validate sample invoices before bulk posting.
At the end of every month, compare four numbers: sales as per TallyPrime, sales as per marketplace reports, sales as per GST working, and sales as per management dashboard. These numbers may not be identical because of timing, returns, cancellations, or tax logic, but the differences should be documented. Unexplained differences become audit stress.
TallyPrime to Excel: Why Excel Still Matters
TallyPrime is the accounting system. Excel is the working paper environment. For financial statement preparation, Excel helps accountants create schedules, classify balances, perform ageing, reconcile reports, prepare ratio workings, compare previous year numbers, and support audit queries. The objective is not to replace TallyPrime with Excel. The objective is to use Excel as a controlled bridge from books to presentation.
Depending on the TallyPrime release and configuration, reports can usually be exported in spreadsheet-compatible formats through available export options. Users should verify current steps in product documentation or with an authorized Tally partner. Commonly exported reports include trial balance, ledger vouchers, sales register, purchase register, journal register, GST reports, stock summary, outstanding statements, receivables ageing, payables ageing, day book, cash and bank books, and group summaries.
Once exported, Excel should not become an uncontrolled second set of books. Every adjustment in Excel should have a reference, explanation, preparer name, reviewer status, and whether it has been posted back into TallyPrime. Audit teams often ask whether final financial statements agree with the books. If Excel changes are not posted or tracked, the company may face avoidable delays.
A Practical TallyPrime to Excel Closing Workflow
A structured workflow saves time. The following approach works well for many small and mid-sized companies, but it should be adapted to the company size, auditor requirements, and software configuration.
Step 1: Freeze the Master Data Policy
Before exporting, clean the ledger list. Merge duplicates only after proper review. Correct obvious spelling variations. Ensure marketplace receivable, fee, tax, inventory, bank, customer, supplier, loan, advance, and statutory ledgers are grouped properly. Schedule III schedules depend heavily on grouping.
Step 2: Export Trial Balance
Export the trial balance at year-end with previous year comparison if available. Check whether the debit and credit totals agree. Review negative balances. A supplier with a debit balance may be an advance or overpayment. A customer with a credit balance may be an advance or refund liability. Reclassify only after checking ledger details.
Step 3: Export Ledger Details for Key Accounts
For Amazon receivable, bank accounts, GST ledgers, TCS, TDS, sales, returns, purchases, inventory adjustments, loans, director accounts, and major expenses, export detailed ledgers. These details support reconciliation and audit sampling.
Step 4: Export Sales and Credit Note Registers
Compare sales and return vouchers with marketplace reports. Check if all months are covered. Verify large credit notes. Review cancellations and return timing. Confirm whether sales are recorded on invoice date, shipment date, delivery date, or another policy accepted by the accountant.
Step 5: Export Bank Book
Match every marketplace settlement receipt to settlement reports. Do not leave entries named only Amazon without settlement references. Add narration or supporting reference numbers where possible. Bank reconciliation should identify cheques issued, charges, failed payments, deposits in transit, and direct debits.
Step 6: Prepare Excel Control Sheet
Create a control sheet listing all exported reports, export date, Tally company name, financial year, period covered, prepared by, and file location. This simple sheet prevents confusion when multiple versions are shared during audit.
Step 7: Map Trial Balance to Schedule III Heads
In Excel, create mapping columns for Schedule III head, sub-head, current or non-current classification, notes reference, and remarks. For example, bank balances map to cash and bank balances, marketplace receivable may map to trade receivables or other current assets depending on facts and auditor view, GST receivable may map to other current assets, and marketplace fees map to other expenses or selling and distribution expenses as considered appropriate.
Step 8: Prepare Lead Schedules
For each financial statement line item, prepare a lead schedule that agrees to the mapped trial balance. Attach supporting schedules for major balances. Trade receivables, trade payables, loans, advances, GST balances, inventories, and fixed assets generally need detailed support.
Step 9: Review Adjustments
Identify year-end provisions, prepaid expenses, accrued expenses, depreciation, inventory valuation adjustments, bad debt provisions, statutory liabilities, income tax provisions, audit fee provisions, and other closing entries. Post approved entries into TallyPrime wherever required, then re-export the final trial balance.
Step 10: Lock the Final Pack
Once financial statements are finalized, save the final TallyPrime export, Excel workbook, signed financial statements, audit schedules, tax reconciliations, and management approval notes in a secure folder. If using cloud access, ensure user rights and backups are controlled.
Mapping Common TallyPrime Ledgers to Schedule III Division I
Mapping is where accounting becomes presentation. The same ledger may be classified differently depending on facts. Therefore, the following examples are illustrative and should be reviewed by the auditor.
- Amazon Marketplace Receivable: Usually reviewed as a receivable or other current asset depending on relationship, settlement cycle, and accounting policy.
- Amazon Commission Expense: Usually considered part of selling, distribution, or other expenses depending on presentation policy.
- GST Input Credit: Usually reviewed under statutory receivables or other current assets if recoverable.
- GST Payable: Usually reviewed under statutory dues within current liabilities.
- TCS Receivable and TDS Receivable: Usually reviewed under other current assets or tax assets depending on nature and recoverability.
- Customer Advances: Usually classified under current liabilities if goods or services are yet to be delivered.
- Supplier Advances: Usually classified under loans and advances or other current assets depending on nature.
- Inventory in Marketplace Fulfilment Center: Usually part of inventory if risks and ownership remain with the company, subject to verification.
- Damaged or Obsolete Stock: Requires valuation review and possible provision or write-down as per applicable standards.
- Director Current Account: Requires careful review for legal, tax, and disclosure implications; do not classify casually.
Schedule III presentation also involves notes. A clean trial balance is not enough. The company may need disclosures for share capital, reserves, borrowings, trade payables ageing, trade receivables ageing, fixed assets, inventories, revenue, employee benefits, statutory dues, contingent liabilities, related parties where applicable, and other items. Confirm current requirements with the auditor.
Common Reconciliation Mistakes and How to Avoid Them
Reconciliation is not a once-a-year punishment. It is a monthly habit. The following mistakes are common in Delhi trading companies and can be reduced with a disciplined workflow.
Mistake 1: Booking Net Settlement as Sales
This hides marketplace fees, tax credits, and gross revenue. Avoid it by using a marketplace receivable ledger and posting settlements component-wise.
Mistake 2: Ignoring Returns Until Year-End
This inflates sales and receivables. Avoid it by downloading return reports monthly and posting credit notes promptly.
Mistake 3: Duplicating Returned Orders
Sometimes the sales report is imported again after returns, and credit notes are also posted separately without matching. Avoid it by using order IDs and invoice numbers as reconciliation keys.
Mistake 4: Treating TCS or TDS as Expense
Tax amounts deducted or collected may be credits receivable, subject to eligibility and matching. Avoid errors by maintaining separate tax receivable ledgers and reconciling with portal data.
Mistake 5: Not Matching GST Reports
Sales as per books, GST returns, and marketplace tax reports should be compared. Differences should be explained month-wise.
Mistake 6: Combining Personal and Company Transactions
Owner-managed companies sometimes pay small expenses personally or use company accounts for non-business items. This complicates audit and tax review. Maintain clear director account documentation and approvals.
Mistake 7: No SKU Mapping
If internal SKU names differ from marketplace SKUs, inventory and profitability reports become unreliable. Maintain a master SKU mapping sheet and update it when new listings are created.
Mistake 8: Leaving Old Balances Unexplained
Old receivable, payable, GST, TCS, TDS, and advance balances weaken financial statements. Age and review them before the audit starts.
Practical Example: One Amazon Sale from Order to Settlement
Assume a Delhi company sells a product through a marketplace. The customer pays the marketplace. The marketplace report shows item value, shipping amount if charged, tax, promotional discount if any, and final invoice value. Later, the settlement report shows marketplace commission, shipping or fulfilment fee, GST on platform fees where applicable, TCS, TDS, and net amount deposited into the company bank account. The exact tax amounts and rates are deliberately not stated here because they must be verified for the current period and transaction type.
The accounting thought process is as follows. First, record the sale at the appropriate invoice value with output tax if applicable and debit the marketplace receivable. Second, when the settlement arrives, debit bank for the net receipt. Third, debit marketplace fee expense ledgers for charges. Fourth, debit input tax credit if eligible and supported. Fifth, debit TCS or TDS receivable ledgers if applicable. Sixth, credit marketplace receivable for the total settled amount. Seventh, investigate any difference between the settlement statement and receivable ledger.
If the product is later returned, post a credit note and update inventory depending on the condition of the goods. If the marketplace reimburses the seller for a lost item, record the reimbursement according to its nature. Do not classify every reimbursement as sales. Some reimbursements may offset loss, expense, or receivable. Review with the accountant.
Practical Example: Reconciling a Month of Sales
At month-end, the finance team exports the Amazon order report, return report, settlement report, and fee invoice data. It also exports sales register, credit note register, bank book, GST report, and marketplace receivable ledger from TallyPrime. In Excel, the team creates a reconciliation workbook.
The first sheet lists order-wise gross invoices as per marketplace. The second sheet lists sales vouchers as per TallyPrime. A lookup compares invoice numbers and amounts. Differences are tagged as missing in Tally, missing in marketplace, amount difference, date difference, cancellation, return, or tax difference. The third sheet compares return report with credit notes. The fourth sheet compares settlement IDs with bank receipts. The fifth sheet summarizes marketplace fees and tax credits. The final sheet gives a month-end reconciliation summary.
The summary may show that sales as per marketplace are higher than TallyPrime because some cancelled orders were included in the raw report. It may show that TallyPrime has invoices not in the settlement because the settlement will occur next month. It may show that bank receipts are lower because fees and taxes were deducted. These are not problems if they are explained. The problem is unexplained difference.
Practical Example: Schedule III Working for Marketplace Receivable
Suppose the Amazon Marketplace Receivable ledger shows a debit balance at year-end. The accountant should not simply carry it into the balance sheet without analysis. The balance may include unsettled invoices from late March, pending reimbursements, fee disputes, TCS or TDS amounts not transferred to separate ledgers, unmatched refunds, or duplicate entries.
In Excel, prepare an ageing and nature analysis. Separate current settlement pending, claims pending, tax credit pending transfer, disputed amounts, and old unreconciled balances. For old items, ask whether they are recoverable. If not, discuss provision or write-off with the auditor. This analysis supports classification and valuation in financial statements.
For Schedule III presentation, the auditor may ask whether the balance is a trade receivable, other receivable, statutory asset, or adjustment account. The answer depends on the underlying nature. A properly prepared Excel schedule gives evidence.
Inventory Controls for Electronics, Accessories, Garments, and Retail Goods
Inventory is often the largest number after sales. In Nehru Place, electronics and accessories may have fast model changes, warranty returns, serial numbers, and price erosion. In Lajpat Nagar, garments and lifestyle products may have seasonality, sizes, colors, and fashion risk. For Amazon sellers, inventory may also sit in warehouses or fulfilment centers outside the shop.
Use item masters consistently. Record purchases with SKU details. Track stock transfers between shop, warehouse, and marketplace fulfilment locations if ownership remains with the company. Conduct physical verification periodically. Match physical count with TallyPrime stock summary and marketplace inventory reports. Investigate shortages, damages, obsolete items, and negative stock.
At year-end, inventory valuation should be reviewed under applicable accounting standards. The accountant should consider cost, net realizable value where relevant, damaged goods, old models, and slow-moving stock. Tax and accounting treatment of discounts, schemes, purchase returns, and supplier credit notes should also be considered. Do not rely only on quantity reports. Value matters.
Trade Receivables and Ageing
For corporate financial statements, trade receivables usually require careful ageing and review. Marketplace receivables settle quickly in normal cases, but B2B customers, institutional clients, service customers, and dealers may have longer cycles. Export outstanding receivables from TallyPrime and prepare an ageing schedule in Excel. Verify whether balances are good, doubtful, disputed, or subject to credit notes.
Customer balances should be confirmed where practical, especially for material amounts. If a customer has both sales and purchase transactions, avoid netting without proper right of set-off and auditor approval. If old balances are not recoverable, discuss provision or write-off. Schedule III disclosure requirements for ageing and disputed amounts should be verified with the current format and auditor instructions.
Trade Payables and MSME Considerations
Trade payables also require ageing and classification. Suppliers in Delhi markets may be wholesalers, importers, distributors, manufacturers, logistics providers, repair vendors, packaging suppliers, or advertising agencies. Export payables from TallyPrime and verify balances. Reconcile major supplier statements. Identify debit balances, advances, old disputes, and credit notes pending.
MSME classification and disclosure can be sensitive. Companies should obtain supplier declarations where required and confirm current legal requirements with their accountant or company secretary. Do not assume that a supplier is or is not covered. Proper classification can affect disclosures and compliance.
Fixed Assets, Depreciation, and Small Business Reality
Even trading companies have fixed assets: computers, billing machines, printers, racks, furniture, CCTV cameras, office equipment, delivery equipment, software, and leasehold improvements. Maintain a fixed asset register that agrees with TallyPrime. Record additions with invoice details, date of put-to-use, location, and GST treatment. Record disposals and write-offs properly.
Depreciation rates and methods should be calculated under applicable company law and accounting policy, and tax depreciation may differ. Confirm current requirements with the accountant. In Excel, maintain a depreciation working that reconciles opening gross block, additions, deletions, closing gross block, accumulated depreciation, and net block. This supports Schedule III notes.
Loans, Borrowings, and Director Balances
Many owner-managed companies use bank overdrafts, working capital loans, unsecured loans, director funding, or credit card facilities. Schedule III classification requires more than listing a total. The accountant should identify secured and unsecured borrowings, current maturities, interest accrued, repayment terms, and related party nature where applicable. Bank confirmations and loan statements should be obtained.
Director balances should be handled carefully. Payments to directors, reimbursements, loans, advances, salary, rent, interest, and personal expenses can have legal and tax implications. Do not adjust these casually at year-end. Maintain documentation, approvals, and supporting bills. Related party disclosure requirements should be verified with the auditor.
Revenue Presentation: Gross, Net, Discounts, and Schemes
Revenue presentation is an area where sellers often need professional judgment. Gross product sales, discounts, promotional schemes, shipping charges, gift wrap charges, reimbursements, and marketplace-funded promotions may need different treatment depending on facts. Some discounts reduce revenue. Some reimbursements may be other income or expense recovery. Some shipping charges may be part of customer billing and related delivery costs may be expenses.
The safest approach is consistency and documentation. Create a revenue policy note for internal use. State how marketplace sales are recorded, how discounts are treated, when returns are recognized, how reimbursements are classified, and how GST data is reconciled. Share the policy with the auditor before year-end if the amounts are material.
Expense Classification for Schedule III
Expenses should be classified in a way that supports the statement of profit and loss and notes. Common expenses for Delhi sellers include purchases, freight inward, freight outward, marketplace commission, fulfilment fees, packing material, salaries, rent, electricity, repair and maintenance, internet, software subscriptions, accounting fees, audit fees, legal fees, bank charges, interest, advertising, sales promotion, travel, depreciation, and miscellaneous office expenses.
Avoid using one large ledger called general expenses for recurring material items. It weakens management reporting and audit review. At the same time, avoid excessive micro-ledgers that no one can maintain. The right structure is balanced: detailed enough to explain performance, simple enough for daily accounting.
Year-End Closing Checklist for TallyPrime Users
Use this checklist before sending books for audit or preparing final Schedule III statements.
- Company master: Confirm company name, financial year, GST registrations, address, and statutory details in TallyPrime.
- Backup: Take verified backups before major year-end adjustments or migrations.
- Ledger grouping: Review all ledgers for correct groups and Schedule III mapping.
- Sales reconciliation: Match TallyPrime sales with marketplace reports, GST workings, and management dashboards.
- Returns: Ensure all credit notes are posted and linked to return reports.
- Settlements: Match every marketplace settlement to bank credits and settlement IDs.
- Fees: Post marketplace fees separately and check GST on fee invoices where relevant.
- TCS and TDS: Reconcile tax credits with marketplace reports and portal data where available.
- GST: Reconcile output tax, input tax credit, credit notes, and statutory dues.
- Bank reconciliation: Complete bank reconciliation for all bank accounts, overdrafts, and payment gateways.
- Inventory: Match physical stock, TallyPrime stock, marketplace inventory, damaged goods, and valuation working.
- Receivables: Prepare ageing, confirm major balances, and review doubtful debts.
- Payables: Prepare ageing, reconcile supplier statements, and identify MSME-related data where required.
- Fixed assets: Update asset register, depreciation, additions, deletions, and physical verification.
- Loans: Obtain loan statements, interest certificates, and confirmations.
- Provisions: Record audit fees, expenses payable, statutory liabilities, employee costs, and other accruals.
- Prepaids: Identify insurance, subscriptions, rent, maintenance, and other prepaid expenses.
- Related parties: Review director, group company, relative, and common control transactions.
- Excel schedules: Ensure every final schedule agrees with the final trial balance.
- Audit trail: Maintain export files, working papers, explanations, and approval notes.
Monthly Checklist for Amazon Sellers
A month-end routine prevents year-end panic. Complete the following within a reasonable number of days after month-end, based on your internal deadline and accountant availability.
- Download marketplace order, settlement, fee, return, tax, and inventory reports.
- Save reports in a month-wise folder with consistent file names.
- Post or import sales according to the approved accounting policy.
- Post credit notes for returns and verify GST impact.
- Post settlement entries component-wise, not as net sales.
- Reconcile bank credits with settlement IDs.
- Transfer TCS and TDS amounts to separate receivable ledgers.
- Check input GST on marketplace fee invoices where eligible.
- Compare GST outward liability with TallyPrime reports and tax working.
- Review negative stock, damaged stock, and slow-moving items.
- Prepare a one-page reconciliation summary for management review.
Excel Workbook Structure for Financial Statement Preparation
A good Excel closing workbook should be easy to review. Use separate sheets for index, control totals, trial balance, mapping, lead schedules, sales reconciliation, GST reconciliation, marketplace reconciliation, bank reconciliation, receivables ageing, payables ageing, inventory valuation, fixed assets, loans, provisions, tax credits, related parties, and final financial statement links.
Use formulas carefully. Lock formulas where possible. Avoid hard-coded numbers in final schedules unless clearly marked. Use references to trial balance rows. Include a check column that compares each schedule total with the mapped trial balance amount. Highlight differences. Keep prior year numbers in separate columns for comparison. Use comments or remarks columns for unusual balances.
Do not send multiple uncontrolled versions to directors and auditors. Use version names with dates. When an adjustment is posted in TallyPrime, update the export and refresh the workbook. The final financial statements should be prepared from the final books, not an old trial balance.
Data Security and Tally on Cloud Considerations
Many Delhi companies use remote access or cloud-hosted environments for TallyPrime to allow accountants, directors, and consultants to work from different locations. This can improve speed, but it also requires controls. User access should be role-based. Backups should be scheduled and tested. Passwords should not be shared casually. Data exports should be stored securely because they contain customer, supplier, tax, and financial information.
If the company uses TallyPrime in a cloud or hosted setup, verify performance, backup policy, user rights, data ownership, support process, and compatibility with your version. Also confirm whether integrations, import tools, and Excel exports work as expected in that environment. A finance process is only reliable when the data environment is reliable.
What Directors Should Ask Their Accountant Before Signing Financial Statements
Directors do not need to become accountants, but they should ask focused questions before approving financial statements. These questions often reveal whether the books are truly ready.
- Do sales as per books reconcile with marketplace reports and GST returns?
- Are returns and credit notes fully posted up to year-end?
- Is the marketplace receivable balance supported by settlement-wise details?
- Are marketplace fees recorded separately from sales?
- Are TCS and TDS credits reconciled and recoverable?
- Are GST receivable and payable balances supported by return workings?
- Does inventory as per books agree with physical and marketplace stock reports?
- Have old receivables and payables been reviewed?
- Are director balances and related party transactions properly documented?
- Do Excel schedules agree with the final TallyPrime trial balance?
- Has the auditor reviewed classification under Schedule III Division I?
These questions do not slow down closing. They reduce last-minute surprises. A director who understands the quality of accounting data can make better pricing, borrowing, hiring, and expansion decisions.
2026 Verification Points: What Not to Assume
Because accounting, tax, and software environments can change, the finance team should maintain a verification list. This is especially important for companies preparing 2026 financial statements or planning accounting processes for the 2026 year.
- Confirm whether Schedule III Division I applies to the company or whether another division or framework is applicable.
- Confirm current Schedule III disclosure requirements, including ageing, ratios, rounding, and any company-specific disclosures.
- Confirm GST rates, HSN or SAC classification, place of supply, credit note rules, e-invoicing applicability, and return filing requirements.
- Confirm e-commerce TCS and income tax TDS applicability, rates, credit availability, and portal matching process.
- Confirm income tax provisions, audit requirements, due dates, and reporting obligations with a tax professional.
- Confirm TallyPrime features, export methods, GST report behavior, import options, user controls, and release-specific workflows from current documentation.
- Confirm marketplace report formats and fields because seller portal reports may change over time.
- Confirm auditor expectations before finalizing summarised entries or Excel-based schedules.
This verification discipline protects the company from relying on old assumptions. It also helps the accountant explain why a particular treatment was used.
How Clean Books Improve Business Decisions
Clean accounting is not only for statutory compliance. It changes daily business decisions. When fees are separated, the company can identify profitable channels. When returns are measured, it can improve product descriptions, packaging, or supplier quality. When GST and tax credits are reconciled, cash flow forecasting improves. When inventory is accurate, purchasing becomes sharper. When receivables ageing is visible, collection calls become timely.
For a Nehru Place electronics company, this may mean discontinuing a model that sells fast but returns often. For a Lajpat Nagar apparel company, it may mean adjusting size charts or reducing festival ad spend on low-margin products. For a Karol Bagh accessories seller, it may mean negotiating better marketplace fulfilment terms or supplier credit. Financial statements prepared under Schedule III are an output, but the underlying accounting discipline is a management tool.
Preparing for Audit Without Panic
Auditors usually ask for trial balance, ledgers, bank statements, confirmations, GST returns, tax challans, marketplace reports, sales and purchase registers, fixed asset register, inventory valuation, loan documents, ageing schedules, related party details, and board approvals where relevant. A company that prepares these documents throughout the year can complete audit work faster and with fewer interruptions.
Create an audit request folder. Use subfolders for statutory records, bank, sales, purchases, marketplace, GST, TDS, TCS, payroll, fixed assets, inventory, receivables, payables, loans, legal documents, and management representations. Maintain an audit query tracker in Excel with columns for query, responsible person, due date, response, supporting file, and status. This simple tracker reduces repeated questions and confusion.
When to Use Automation and When to Use Manual Review
Automation can help import high-volume marketplace data into TallyPrime, but automation is not a substitute for accounting judgment. If mappings are wrong, automation repeats the wrong entry hundreds or thousands of times. Before using import tools, test a small sample. Check sales, GST, returns, fees, TCS, TDS, settlement clearing, inventory impact, and narration quality. Get accountant approval before full import.
Manual review is essential for unusual transactions: large claims, damaged stock, disputed settlements, reimbursement entries, old balances, director transactions, legal expenses, warranty provisions, and tax mismatches. A good finance process uses automation for repetitive structured data and human review for judgment-heavy items.
Local Practical Tips for Delhi Trading Hubs
Businesses in Nehru Place, Lajpat Nagar, Karol Bagh, and nearby markets often operate with high transaction speed and lean staff. The following habits are practical and realistic.
- Give every marketplace settlement a reference number in TallyPrime narration.
- Keep a shared month-wise folder for marketplace reports and bank statements.
- Do not allow staff to create duplicate item names without approval.
- Review cash sales and digital collections separately.
- Deposit cash promptly and maintain supporting records.
- Separate repair, replacement, warranty, and resale transactions.
- Review supplier credit notes monthly, especially for schemes and defective goods.
- Keep director approvals for major write-offs and provisions.
- Schedule a monthly finance review before the next month becomes too busy.
Natural Closing Call to Action
If your company is preparing Schedule III Division I financial statements, cleaning Amazon marketplace accounting, or building a TallyPrime to Excel closing process for 2026, experienced local support can save time and reduce avoidable errors. Tally@Cloud solutions and TallyPrime guidance can help your accounting team work with cleaner data, better access, and stronger year-end schedules.
Powered by Binarysoft Technologies, Authorized Tally Partner, 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi - 110005, INDIA. For assistance, contact +91 7428779101, 9205471661 or email tally@binarysoft.com. Contact hours: 10:00 AM - 6:00 PM, Mon-Fri.
Conclusion
Corporate financial statements under Schedule III Division I are much easier to prepare when the accounting system is designed for clarity from the beginning. For Nehru Place and Lajpat Nagar companies selling through Amazon and other channels, the most important discipline is separating sales, returns, settlements, fees, TCS, TDS, GST, inventory, and bank receipts. TallyPrime should hold the accounting truth, while Excel should organize reconciliations, mappings, and financial statement schedules. Do not wait for audit season to discover that net bank receipts were booked as sales or that tax credits were never reconciled. Build a monthly process, verify current tax and software requirements, keep supporting reports, and map ledgers carefully to Schedule III heads. Clean books do more than satisfy compliance. They help owners understand profit, protect cash flow, answer auditors confidently, and make better business decisions in a fast-moving 2026 market.
FAQ
Does Schedule III Division I apply to every company in Nehru Place or Lajpat Nagar?
No. Applicability depends on the company type, accounting framework, and current legal requirements. Many non-Ind AS companies use Schedule III Division I, but every company should confirm the correct division and disclosure format with its statutory auditor or company secretary.
Should Amazon settlement deposits be recorded as sales in TallyPrime?
Generally, the net settlement deposit should not be treated as the full sale. It is a bank receipt after deductions and adjustments. Sales, returns, marketplace fees, tax credits, and bank receipts should be recorded separately so that revenue and expenses are not distorted.
How should TCS and TDS from marketplace reports be handled?
TCS and TDS should usually be tracked in separate receivable ledgers according to their nature, subject to eligibility and portal matching. Do not mix them with commission expense or leave them hidden in marketplace receivable. Confirm rates, applicability, and credit process with your accountant.
Can Excel be used to prepare Schedule III financial statements from TallyPrime?
Yes. Excel is commonly used for mapping the trial balance, preparing lead schedules, ageing, reconciliations, and financial statement workings. However, Excel should reconcile to the final TallyPrime trial balance, and all material adjustments should be documented and posted where required.
What is the most common Amazon accounting error for sellers?
The most common error is confusing bank receipts with revenue. Another common error is ignoring returns and credit notes until year-end. Both mistakes can affect sales, GST, receivables, inventory, and profit.
How often should marketplace sales and GST data be reconciled?
A monthly reconciliation is strongly recommended. Compare TallyPrime sales, marketplace reports, credit notes, settlement reports, bank receipts, and GST workings. Monthly review prevents old differences from becoming year-end audit problems.
Do TallyPrime features and GST reports need current verification?
Yes. TallyPrime releases, marketplace report formats, GST rules, tax rates, and statutory requirements can change. Verify current product documentation and consult your accountant before relying on any workflow, tax treatment, or filing assumption.
Frequently Asked Questions
Does Schedule III Division I apply to every company in Nehru Place or Lajpat Nagar?
No. Applicability depends on the company type, accounting framework, and current legal requirements. Many non-Ind AS companies use Schedule III Division I, but every company should confirm the correct division and disclosure format with its statutory auditor or company secretary.
Should Amazon settlement deposits be recorded as sales in TallyPrime?
Generally, the net settlement deposit should not be treated as the full sale. It is a bank receipt after deductions and adjustments. Sales, returns, marketplace fees, tax credits, and bank receipts should be recorded separately so that revenue and expenses are not distorted.
How should TCS and TDS from marketplace reports be handled?
TCS and TDS should usually be tracked in separate receivable ledgers according to their nature, subject to eligibility and portal matching. Do not mix them with commission expense or leave them hidden in marketplace receivable. Confirm rates, applicability, and credit process with your accountant.
Can Excel be used to prepare Schedule III financial statements from TallyPrime?
Yes. Excel is commonly used for mapping the trial balance, preparing lead schedules, ageing, reconciliations, and financial statement workings. However, Excel should reconcile to the final TallyPrime trial balance, and all material adjustments should be documented and posted where required.
What is the most common Amazon accounting error for sellers?
The most common error is confusing bank receipts with revenue. Another common error is ignoring returns and credit notes until year-end. Both mistakes can affect sales, GST, receivables, inventory, and profit.
How often should marketplace sales and GST data be reconciled?
A monthly reconciliation is strongly recommended. Compare TallyPrime sales, marketplace reports, credit notes, settlement reports, bank receipts, and GST workings. Monthly review prevents old differences from becoming year-end audit problems.
Do TallyPrime features and GST reports need current verification?
Yes. TallyPrime releases, marketplace report formats, GST rules, tax rates, and statutory requirements can change. Verify current product documentation and consult your accountant before relying on any workflow, tax treatment, or filing assumption.
CA. Praneet Bansaal is a Chartered Accountant with experience in taxation, accounting controls, and financial process reviews. He has advised businesses on aligning inventory movement with accounting and GST requirements. His content focuses on compliance, accuracy, and long-term sustainability.